Published: Wednesday, October 14, 2026 · 2:14 AM | Updated: Wednesday, October 14, 2026 · 2:14 AM
📊 19 views


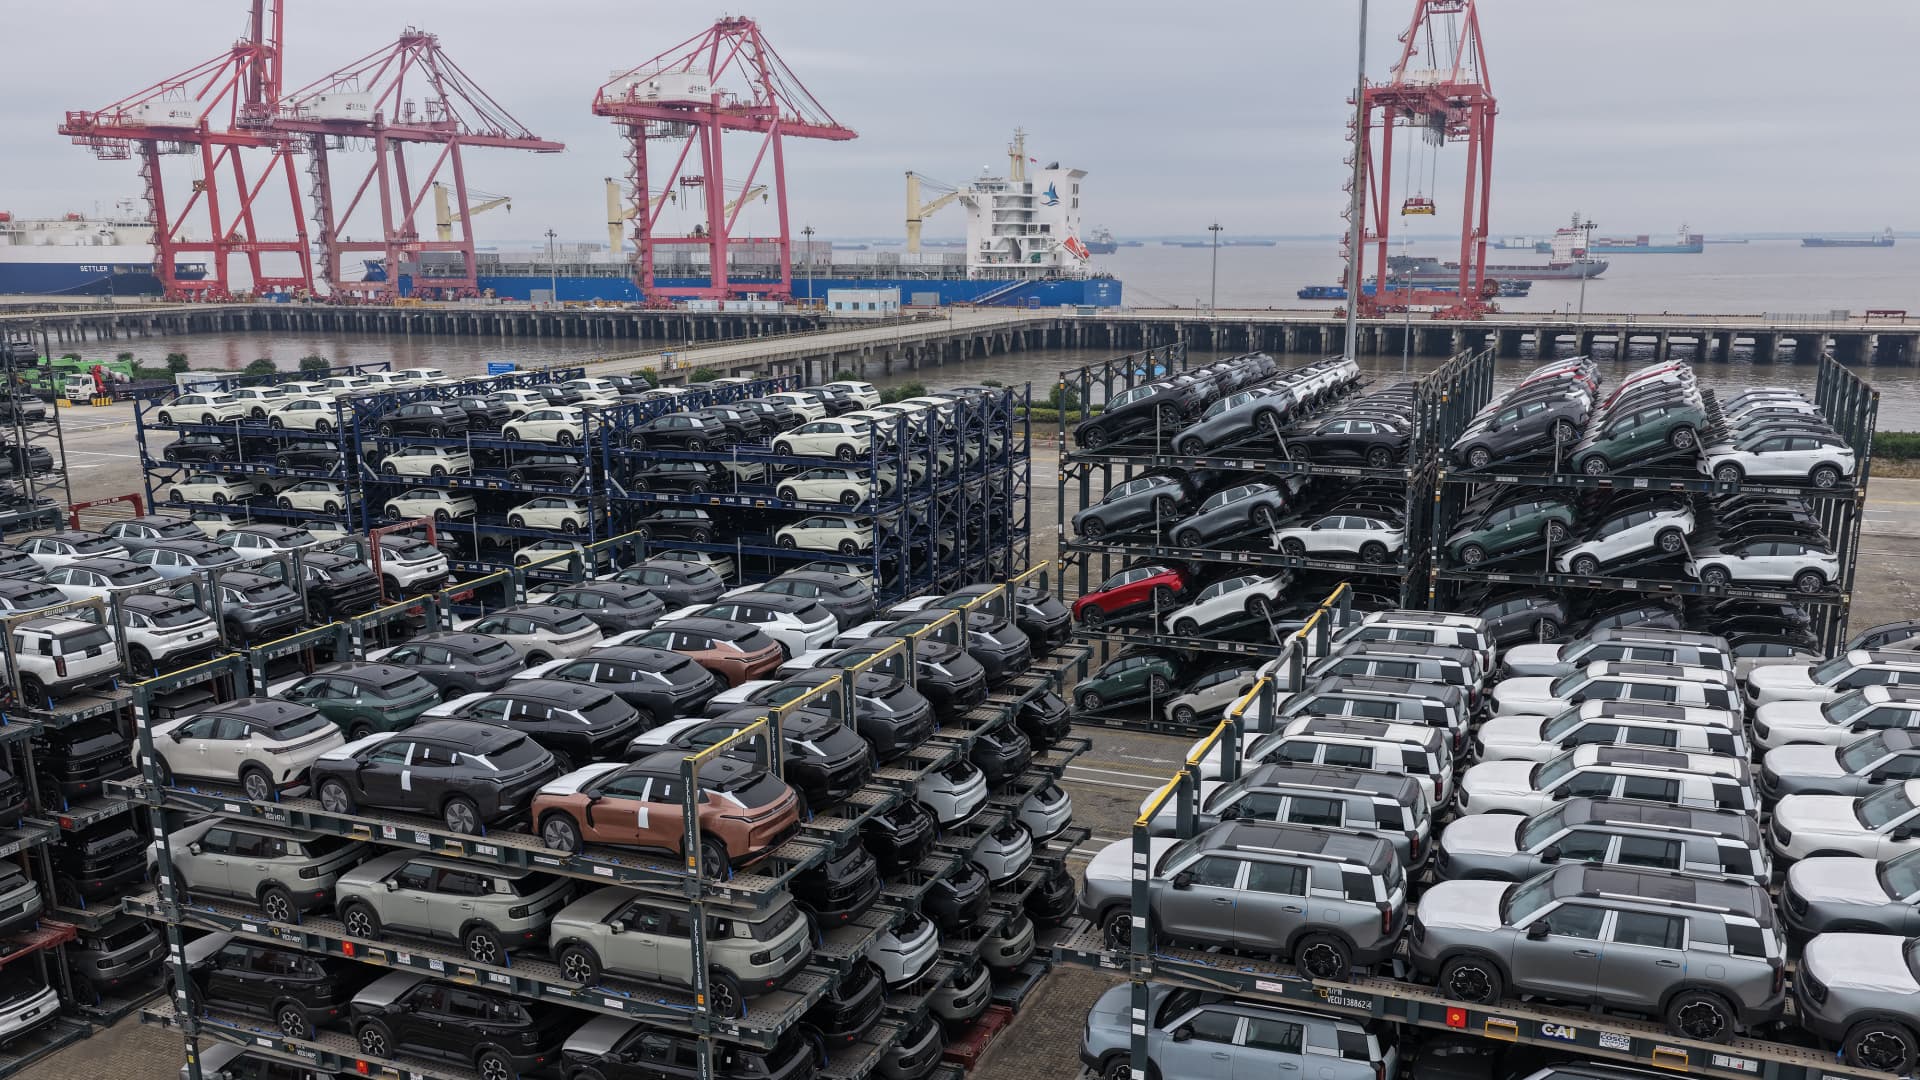
Beijing’s trade performance defied expectations in September, with both exports and imports registering significant year-over-year growth. This surge, particularly in China’s Exports, indicates a resilient external sector despite ongoing domestic economic concerns, driving global trade dynamics and presenting complex scenarios for asset valuations.
💰 Financial Strategy & Market Insights
- Robust External Demand. China’s export growth, its fastest since February, indicates strong global demand for Chinese goods, particularly high-tech components for AI and vehicles.
- Strategic Trade Surpluses. A record monthly trade surplus signals a continued accumulation of foreign exchange reserves, potentially influencing yuan strength and capital flows.
- Commodity Import Shifts. Despite an overall import surge, declining crude oil and rare earth volumes highlight strategic stockpiling or shifts in industrial consumption patterns.
China’s economy exhibited surprising strength in September, as exports jumped 36.3% year-on-year, marking their fastest pace since February. Imports also saw a robust increase of 31%, accelerating from August’s 28.2% and achieving their quickest growth since June. Both figures significantly outpaced consensus estimates from a Reuters poll, which projected 25.5% for exports and 24.5% for imports.
A key driver for this expansion was the surge in exports to the United States, which grew by nearly 39.6% in September, contributing to the largest monthly trade surplus since January 2025, according to customs data via Wind Information. This momentum is partly attributed to stabilizing U.S.-China trade tensions and burgeoning global demand for AI-related infrastructure. For instance, integrated circuit board exports globally soared by 136% in value, even as unit volume only rose by 1%, suggesting significant price increases or shifts to higher-value components. The broader automotive sector also saw strong performance, with overall car exports increasing by 56.3% in volume and 62% in value. However, the trade picture wasn’t uniformly positive across all sectors, revealing nuanced shifts in demand and supply chains.
- The volume of crude oil imports declined for the sixth consecutive month, despite a rise in value, reflecting potential shifts in energy consumption or inventory management.
- Rare earths and fertilizer exports saw a drop in volume over the first three quarters, while fertilizer imports surged, possibly due to domestic agricultural needs or strategic resource management.
- The European Union recently secured an agreement from China to halve hybrid-powered car exports to the bloc, indicating potential future shifts in trade balances for specific categories.
The record monthly trade surplus of $133.5 billion underscores the resilience of China’s external sector, even amidst concerns about sluggish domestic demand. This continued strength is a crucial factor for global market analysis and the stability of the financial sector performance, as noted by Hao Zhou, chief economist at Guotai Junan International Holdings. The recent plans by the U.S. and China to roll back tariffs on $30 billion worth of goods and extend a broader trade truce further stabilize the trading environment, supporting investment flows and mitigating geopolitical risk.
The Intricacies of Risk vs. Reward in Chinese Trade
The recent trade data presents a dual narrative of opportunity and caution for investors navigating global markets.
- Upside Potential:
- Strong export performance supports corporate earnings for China-based manufacturers, especially in tech and automotive.
- A robust trade surplus can bolster the yuan, making Chinese assets more attractive and potentially drawing foreign direct investment.
- Stabilizing U.S.-China trade relations could reduce policy uncertainty, encouraging cross-border investment and trade.
- Downside Risks:
- Dependence on external demand makes China vulnerable to global economic slowdowns or shifts in consumer spending.
- Concerns about sluggish domestic demand could cap growth in imports of certain goods, reflecting underlying weaknesses.
- Geopolitical tensions, despite recent stabilization, remain a long-term risk, potentially leading to renewed trade barriers or supply chain disruptions.
Understanding Capital Shifts: In financial markets, ‘capital shifts’ refer to the reallocation of investment funds across different asset classes, geographies, or sectors in response to changing economic conditions, interest rates, or geopolitical events. China’s surging trade surplus, for example, can attract capital inflows, influencing currency strength and domestic asset valuations.
Key Trade Metrics: September 2026 vs. Estimates
| Metric | September 2026 (YoY Growth) | Reuters Poll Estimate |
|---|---|---|
| Exports Growth | 36.3% | 25.5% |
| Imports Growth | 31.0% | 24.5% |
| Trade Surplus (USD) | $133.5 Billion | N/A |
| Exports to U.S. Growth | 39.6% | N/A |
| Integrated Circuit Exports (Value) | 136.0% | N/A |
| Overall Car Exports (Value) | 62.0% | N/A |
China’s Trade Dynamics: Market Liquidity Analysis
The impressive surge in China’s Exports directly impacts market liquidity, both domestically and internationally. A substantial trade surplus implies significant foreign currency inflows into China, which can increase the domestic money supply if not sterilized by the central bank. This expanded liquidity can lower borrowing costs, fuel domestic investment, and potentially inflate asset prices within China. Globally, China’s robust demand for raw materials and components, even with some volume declines in specific commodities, maintains a baseline level of liquidity in commodity markets. Investors should monitor how the People’s Bank of China manages these inflows, as its actions will dictate the extent to which this liquidity translates into tangible economic impact or inflationary pressures.
Global Capital Shifts: Investment Trends Impact
The surprising strength of China’s trade figures signals notable shifts in global capital flows and investment trends. The country’s role as a manufacturing powerhouse for AI-related components and electric vehicles positions it at the forefront of technological supply chains, attracting strategic investments. Furthermore, improving U.S.-China trade relations, even if fragile, encourage long-term capital commitments from multinational corporations looking to re-engage with the Chinese market. Conversely, the decline in certain commodity imports might indicate a re-evaluation of dependencies or a push towards domestic sourcing, potentially redirecting capital that once flowed to raw material-exporting nations. Investors seeking educational financial insights will observe these patterns closely for signals of emerging market opportunities or rebalancing efforts in wider global market trends.
The Ripple Effect of China’s Exports on 2026 Markets
China’s exceptional September trade data provides a crucial barometer for the health of global demand and China’s strategic position in the world economy. The robust performance in high-tech and automotive sectors highlights key areas of economic resilience and innovation, contrasting with nuanced shifts in commodity imports and domestic consumption. This mixed picture requires investors to maintain a discerning eye on market fundamentals and policy responses.
- The strength of export-oriented industries within China is likely to continue, benefiting related equity sectors.
- The record trade surplus could further stabilize the yuan, potentially making Chinese bonds and equities more attractive to foreign investors.
- Ongoing trade dialogues and agreements, such as those with the U.S. and EU, will remain pivotal in shaping future trade patterns and investment climates, influencing broader economic shifts.
How will global supply chains and capital allocations adapt to China’s evolving trade footprint in the coming year?
📊 StockXpo Analyst’s View
Market Impact: The strong September trade data, particularly China’s Exports, provides a significant tailwind for global growth sentiment, counteracting some prevalent fears of a broader economic slowdown. This influx of capital via trade surplus should support Asian market liquidity, potentially leading to stronger performance in sectors reliant on global demand. However, the divergence between export strength and domestic demand weakness presents a complex outlook for internal consumption-driven assets.
Sector To Watch: Given the surge in integrated circuit and automotive exports, the technology and electric vehicle (EV) manufacturing sectors in China are poised for continued investor interest. Companies involved in AI infrastructure components and EV battery technology, both directly and indirectly through their supply chains, should be closely monitored for potential upside. Conversely, traditional raw material suppliers might experience tempered demand if China continues to optimize its import volumes.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE FINANCE
Singapore Haven: Stability Yields Opportunity Amid Global Volatility
Published: Tuesday, October 13, 2026 · 12:19 AM
Inflation Peak for 2026: Sticky Prices to Challenge Asset Valuations
Published: Monday, October 12, 2026 · 11:45 AM