
Published: Wednesday, October 14, 2026 · 2:45 AM | Updated: Wednesday, October 14, 2026 · 2:45 AM
📊 15 views


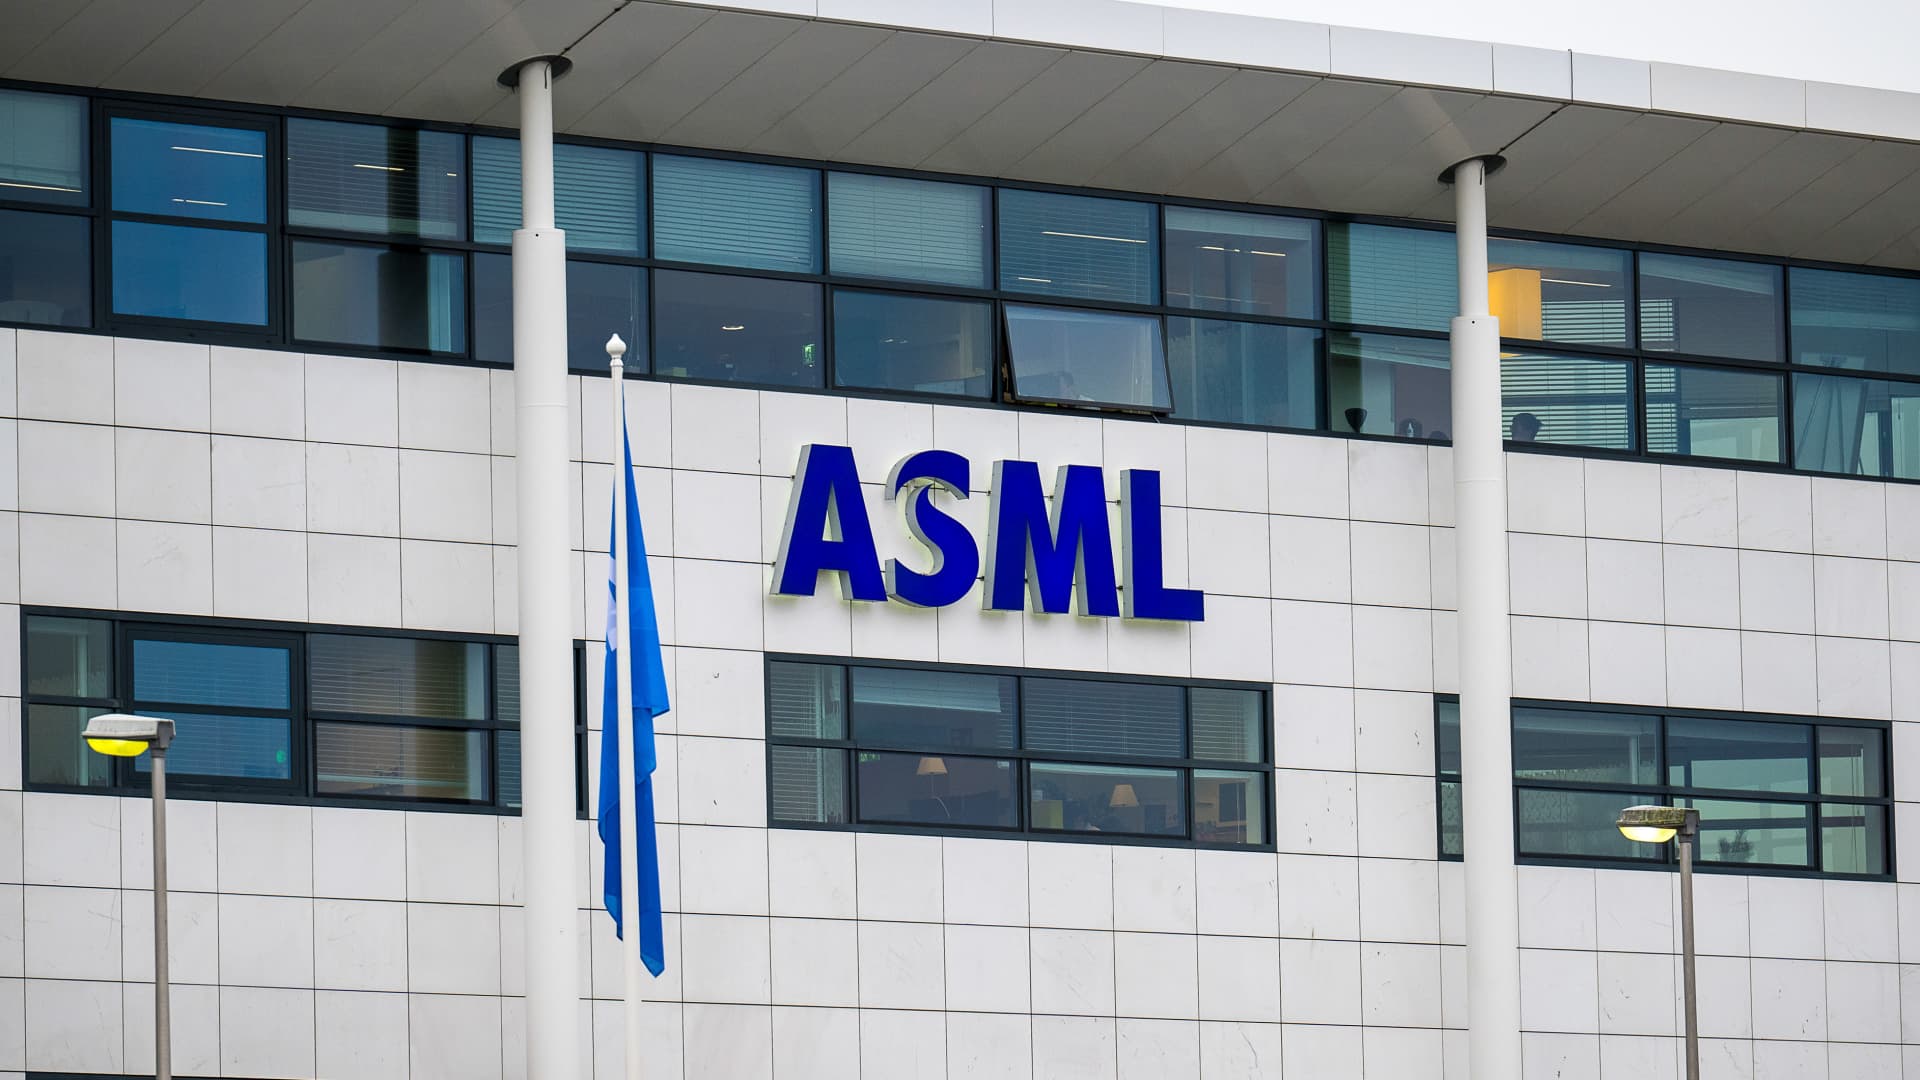
ASML Holding NV, the sole producer of extreme ultraviolet (EUV) lithography machines, has reported third-quarter profits significantly exceeding expectations, fueled by surging interest in orders extending through 2030. This robust demand, primarily driven by long-term AI investments, reinforces ASML’s pivotal role in the global semiconductor landscape and its potential as a compelling long-term alpha generator.
💎 Strategic Investment & Portfolio Insights
- Extended Demand Horizon. ASML’s ability to secure customer interest for orders stretching to 2030 underscores the persistent, AI-driven need for advanced chipmaking capabilities, providing exceptional revenue visibility.
- Unrivaled Market Position. As the exclusive supplier of EUV technology, ASML possesses an unparalleled competitive moat, making it indispensable for leading chipmakers like TSMC and Samsung in their pursuit of next-generation semiconductors.
- Capacity Expansion & Innovation. The company’s proactive efforts to investigate capacity increases beyond its initial 30% forecast for 2028, coupled with the adoption of High NA EUV by key clients, signal sustained technological leadership and growth potential.
The Dutch chip equipment giant, ASML, has delivered a powerful message to investors: demand for its cutting-edge lithography machines is not just strong, but extending far into the next decade. CEO Christophe Fouquet highlighted significant customer interest in placing orders for both 2029 and 2030, a clear indicator of sustained industry growth propelled by artificial intelligence. This long-term visibility is a rare commodity in the often-cyclical semiconductor sector, offering considerable comfort to those assessing ASML’s intrinsic value. The company’s unique position as the world’s only producer of extreme ultraviolet (EUV) lithography machines – essential for fabricating the most advanced semiconductors – underpins this exceptional demand. Leading foundries, including TSMC and Samsung, are not only reliant on ASML’s existing technology but have also committed to adopting its next-generation High NA EUV machines, which analysts view as critical for future expansion. This reinforces the firm’s technological moat and its central role in enabling the global push for AI and other high-performance computing applications.
Despite impressive growth, market insights from ASML suggest that current supply plans for 2027 and 2028 will not fully satisfy customer demand. This has prompted the company to explore ways to further boost capacity beyond its previously projected 30% increase for 2028, signaling both the immense pressure from client needs and ASML’s commitment to capitalizing on this robust market. The firm’s recent financial results further validated its strong trajectory, with Q3 net profit of 4.96 billion euros significantly surpassing consensus estimates of 4.1 billion euros. Moreover, ASML narrowed its full-year revenue forecast upwards to between 44 billion and 45 billion euros, and provided an optimistic Q4 net sales outlook, with the upper end exceeding LSEG expectations.
- ASML’s unprecedented demand visibility through 2030, primarily fueled by massive AI-related investments, provides a rare long-term growth catalyst in the semiconductor industry.
- The company’s exclusive EUV technology and the rapid adoption of its High NA EUV tools by major chipmakers cement its indispensable role in advanced chip manufacturing.
- Despite challenges, ASML expects China sales to constitute 20% of its total business, maintaining its previous forecast amidst export restrictions and China’s nascent DUV domestic production efforts.
Concerns about China’s burgeoning domestic DUV chipmaking capabilities, detailed in reports from Forbes business news, continue to be monitored. While China seeks to bolster its indigenous supply chain, the advanced nature and complexity of ASML’s EUV technology, which remains restricted from sale to China, present substantial barriers to entry for competitors. ASML’s shares have rallied 56% this year, reflecting investor confidence in its growth prospects and strategic importance in the evolving technology landscape.
Portfolio Positioning Effect
Sustained long-term demand for ASML’s cutting-edge equipment → Reinforced revenue visibility and earnings stability for ASML → Enhanced justification for a strategic overweight position in diversified portfolios seeking exposure to foundational technology infrastructure and AI growth drivers → Potential for capital appreciation and alpha generation through a high-quality, wide-moat asset.
“ASML’s extended order book through 2030 is more than just good news; it’s a strategic beacon for discerning investors. This rare level of long-term demand visibility, driven by the relentless march of AI, cements ASML as a core holding in any technology-focused portfolio aiming for foundational growth rather than ephemeral trends. It’s an infrastructure play on the digital future.”
ASML’s Financial Strength: Key Performance Metrics
ASML’s recent financial performance highlights its robust operational strength and market leadership:
| Metric | Reported Value | LSEG Consensus | Significance |
|---|---|---|---|
| Q3 Net Sales | 11.66 billion euros | 11.72 billion euros | Slightly below estimates, but indicative of strong revenue base. |
| Q3 Net Profit | 4.96 billion euros | 4.1 billion euros | Significantly beat expectations, demonstrating strong profitability. |
| Full-Year 2026 Net Sales Forecast | 44 billion – 45 billion euros | Previous: 43 billion – 45 billion euros | Narrowed and raised lower end, signaling increased confidence. |
| Q4 Net Sales Forecast | 14.2 billion – 15.2 billion euros | 14.2 billion euros | Upper end exceeds consensus, projecting strong quarter-end performance. |
ASML Risk-Reward Matrix: Navigating Dominance and Geopolitics
Investing in ASML presents a distinct risk-reward profile shaped by its unparalleled market dominance and external geopolitical factors. On the reward side, its virtual monopoly in EUV technology provides a deep economic moat, ensuring high barriers to entry and consistent demand from a concentrated customer base of leading-edge chipmakers. The multi-year order visibility, driven by secular trends in AI, IoT, and high-performance computing, offers exceptional revenue predictability and long-term growth potential, solidifying its position as a high-quality growth asset. The company’s continuous innovation, particularly with High NA EUV, maintains its technological leadership, fostering continued pricing power and margin expansion.
However, risks are not absent. ASML’s significant exposure to geopolitical tensions, particularly regarding export controls to China, introduces a degree of regulatory uncertainty that could impact sales in a key market. While China currently accounts for 20% of sales, tightening restrictions or retaliatory measures could present headwinds. Furthermore, the semiconductor industry, despite its current boom, remains cyclical, and any global economic downturn or a significant slowdown in AI investments could temper demand. Execution risk also exists in scaling up capacity to meet aggressive demand forecasts, and reliance on a complex global supply chain makes it susceptible to disruptions. Investors must weigh ASML’s robust competitive advantages and long-term secular tailwinds against these specific, albeit manageable, risk factors for proper portfolio strategy.
ASML Competitive Benchmarking: A Class of Its Own
When evaluating ASML against its peers, it quickly becomes evident that the company operates in a category largely of its own, particularly concerning advanced lithography. Traditional semiconductor equipment manufacturers like Applied Materials (AMAT) and Lam Research (LRCX) offer complementary tools for deposition, etching, and other fabrication steps, but none possess the critical, bottleneck technology that ASML does with EUV. This differentiation affords ASML unique pricing power and an almost captive market for its most advanced systems. While competitors might compete on broader equipment offerings or specific process steps, ASML’s EUV dominance ensures it is an indispensable partner for any foundry aiming to produce chips at the 7nm node and below. This translates into superior margins and a more predictable revenue stream compared to companies operating in more fragmented or competitive segments of the semiconductor equipment market. Its investment in R&D for next-generation High NA EUV further widens this competitive gap, maintaining its lead for years to come, as highlighted by a recent Bloomberg markets report.
ASML’s Unprecedented Visibility: A Pillar for Tech Portfolios
ASML’s remarkable earnings report, characterized by strong profit beats and a multi-year order pipeline extending to 2030, firmly establishes its critical role in the accelerating AI revolution. The company’s unique technological edge and its proactive stance on capacity expansion underscore its enduring growth potential, making it a compelling candidate for long-term capital appreciation within diversified technology portfolios.
- The extended demand horizon to 2030 provides unparalleled revenue visibility, mitigating cyclical concerns.
- ASML’s monopoly in EUV and commitment to High NA EUV ensures its indispensable role in advanced chip manufacturing.
- Strategic investors should view ASML as a foundational asset capturing the core infrastructure growth of AI and advanced computing.
Can ASML effectively navigate geopolitical headwinds and scale its formidable technology to meet the insatiable global appetite for advanced semiconductors?
📊 StockXpo Analyst’s View
Market Impact: This news from ASML will likely bolster investor confidence across the entire semiconductor supply chain, signaling robust, long-term demand for advanced chip technology. It should translate into positive sentiment for related equipment providers and foundries, potentially increasing market liquidity and encouraging further capital allocation into the tech sector, especially for companies enabling AI infrastructure.
Sector To Watch: The Semiconductor Equipment & Materials sector (SMH, SOXX) will remain paramount. Beyond ASML, look for strong performance from companies that supply components or services essential to ASML’s manufacturing process, as well as the major chip foundries (like TSMC) that are direct beneficiaries of ASML’s technological advancements, solidifying the long-term growth narrative of the AI ecosystem.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE INVESTMENT NEWS
Goldman Sachs Rating Upgrade: Alpha Potential After Strong Q3 Performance
Published: Tuesday, October 13, 2026 · 3:58 PM
Delta Air Lines Forecast: Warning Signals on 2026 Outlook Amid Fuel Volatility
Published: Friday, October 9, 2026 · 8:54 AM

