
Published: Tuesday, October 6, 2026 · 6:03 AM | Updated: Tuesday, October 6, 2026 · 6:03 AM
📊 10 views


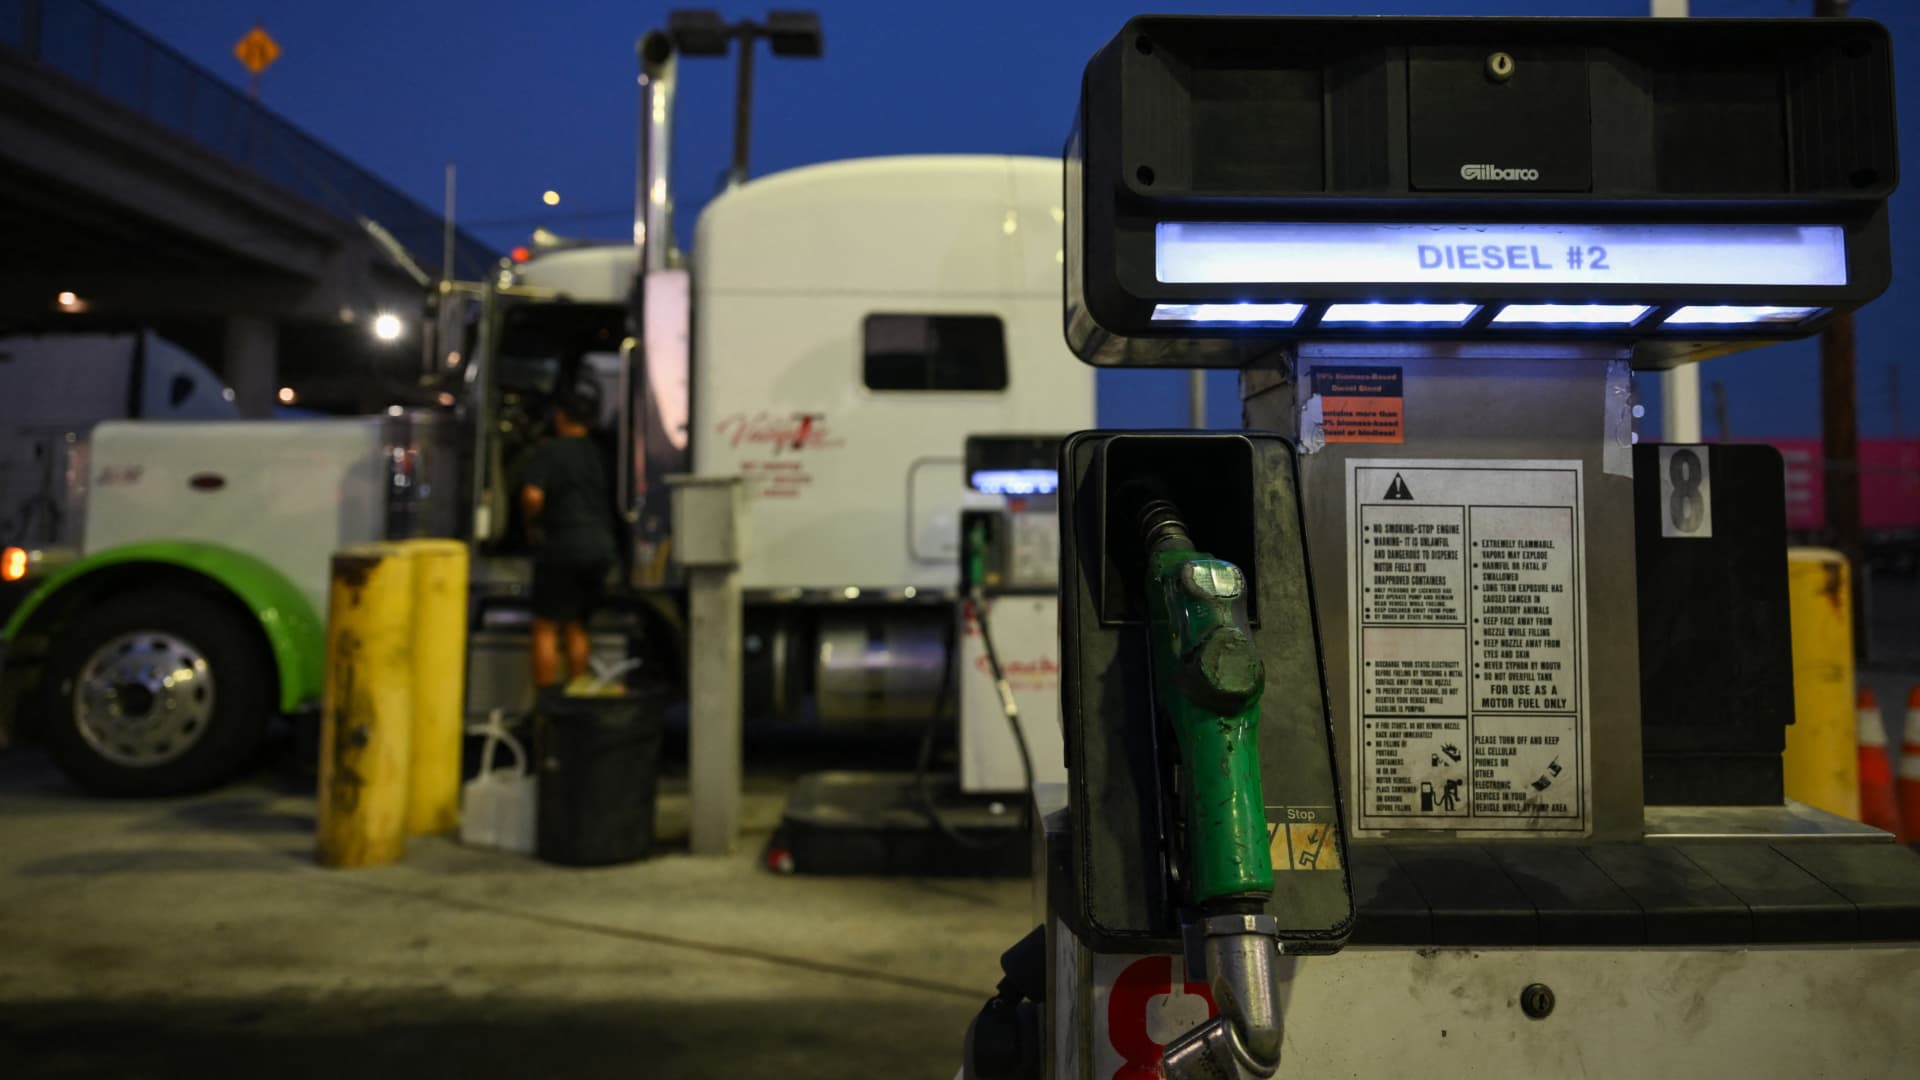
Goldman Sachs projects that elevated diesel prices will persist through 2027, driven by a confluence of persistent global refinery constraints and a robust recovery in consumption. This outlook suggests a prolonged period of inflationary pressure on critical economic sectors reliant on refined products.
💰 Financial Strategy & Market Insights
- Sustained High Prices. Goldman Sachs anticipates diesel prices to remain high through 2027, necessitating demand destruction to balance the market against constrained refining capacity.
- Elevated Crack Spreads. Global diesel and jet-fuel crack spreads are forecast to average over $40 per barrel in 2027, more than double historical norms, even with Brent crude stabilizing around $80 per barrel.
- Inventory Depletion & Recovery Demand. Critical refined product inventories are expected to fall to their lowest days-of-supply since 2015, exacerbating supply shortages as global demand rebuilds, turning restocking into a significant future demand driver.
Global energy markets are grappling with a structural deficit in refining capacity, a core driver behind Goldman Sachs’ latest forecast for persistently high diesel prices. Nikhil Bhandari, Goldman’s co-head of Asia-Pacific natural resources research, highlighted the necessity of sustained high product prices to induce ongoing demand destruction, preventing recovering consumption from overwhelming an already strained global refining system. This dynamic is set to push diesel and jet-fuel crack spreads – the profit margin from refining crude into products – to average above $40 per barrel in 2027, substantially higher than the typical $20.
Despite expectations for Brent crude to stabilize around $80 per barrel, the fundamental issue lies not in crude availability but in refining bottlenecks. Industry experts, including Baden Moore of CLSA, concur that underlying oil-product demand remains robust, with market balancing achieved primarily through inventory drawdowns and consumption curtailment rather than permanent demand destruction. The challenge of replenishing global inventories while simultaneously meeting current demand could extend for two years, exerting continuous upward pressure on refined product valuations.
Refinery networks worldwide are under severe pressure, with 2026 projected to mark another year of negative refining capacity growth. Goldman Sachs estimates that refining capacity outside China will contract by approximately 300,000 barrels per day. The situation is further complicated by roughly 2 million barrels per day of Middle Eastern refining capacity remaining offline and damage to Russian facilities impacting diesel supply. U.S. refineries, which have been operating at elevated rates, face impending deferred maintenance, which will temporarily reduce output.
Recent efforts, such as the G7 countries’ agreement to release 100 million barrels of crude and refined products, including a substantial diesel release, have offered only temporary relief. These emergency releases primarily address liquidity issues rather than the underlying stock problem, meaning inventories are consumed without being rebuilt, according to CLSA’s Moore. Bernard Aw, chief economist for Asia-Pacific at Coface, echoed this sentiment, emphasizing the temporary nature of such interventions on global energy markets, rather than providing structural improvements.
* **Chronic Capacity Shortages**: The structural decline in refining capacity, particularly outside China, creates a bottleneck that even stable crude prices cannot alleviate, keeping refined product prices elevated.
* **Inventory Depletion**: Years of underinvestment and rapid post-pandemic demand recovery have drawn down global product inventories to critical levels, necessitating a prolonged restocking period that will compete with immediate consumption.
* **Geopolitical Impact**: Ongoing geopolitical tensions and unforeseen disruptions, such as attacks on Russian facilities or issues in the Strait of Hormuz, continue to add layers of uncertainty and supply risk to the market.
Assessing the Investment Landscape Amidst High Diesel Prices
The prolonged period of high diesel prices presents a complex risk-reward profile for investors and businesses. Understanding these dynamics is crucial for strategic capital allocation.
- Upside Potential:
- Enhanced profitability for integrated oil and gas companies with refining assets, particularly those with efficient operations or strategic locations.
- Increased investment in refining technology upgrades and new, more efficient capacity, potentially benefiting engineering and construction firms in the energy sector.
- Accelerated adoption and investment in alternative fuels and electric vehicle infrastructure for heavy transport, creating new growth opportunities in related industries.
- Downside Risks:
- Significant inflationary pressures across global supply chains, increasing operating costs for transportation, logistics, agriculture, and manufacturing sectors.
- Potential for demand destruction in price-sensitive sectors, leading to reduced economic activity and lower corporate earnings, as seen in broader financial sector stability.
- Increased risk of government intervention, such as price caps or export bans, which could introduce regulatory uncertainty and impact market efficiency.
- Exacerbated geopolitical tensions if supply disruptions continue or worsen, leading to higher volatility in commodity markets and affecting asset valuation.
Understanding Crack Spreads: In the energy market, a ‘crack spread’ represents the profit margin a refinery can achieve by ‘cracking’ a barrel of crude oil into refined products like diesel, gasoline, and jet fuel. A high crack spread, like the $40 per barrel forecast by Goldman Sachs, indicates strong demand for refined products relative to crude oil, signaling robust profitability for refiners despite potentially stable crude prices.
Key Metrics in the Diesel Market Outlook
| Metric | Value/Outlook | Source/Comment |
|---|---|---|
| 2027 Diesel/Jet-Fuel Crack Spread Forecast | Above $40/barrel | Goldman Sachs (More than double typical levels) |
| Typical Crack Spread Level | Around $20/barrel | Historical Average |
| Brent Crude Price Forecast | Approximately $80/barrel | Goldman Sachs (Stabilized) |
| Non-China Refining Capacity Contraction (2026) | ~300,000 barrels per day | Goldman Sachs |
| Middle Eastern Refining Capacity Offline | ~2 million barrels per day | Nikhil Bhandari, Goldman Sachs |
| G7 Emergency Release (Total) | 100 million barrels (over 4 months) | Group of Seven Countries |
Diesel Market Sentiment Tracker: Navigating Supply Volatility
Market sentiment surrounding global energy markets remains cautious, marked by a clear divergence between crude oil stability and refined product tightness. Despite crude prices showing signs of normalization, the outlook for diesel and other distillates is decidedly bullish due to fundamental supply-side challenges. This sentiment is reinforced by the consensus among analysts that emergency strategic releases offer only short-term relief, failing to address the deeper structural issues in refining capacity and inventory deficits. The market is increasingly pricing in a ‘new normal’ where higher crack spreads and sustained price premiums for refined products become the norm rather than an anomaly. Investor focus has shifted from upstream crude production to midstream and downstream refining capabilities, highlighting the critical pinch point in the energy value chain. Concerns about economic inflation, driven by elevated transport costs, are also influencing broader market sentiment and risk-off behavior.
Global Refinery Capacity Analysis: A Decisive Pinch Point
The global refinery landscape is undergoing a significant transformation, characterized by closures, underinvestment, and deferred maintenance, creating a critical choke point for refined product supply. The anticipated contraction in non-China refining capacity in 2026, coupled with substantial offline capacity in the Middle East and Russia, illustrates a systemic problem. This structural deficit means that even if crude oil supply is abundant, the ability to convert it into usable fuels like diesel is severely limited. Analysts from firms like CLSA and Coface, whose insights are often echoed in analyst reports, emphasize that this is not a transient issue but a multi-year challenge requiring substantial capital investment and strategic planning. The reliance on existing, often aging, infrastructure running at peak utilization rates further exposes the market to operational risks, scheduled shutdowns for maintenance, and unexpected outages, all contributing to heightened supply volatility and sustained high prices.
What Sustained Diesel Prices Mean for Global Commerce
Goldman Sachs’ forecast for prolonged high diesel prices through 2027 indicates a challenging period ahead for the global economy, necessitating proactive strategies from businesses and policymakers. The persistent imbalance between recovering demand and constrained refining capacity signals enduring cost pressures for sectors from logistics to manufacturing.
- Businesses heavily reliant on diesel, such as trucking, shipping, and agriculture, face sustained higher operating costs, impacting profitability and consumer prices.
- Governments may consider various interventions, but temporary measures like strategic releases are unlikely to offer long-term structural solutions to supply deficits.
- The outlook underscores the need for accelerated investment in energy efficiency, alternative fuels, and potentially new, more flexible refining capacity to mitigate future shocks.
How will global supply chains adapt to this new era of elevated diesel costs, and what impact will it have on inflationary trends and economic growth projections?
📊 StockXpo Analyst’s View
Market Impact: The sustained elevation of diesel prices will act as a significant inflationary catalyst, permeating across manufacturing, agriculture, and especially the transport and logistics sectors. This will pressure corporate margins and could dampen consumer spending, potentially leading to a repricing of industrial equities and a cautious stance on growth-sensitive assets. Market liquidity might tighten as businesses prioritize essential operational costs.
Sector To Watch: Investors should keenly observe the logistics, heavy industrial, and agricultural sectors, which face direct cost headwinds. Conversely, integrated oil companies with significant refining capacity could see robust earnings, while developers of alternative fuels and energy-efficient technologies may experience increased investment and accelerated adoption. For more educational financial insights, stay tuned to our analyses.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE FINANCE
Brazilian Stocks Jump: Political Shift Ignites Market Volatility
Published: Monday, October 5, 2026 · 1:50 PM
Sports Betting Volatility: Gen Z’s Risky Financial Shift
Published: Sunday, October 4, 2026 · 10:11 AM


