
Published: Tuesday, October 6, 2026 · 1:56 AM | Updated: Tuesday, October 6, 2026 · 1:56 AM
📊 13 views


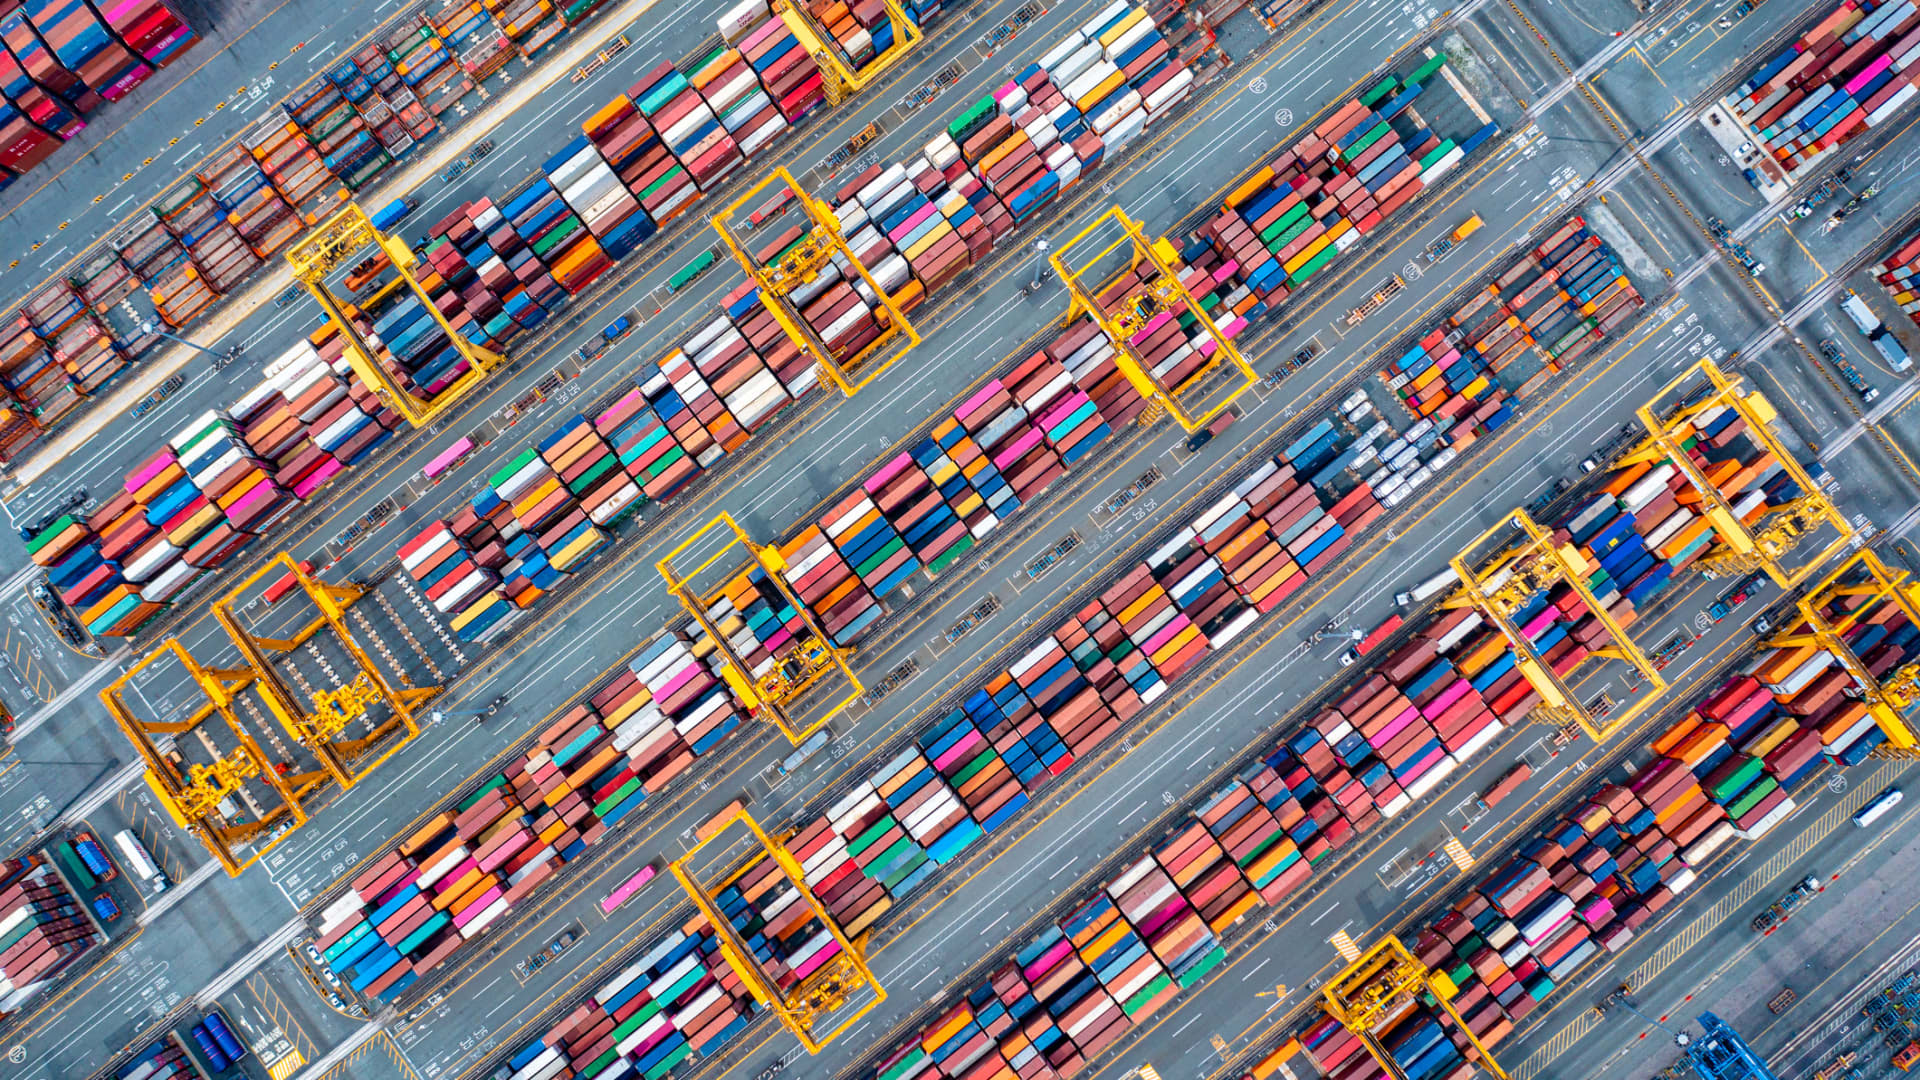
The World Bank has issued a stark warning regarding significant AI concentration risks, even as it boosted the growth forecast for the East Asia and Pacific (EAP) region to 4.5% for the current year. This dual outlook highlights a precarious balance: robust economic expansion fueled by a surging AI sector, juxtaposed with the inherent vulnerabilities of over-reliance on a rapidly evolving, yet largely untested, technological boom. The global economy stands at a critical juncture, navigating the transformative potential of AI against the backdrop of potential financial instability.
📊 Macro-Economic Strategic Insights
- EAP Growth Revised Upwards. The World Bank now projects East Asia and Pacific economies to expand by 4.5% in 2026, a 0.3 percentage point increase from previous forecasts, driven largely by AI-related exports.
- AI Export Dependence Deepens. More than half of the region’s export growth, and over 70% in key economies like Malaysia and Vietnam, is attributed to AI-related goods, indicating a profound reliance on this single sector.
- Bubble-Like Spending Concerns. Global AI capital expenditure now mirrors the 2000 dot-com bubble’s peak in IT investment relative to U.S. GDP, prompting concerns about a potential spending reversal and its systemic impact.
The World Bank’s latest report on the East Asia and Pacific region paints a picture of resilient economic growth, largely propelled by a surging demand for artificial intelligence-related exports. The EAP economy, encompassing 23 diverse nations including China, Vietnam, and Indonesia, is now projected to grow by 4.5% this year, an upward revision of 0.3 percentage points from the April forecast. This robust expansion is a testament to the region’s crucial role in the global AI supply chain, with nations like Vietnam receiving substantial upgrades to their growth outlook, now at 7.4%. However, this positive trajectory is shadowed by considerable AI concentration risks.
The bank’s analysis reveals a concerning dependency: trade growth, excluding AI-related goods, has been ‘weak or negative.’ AI products alone constituted over half of the export growth across most regional economies, exceeding 70% in Malaysia, the Philippines, Thailand, and Vietnam. This concentration is starkly visible in figures showing China, Indonesia, Malaysia, the Philippines, Thailand, and Vietnam collectively shipped $1.4 trillion worth of AI-related goods in the 12 months leading up to April. South Korea, for instance, saw its September exports surge by 83.5% to a record $120.9 billion, with semiconductors accounting for half of that volume. The dominance is further emphasized by Samsung and SK Hynix, two chipmakers, representing 43% of the benchmark Kospi index’s value as of April end.
The rapid escalation of AI-related capital expenditure globally raises significant red flags for macro-stability.
- This unprecedented spending cycle has already reached about 6% of U.S. GDP, a level comparable to the peak of information-technology investment during the 2000 dot-com era, and continues to accelerate at an alarming rate.
- Concerns over potential market overheating are echoed by the Bank for International Settlements (BIS), which noted in its annual economic report that the AI boom’s scale and pace bear resemblance to historical ‘manias’ like the 1990s dot-com frenzy, suggesting an investment bubble.
Further exacerbating these concerns is the opacity of the financing underpinning this boom. A significant portion of the planned AI capital expenditure — $800 billion out of a projected $2.9 trillion for 2025-2028 — is expected to come from private credit markets. Lending for AI-related projects within private credit portfolios surged from an 18% average over the prior five years to 34% in 2025. These markets are inherently ‘less visible, and have not been tested by a severe downturn,’ according to the World Bank, and have already experienced markdowns, outflows, and defaults this year, as reported by financial news outlets like Reuters’ analysis on emerging market stability. For broader educational insights into market dynamics, consult expert economic blogs. The potential for a sharp correction, where investment has ‘run ahead of realized demand,’ could severely impact the East Asia region due to its deep integration into the AI supply chain.
The Ripple Effect: Unpacking AI’s Economic Consequences
The global economic landscape faces several ripple effects stemming from the current AI boom dynamics:
- Excessive AI Investment → Increased Market Volatility → Potential Correction in Tech Valuations.
- Concentrated AI Exports → Heightened Regional Vulnerability → Economic Downturn if Global Demand Shifts.
- Opaque Private Credit Funding → Systemic Financial Risk → Credit Market Stress if Defaults Rise.
- Tightening Financial Conditions (e.g., Fed rate hikes) → Reduced Liquidity → Slower Investment in Growth Sectors.
- U.S. Growth Slowdown (1 percentage point) → Emerging Market Growth Cut (0.6 percentage point) → Impact on Global Trade and Investment.
‘The concept of ‘systemic risk’ in finance refers to the risk of collapse of an entire financial system or market, as opposed to the collapse of a single entity, resulting from the failure of a major interconnected component. In the context of the AI boom, the heavy reliance on private credit, coupled with the concentrated nature of AI-related exports and investment, introduces systemic vulnerabilities. A significant reversal in tech spending or a cascade of defaults within less transparent private credit markets could trigger a broader financial contagion, far beyond individual company failures.’
Key Economic Indicators: AI Sector and EAP Growth
| Metric | Value (2026 est.) | Significance |
|---|---|---|
| East Asia & Pacific Growth Forecast | 4.5% (up from 4.2%) | Indicates regional economic resilience, primarily driven by external demand for AI components. |
| Vietnam Growth Forecast Upgrade | 7.4% (up 1.1 percentage pts) | Highlights specific economies benefiting disproportionately from the AI supply chain boom. |
| AI-Related Export Share (select EAP) | 70%+ (Malaysia, Philippines, Thailand, Vietnam) | Reveals extreme concentration of export revenue in the AI sector, increasing risk. |
| Global AI Capex as % of U.S. GDP | ~6% | Comparable to dot-com bubble peak, signaling potential overinvestment relative to demand. |
These metrics underscore the dual nature of the AI boom: significant growth for key EAP economies, but also a growing dependency and potential for market instability if the sector faces a downturn.
Southeast Asia’s Regional Trends and Export Diversification Needs
The burgeoning AI sector has undoubtedly provided a significant uplift to Southeast Asian economies, particularly those deeply embedded in electronics and semiconductor manufacturing. Countries like Vietnam, Malaysia, and the Philippines are reaping the benefits of increased global demand for AI-related hardware. However, this hyper-specialization, while profitable in the short term, also exposes these nations to considerable risk. A global slowdown in tech spending or a shift in AI technology paradigms could disproportionately affect their export-driven growth models. Diversifying their manufacturing bases and cultivating domestic demand in non-tech sectors will be crucial for these economies to build sustainable macro-stability and resilience against future market shocks.
Policy Commentary on Safeguarding Financial Stability Amidst Tech Booms
Policymakers in the East Asia and Pacific region, as well as global financial regulators, face a delicate balancing act. On one hand, fostering innovation and embracing the economic benefits of AI is paramount for long-term growth. On the other, the lessons from past speculative bubbles, such as the dot-com era, highlight the need for robust financial oversight. Central banks must carefully monitor the expansion of private credit markets, particularly their exposure to the AI sector, which currently lacks transparency, a concern often highlighted by leading economic publications. Implementing stress tests for financial institutions with significant foreign-currency liabilities, especially in countries like Malaysia (29.2% of GDP) and the Philippines (20.7% of GDP), is critical. Proactive fiscal policies that encourage broader economic diversification, rather than over-reliance on a single industry, will be vital to mitigate the systemic risks associated with concentrated tech investment.
Navigating AI Concentration Risks: The Path to Sustainable Growth
The World Bank’s latest assessment reveals a complex narrative of impressive growth in East Asia and the Pacific, directly powered by the AI revolution, yet simultaneously shadowed by profound AI concentration risks. While the immediate economic benefits are undeniable, the long-term systemic stability of these economies hinges on their ability to manage potential tech spending reversals and address the opaque financing structures fueling the boom.
- The region’s heavy reliance on AI-related exports could lead to significant economic disruption if global demand for these products softens or shifts.
- Unregulated private credit markets pose a hidden threat, potentially amplifying financial instability in the event of an AI sector downturn.
- Policymakers must prioritize diversification and transparency to ensure that current growth is sustainable and does not lead to future systemic shocks.
How will the EAP economies balance the transformative potential of AI with the imperative of building resilient, diversified growth models for the coming decade?
📊 StockXpo Analyst’s View
Market Impact: The current environment suggests that while AI-related stocks in the EAP region could continue to see strong performance on the back of export demand, investors must exercise caution. The warning of ‘AI concentration risks’ from the World Bank signals potential volatility. A sudden cooling of global AI capital expenditure, akin to past tech bubbles, could trigger sharp corrections in highly specialized EAP markets. Liquidity remains abundant but rising rates could curb enthusiasm. For investors looking for insights into global market trends and strategic investment analysis, resources like StockXpo.com can provide valuable context.
Sector To Watch: The semiconductor and advanced manufacturing sectors are clearly central to the AI boom in EAP. However, their extreme dependency means they are also the most exposed to a downturn. While growth is robust now, smart investors should also monitor sectors that offer diversification, such as renewable energy infrastructure or domestic consumer staples, to hedge against potential overexposure to the AI supply chain. Furthermore, understanding economic policy shifts is crucial for navigating these markets effectively; comprehensive analysis of economic policy from sources like StockXpo.com/economy is essential.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE ECONOMY
Western Populations’ Shrinkage: A Looming Fiscal Warning by 2029
Published: Monday, October 5, 2026 · 3:15 AM
Labor Market Weakness: September Jobs Report Signals Economic Shift
Published: Friday, October 2, 2026 · 10:08 AM


