
Published: Friday, October 2, 2026 · 10:08 AM | Updated: Friday, October 2, 2026 · 10:08 AM
📊 12 views


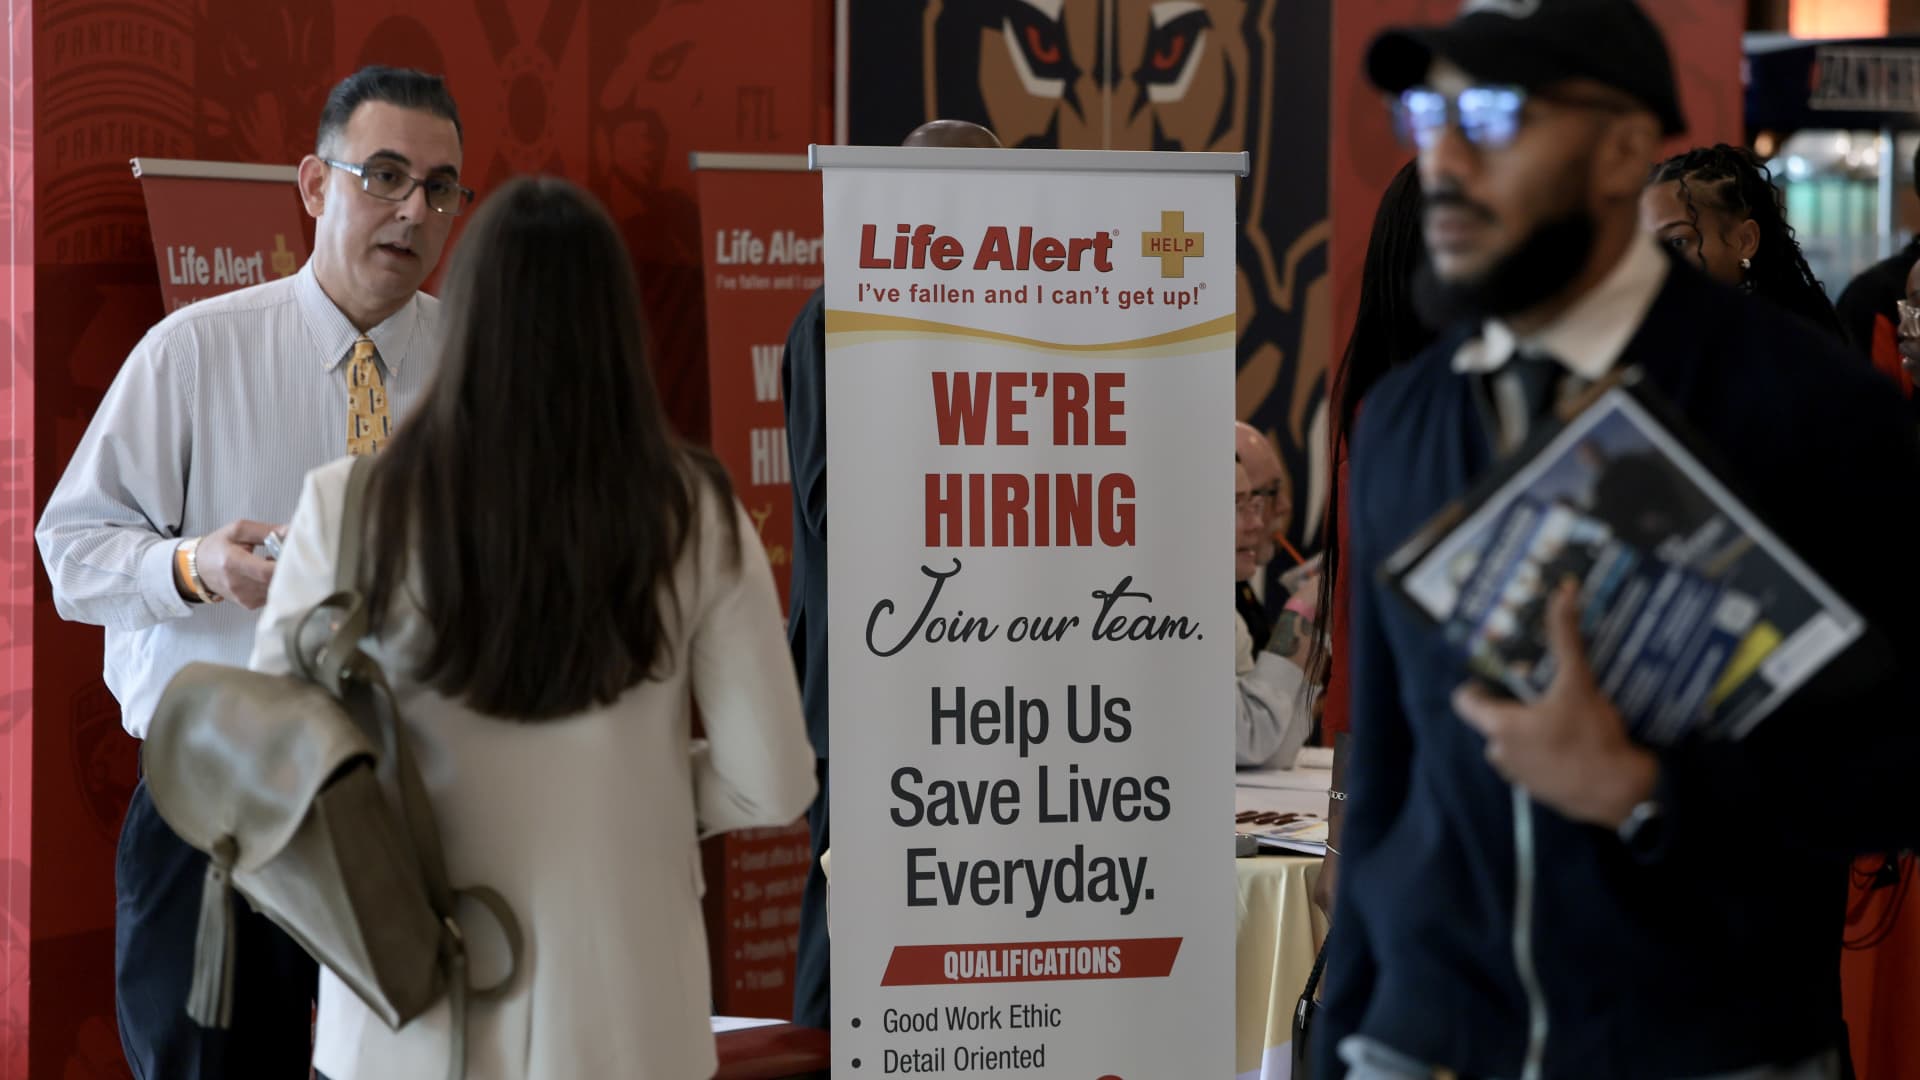
The U.S. labor market unexpectedly stumbled in September, with job creation falling significantly below expectations and the unemployment rate ticking up. This surprising soft patch suggests a cooling economic environment, potentially influencing global investment flows and central bank policy decisions worldwide.
📊 Macro-Economic Strategic Insights
- Unexpected Jobs Slowdown. Nonfarm payrolls rose only 29,000, significantly below the anticipated 84,000, signaling a pronounced deceleration in hiring activity across the U.S. economy.
- Fed Rate Hike Probability Shifts. The weaker-than-expected jobs data has sharply reduced the likelihood of an October interest rate hike by the Federal Reserve, with market-implied odds for a steady rate now at 82.8%.
- Disinflationary Wage Trends Emerge. Average hourly earnings increased by just 0.1% in September, bringing the 12-month gain to 3%, the lowest since May 2021, suggesting cooling inflationary pressures from wages.
September’s U.S. jobs report revealed a surprising deceleration in hiring, with nonfarm payrolls increasing by a mere 29,000, sharply missing Dow Jones economist expectations of 84,000. This marks a notable shift in the previously resilient labor market, raising questions about broader economic momentum. Furthermore, upward revisions to prior months erased 60,000 jobs, indicating a more persistent weakness than initially perceived. The unemployment rate also edged up to 4.2% from 4.1%, contradicting recent low jobless claims and suggesting a potential soft patch in the economy, as reported by CNBC.
The immediate market reaction was significant: stock futures surged, and Treasury yields, which had recently hit multi-year highs, sharply declined. Traders interpreted the soft data as a strong signal for the Federal Reserve to pause its rate-hiking cycle, particularly at its upcoming October meeting. Jefferies chief U.S. economist Thomas Simons noted that this data “should be the nail in the coffin for an October hike.” While the establishment survey (which counts payrolls) showed weakness, the household survey (used for the unemployment rate) presented a somewhat more nuanced picture, indicating a rise in household employment by 406,000 and a 0.2 percentage point increase in the participation rate to 61.8%, its highest since May. This divergence suggests that while overall hiring slowed, more people entered or rejoined the workforce.
Despite headline inflation remaining above the Fed’s 2% target, particularly with core inflation at a 3% annual rate, wage growth showed clear signs of cooling. Average hourly earnings rose by just 0.1% in September, pushing the annual gain down to 3%, the lowest since May 2021. This disinflationary trend in wages is a key metric for policymakers assessing inflationary pressures. Industries experiencing job gains included healthcare (17,000), construction (11,000), and manufacturing (9,000). Conversely, government employment fell by 17,000, temporary help services declined by 11,000, and information services lost 10,000 jobs, potentially reflecting ongoing concerns about technological shifts like AI. Amid these shifts, analyzing economic policy and inflation trends requires a careful look at underlying data, often explored in publications like macroeconomic policy discussions.
- Sectoral Disparities: While some sectors like healthcare saw growth, others such as government and temporary services contracted, highlighting uneven recovery.
- Wage Deceleration: The significant slowdown in wage growth suggests that businesses are feeling less pressure to increase compensation, which could temper future consumer spending.
- Participation Rate Rebound: The increase in labor force participation, despite softer payroll numbers, indicates that individuals are re-engaging with the job market, which could alleviate long-term labor shortages.
On a macro level, the U.S. economy has shown robust growth, with the Commerce Department revising first and second-quarter GDP growth to 2.5% and 2.2% respectively, and the Atlanta Fed tracking third-quarter GDP at a strong 3.7%. This contrasts sharply with the recent U.S. economic data from the job market, creating a complex picture for policymakers. Investors seeking broader perspectives on global economic shifts often turn to investment analysis platforms for deeper insights into market movements.
The Ripple Effect: Unpacking Labor Market Dynamics
The surprising slowdown in the labor market translates into a clear set of ripple effects across the economy:
Weak Job Growth → Reduced Wage Pressure → Eased Inflationary Concerns → Federal Reserve Rate Pause Likelihood ↑ → Lower Treasury Yields → Increased Stock Market Appeal.
Understanding Survey Divergence: The difference between the establishment survey (which measures nonfarm payrolls by surveying businesses) and the household survey (which calculates the unemployment rate by surveying individuals) is crucial. While the establishment survey reported only 29,000 new jobs, the household survey indicated a rise of 406,000 in employment. This divergence means that while businesses may be slowing hiring, more individuals are entering the workforce and finding jobs, even if those jobs are not captured in the business payroll counts immediately. The Federal Reserve often prioritizes the household survey’s unemployment rate as a broader indicator of labor market health and participation.
While the broader economic narrative takes shape, key labor market metrics provide a quantitative foundation for analysis:
| Metric | September 2026 | August 2026 (Revised) | Significance |
|---|---|---|---|
| Nonfarm Payrolls Added | 29,000 | 133,000 | Indicates pace of job creation; September well below 84,000 expectation. |
| Unemployment Rate | 4.2% | 4.1% | Measure of joblessness; slight uptick suggests cooling. |
| Avg. Hourly Earnings (MoM) | 0.1% | N/A | Wage growth indicator; lower than expected 0.3%, easing inflation. |
| Avg. Hourly Earnings (YoY) | 3.0% | 3.1% (expected) | Annual wage inflation; lowest since May 2021, significant for Fed. |
| Labor Force Participation | 61.8% | 61.6% | Share of active workforce; increase signals more people seeking jobs. |
U.S. Fiscal Policy Commentary Amidst Labor Shifts
The latest jobs data arrives at a critical juncture for U.S. fiscal policy. With federal spending packages and potential infrastructure projects often tied to job creation metrics, a sustained slowdown could prompt renewed debate in Washington. While the Federal Reserve adjusts monetary policy, Congress faces pressure to consider complementary fiscal measures. A weakening labor market could amplify calls for targeted relief or stimulus programs, especially if consumer confidence wanes heading into the holiday season. The delicate balance between controlling inflation and supporting employment will likely be a central theme in upcoming legislative discussions, as policy experts often highlight in their educational insights.
Global Benchmarking: Reading International Labor Signals
Comparing the U.S. labor market performance to global trends reveals interesting insights. While many developed economies are grappling with varying degrees of labor tightness and wage inflation, the sharp deceleration in U.S. job growth in September stands out. Nations like Germany and Japan, facing demographic challenges, continue to experience labor shortages, whereas parts of Europe still contend with higher structural unemployment. This divergence implies that while global supply chains might ease, the individual economic paths of major powers will continue to be distinct, influenced by their unique domestic policy responses to inflation and growth, a point often underscored by global economic reporting.
The Shifting Landscape: What This Labor Market Report Means for Investors
September’s unexpectedly soft jobs report marks a pivotal moment for the U.S. economy, indicating a cooling trend in the labor market that could reshape Federal Reserve policy and investor sentiment. While signaling potential disinflation, it also introduces uncertainty about sustained economic momentum.
- The prospect of a Fed pause is now highly probable, suggesting potential stability for equity and bond markets.
- Sectors resilient to economic slowdowns, such as healthcare and utilities, may see increased investor interest.
- The slowdown in wage growth, while good for inflation, could dampen consumer spending in the coming months.
How will this evolving labor dynamic impact the broader economic narrative and corporate earnings outlooks in the final quarter of the year?
📊 StockXpo Analyst’s View
Market Impact: This softer jobs report is largely being interpreted as positive for risk assets, as it significantly reduces the immediate threat of further rate hikes, boosting liquidity and investor confidence. Equity markets could see sustained upward momentum, while bond yields might stabilize or even tick lower, making fixed-income investments more attractive. The dollar could weaken slightly against major currencies, reflecting a less aggressive Fed stance.
Sector To Watch: Given the disinflationary wage trend and reduced rate hike expectations, growth sectors that are sensitive to interest rates, particularly technology and innovation, might find renewed favor. Conversely, sectors heavily reliant on robust consumer spending or government contracts, like temporary staffing, could face headwinds. Healthcare, known for its defensive qualities, also remains a stable bet in this uncertain environment.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE ECONOMY
China Industrial Profit Growth: A Slowing Expansion Amidst Economic Headwinds
Published: Sunday, September 27, 2026 · 11:09 PM
US-China Trade Stability: A Surprise Jump in Orders Signals De-escalation
Published: Friday, September 25, 2026 · 8:19 AM


