
Published: Sunday, September 27, 2026 · 11:09 PM | Updated: Sunday, September 27, 2026 · 11:09 PM
📊 11 views


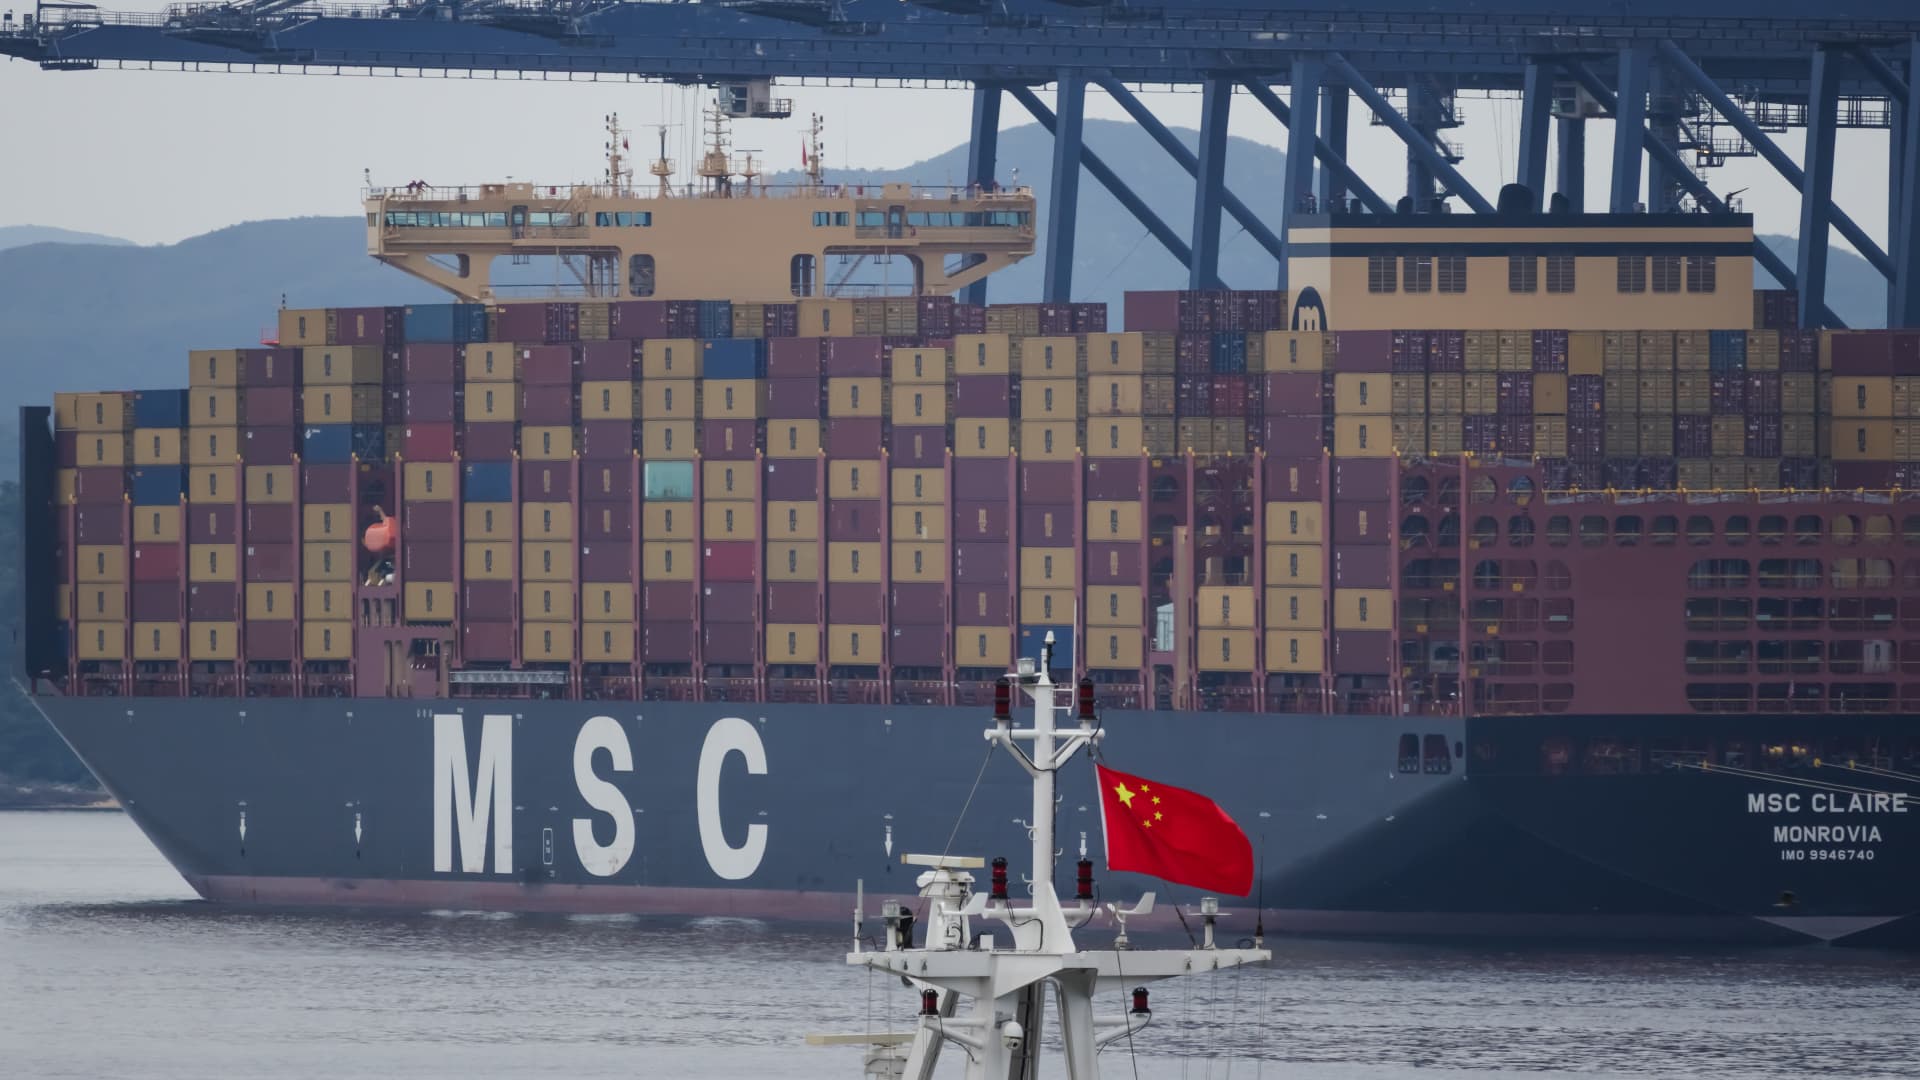
China’s latest industrial data reveals a significant deceleration, with August marking the weakest China Industrial Profit growth this year. This slowdown to 4.2% signals mounting pressure on the world’s second-largest economy, driven by persistent domestic demand issues and rising operational costs. The trend raises concerns about global supply chains and the pace of recovery for the broader Asian market.
📊 Macro-Economic Strategic Insights
- Decelerating Expansion. China’s industrial profits expanded by just 4.2% in August, marking the slowest pace this year and a continued slowdown from earlier months.
- Demand-Side Weakness. Tepid consumer demand within China is a primary drag, impacting manufacturers’ ability to maintain robust profit margins.
- Sectoral Disparities. While AI and computing equipment sectors show strong growth, traditional industries like auto manufacturing are facing fierce competition and declining profitability.
Official data from Monday showed China’s industrial profits climbing a mere 4.2% year-on-year in August, reflecting significant headwinds faced by manufacturers. This figure represents the weakest expansion recorded for the year, extending a four-month deceleration trend from a high of 24.7% in April. Despite this recent slowdown, the overall performance for the first eight months of 2026 remains positive, with a 15.7% increase, a notable reversal from the marginal 0.6% gain observed throughout 2025, which itself was the first increase after three years of declines. This indicates a complex economic landscape where recovery battles against new pressures, often influencing global stock markets.
A key driver behind the profit deceleration is the persistent weakness in consumer demand across China, coupled with a sustained rise in energy costs impacting operational expenditures. The manufacturing purchasing managers’ index (PMI) for both July and August indicated contraction, signaling ongoing challenges in factory activity. Moreover, retail sales have continued to slow, and urban investment experienced a deepening slump in August. The only significant bright spot has been industrial output, which saw a rebound, largely fueled by strong export performance.
The divergence in sectoral performance is particularly striking.
- The computer, communication, and electronic equipment manufacturing industry has been a standout, experiencing a staggering 110% profit surge for the January-to-August period, primarily due to the artificial intelligence boom.
- Conversely, the automobile manufacturing sector has seen its profits decline by 16% over the same period, battling intense domestic competition and price wars.
Economists widely anticipate Beijing to implement further stimulus measures to bolster corporate profitability and prevent deeper economic contraction, especially as consolidation accelerates in challenged sectors.
Understanding the Economic Ripple Effect
Weak Consumer Demand → Reduced Factory Orders → Slower Industrial Profit Growth
Rising Energy Costs → Higher Production Expenses → Lower Profit Margins
Manufacturing PMI Contraction → Business Confidence Erosion → Reduced Investment
Export Rebound → Partial Offset to Domestic Weakness → Sustained Industrial Output
Profitability serves as a critical barometer for economic health, reflecting a company’s ability to generate revenue beyond its costs. In macroeconomics, robust industrial profitability often correlates with higher investment, job creation, and overall economic stability, signaling a strong and competitive business environment.
Key Metrics Shaping China’s Industrial Outlook
| Metric | Value (Jan-Aug 2026) | Significance |
|---|---|---|
| Industrial Profit Growth (August) | +4.2% | Weakest monthly growth this year, indicating slowing momentum. |
| Industrial Profit Growth (Jan-Aug) | +15.7% | Overall positive, but a deceleration from earlier periods (e.g., 17.6% Jan-Jul). |
| Computer/Electronics Profit Growth (Jan-Aug) | +110% | Driven by AI boom, highlights selective sectoral strength amidst broader weakness. |
| Automobile Manufacturing Profit Growth (Jan-Aug) | -16% | Reflects intense competition and demand challenges in a key manufacturing sector. |
China’s Fiscal Policy Commentary
Beijing’s response to slowing industrial profitability will be crucial. With manufacturing activity contracting for two consecutive months and retail sales showing persistent weakness, the focus will undoubtedly shift towards more aggressive fiscal interventions. Expect targeted tax cuts, increased infrastructure spending, and potentially more direct support for struggling small and medium-sized enterprises (SMEs). The challenge lies in balancing stimulus with long-term structural reforms aimed at rebalancing the economy towards domestic consumption rather than relying heavily on exports and fixed asset investment. For a deeper dive into understanding these trends, various resources are available.
Global Benchmarking of Manufacturing Trends
While China’s industrial slowdown is domestically driven, it resonates globally. Many major economies, including those in Europe and North America, have also contended with inflationary pressures and softening demand in their manufacturing sectors. However, China’s scale means its industrial health has a disproportionate impact on global trade and supply chains. A sustained dip in China Industrial Profit could signal broader challenges in global manufacturing, especially if it dampens demand for commodities and intermediate goods. Reports from trusted sources like Bloomberg Economics and latest Reuters reports often highlight interconnected global manufacturing cycles.
The Future Trajectory of China Industrial Profit
The recent dip in China’s industrial profit growth points to underlying structural weaknesses that require targeted policy responses. While the AI-driven tech sector offers a glimpse of future growth potential, the broader manufacturing base is grappling with a difficult operating environment. Sustained government intervention will be necessary to stabilize corporate earnings and prevent a more pronounced economic downturn.
- Policymakers are expected to ramp up stimulus to cushion the slowdown.
- Sectoral divergence will likely intensify, favoring high-tech and value-added industries.
- The interplay between domestic demand and export strength will define future performance.
Can China effectively navigate these cross-currents to reignite broad-based industrial vitality?
📊 StockXpo Analyst’s View
Market Impact: This deceleration in China Industrial Profit will likely cast a shadow on investor sentiment, particularly concerning global growth prospects. While direct equity impact might be muted given some prior expectations of a slowdown, sectors reliant on Chinese industrial demand, such as commodities and heavy machinery, may face headwinds. The market will closely watch Beijing’s policy responses for signs of robust stimulus.
Sector To Watch: Investors should monitor the technology and AI-related hardware sectors, which continue to show resilience. Conversely, traditional manufacturing and automotive sectors, facing fierce competition and softening domestic demand, will remain under pressure. Monitoring economic policy shifts will be key for investors tracking these trends.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE ECONOMY
US-China Trade Stability: A Surprise Jump in Orders Signals De-escalation
Published: Friday, September 25, 2026 · 8:19 AM
Treasury Yields Surge: A Stark Warning to the Fed on Inflation
Published: Thursday, September 24, 2026 · 4:22 PM


