
Published: Sunday, September 27, 2026 · 8:32 AM | Updated: Sunday, September 27, 2026 · 8:32 AM
📊 107 views


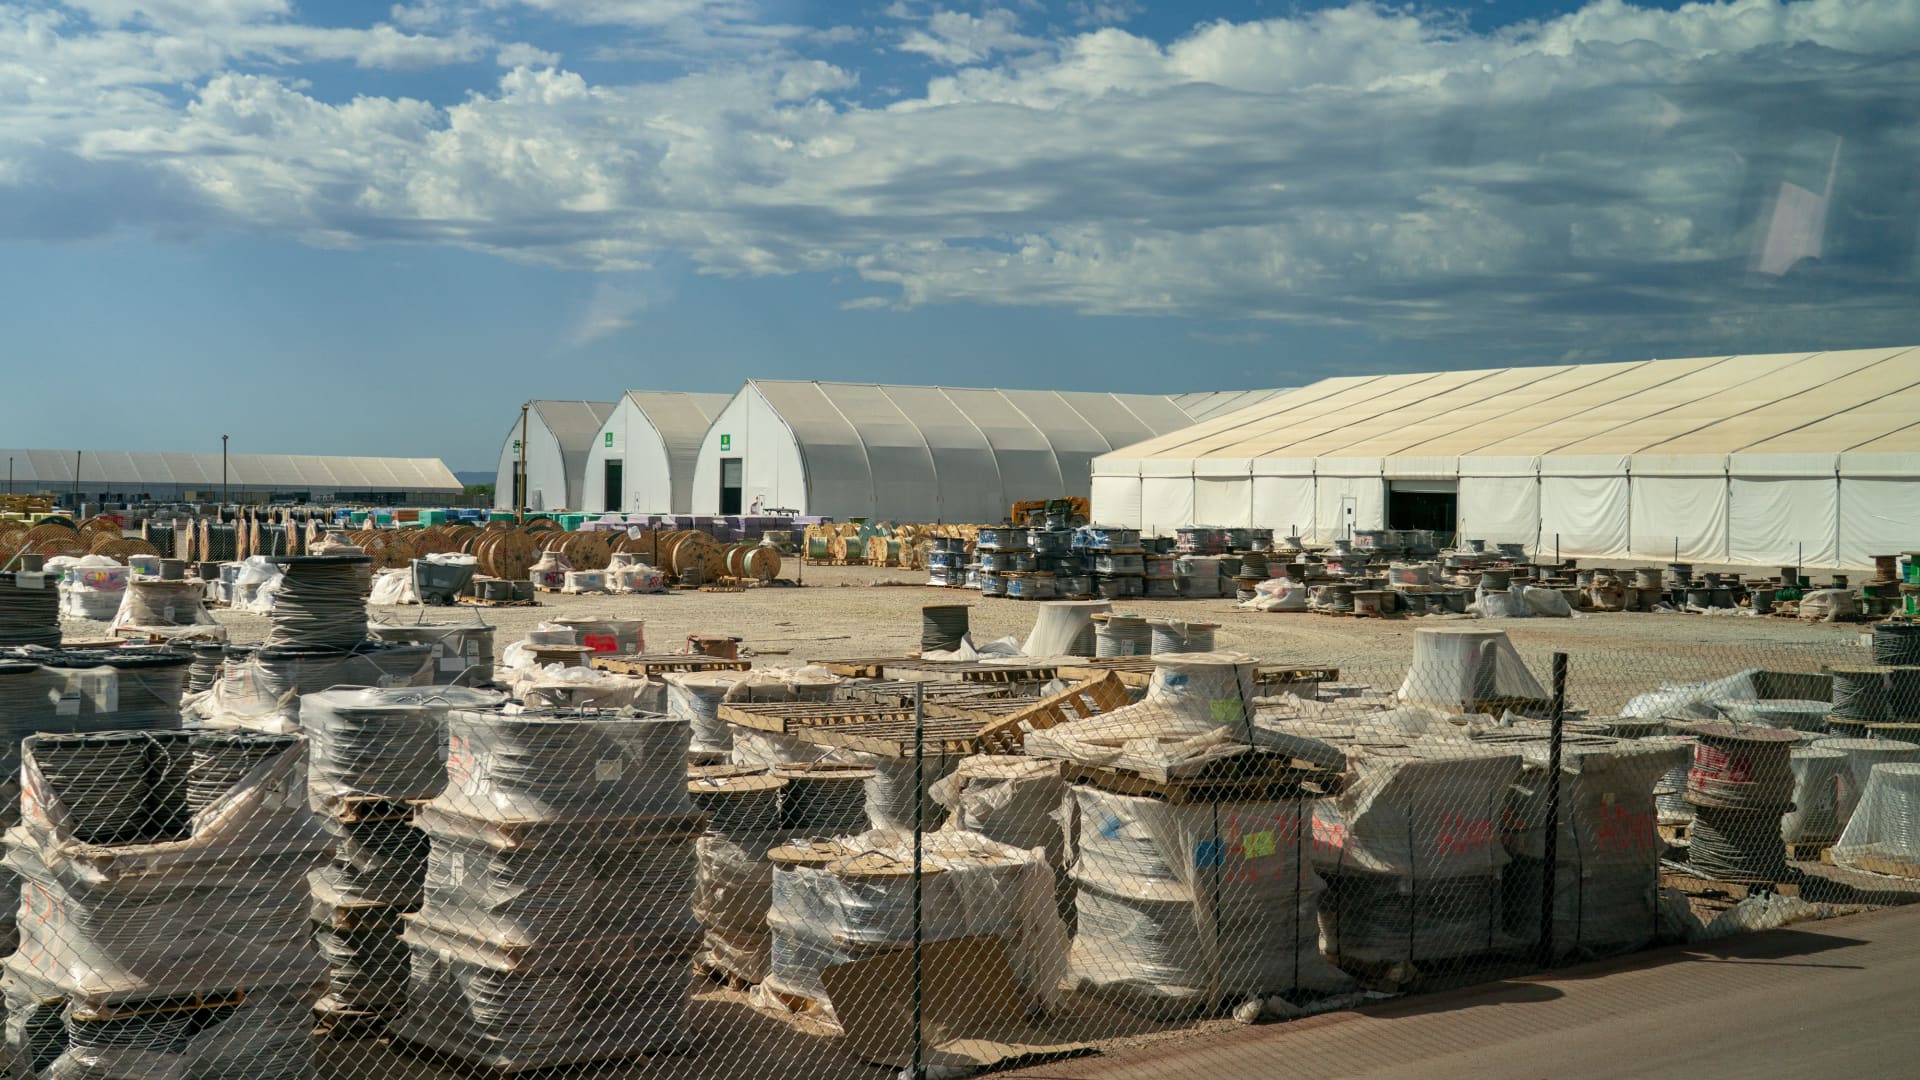
The burgeoning artificial intelligence sector, already grappling with immense capital requirements, now faces an intensifying challenge as bond yields climb to levels not seen in decades. This surge in borrowing costs is poised to significantly impact the financing landscape for AI companies, potentially reshuffling the deck for both established tech giants and emerging neocloud providers.
💰 Financial Strategy & Market Insights
- Rising Borrowing Costs. Treasury yields reaching their highest since 2007 directly increase debt expenses for AI infrastructure projects, which JPMorgan estimates will require $4.1 trillion in debt by 2030.
- Tiered Access to Capital. While hyperscalers like Amazon and Microsoft leverage investment-grade ratings for cheaper financing, smaller neoclouds face tougher conditions as lenders become more selective.
- Market Divergence. Some debt-heavy AI companies like CoreWeave show resilience, while others like Oracle experience significant stock declines, indicating a varied investor response to rising rates and project risks.
The ongoing buildout of AI infrastructure, a monumental undertaking requiring vast sums of capital, is becoming notably more expensive. With Treasury yields now near 5.17% for the 10-year, up approximately one percentage point since the start of the year, companies seeking to fund their expansion through debt must offer more attractive returns to investors. This environment directly impacts AI companies that rely heavily on borrowed capital to finance their data centers and advanced model development.
JPMorgan Chase’s June estimate of $4.1 trillion in AI-related debt issuance through 2030 underscores the scale of capital needed to meet what many perceive as insatiable demand for AI services. This massive funding requirement, set against a backdrop of rising interest rates, presents a complex picture for market participants, often highlighted in comprehensive financial market reports. The cost of this debt is a critical factor, directly influencing the viability and profitability of ambitious AI projects.
For instance, CoreWeave, a prominent neocloud provider, acknowledged in its latest quarterly SEC filing that a 100-basis point increase in rates could boost its interest expense by $30 million. This illustrates the direct financial pressure on firms with significant floating-rate debt. Conversely, while Oracle, deeply invested in AI expansion, has seen its stock decline 7% for the week and 30% year-to-date, reflecting market concerns over its debt-funded projects, CoreWeave’s shares surprisingly rose almost 8% this week. This divergence highlights a nuanced market perception of risk and potential, suggesting some AI companies are better positioned to weather the current rate environment or are perceived to have stronger growth trajectories. SoftBank, a major AI capital provider, recently secured $11.1 billion through a junk-bond sale, accepting yields as high as 9.75% for its 7-year tranche. Siebert Financial’s Mark Malek noted this indicates a ‘price insensitive’ approach, emphasizing the urgent need for capital to maintain competitive advantage in the AI race. The broader implications for the financial sector are significant, as this trend could accelerate a re-pricing of risk across various asset classes, a key topic in current financial discussions.
- The current market environment forces a re-evaluation of asset valuation models for AI-centric businesses, with higher discount rates impacting future cash flow projections.
Beyond financing, the AI sector faces other headwinds. Industry leaders at OpenAI and Anthropic have advocated for slowing AI development, citing concerns about advanced models potentially exceeding human control. Furthermore, a growing public backlash against AI data centers, fueled by environmental and resource concerns, is impacting permitting processes, exemplified by Texas Governor Greg Abbott’s temporary halt on data center environmental permits. This regulatory and social pressure adds another layer of complexity for AI infrastructure developers.
Despite these challenges, the demand for AI services remains robust. Meta’s Muse personal assistant app, for example, rapidly gained over 2.5 million downloads in its first two weeks, outpacing ChatGPT on Apple’s App Store. Evercore’s Mark Mahaney predicts Muse could reach 100 million users within 6 to 12 months, signaling the immense market appetite for accessible AI. This strong demand, according to Andrew Giudici of KBRA and Haim Zaltzman of Latham & Watkins, might compel borrowers to accept higher financing costs, as securing compute capacity for future demand, especially with commitments to leaders like OpenAI and Anthropic, outweighs marginal rate increases.
Risk vs. Reward: Navigating AI Investment in a High-Yield Environment
- Upside Potential:
- Continued explosion in demand for AI services could justify higher capital expenditure and borrowing costs, leading to substantial revenue growth for companies that secure compute capacity.
- Early movers who absorb current financing costs may solidify market leadership, especially those with long-term contracts with major AI model developers like OpenAI and Anthropic.
- Investment-grade hyperscalers (Amazon, Google, Microsoft, Meta) can leverage their balance sheets to gain competitive advantages by building out infrastructure at relatively cheaper rates.
- Downside Risks:
- Increased interest expenses could significantly erode profit margins and free cash flow for debt-heavy AI companies, particularly smaller neoclouds with less financial cushion.
- Lender selectivity and a shrinking pool of interested financiers could bottleneck capital for many AI projects, potentially slowing the overall buildout.
- Regulatory and social backlash against data centers could lead to permitting delays, increased operational costs, and localized moratoriums, hindering expansion plans.
- Elevated debt burdens combined with slower revenue growth or unexpected operational challenges could lead to credit rating downgrades or even defaults for highly leveraged firms.
In the current climate, ‘price insensitive’ capital raises, where companies prioritize securing funds regardless of the cost, indicate a fierce competitive drive for compute capacity in the AI sector. This strategy, while ensuring growth, directly elevates a company’s financial risk profile, placing a premium on robust revenue generation to service higher debt obligations.
Key Financial Metrics for AI Infrastructure
| Company/Metric | Description | Value |
|---|---|---|
| JPMorgan AI Debt Estimate | Projected AI-related debt issuance through 2030 | $4.1 Trillion |
| 10-Year Treasury Yield | Current yield (approx.) | ~5.17% |
| SoftBank Junk Bond Yield | Highest yield for 7-year tranche | 9.75% |
| CoreWeave Interest Expense Sensitivity | Increase for every 100-basis point rate hike | $30 Million |
| Oracle Weekly Stock Performance | Decline for the week | 7% |
| Oracle Year-to-Date Stock Performance | Decline for the year | 30% |
AI Infrastructure Yield Curve Dynamics
The steep ascent of the yield curve, particularly the 10-year Treasury yield, is fundamentally reshaping the economics of long-term AI infrastructure financing. Projects like large-scale data centers often require multi-year debt instruments, making them highly sensitive to sustained elevated rates. This translates into significantly higher debt service costs over the lifespan of these assets, challenging traditional valuation models that assumed a lower cost of capital. Furthermore, the spread between investment-grade corporate bonds and high-yield instruments is widening, accentuating the divide between well-capitalized hyperscalers and smaller, more speculative ventures. This dynamic will force many AI companies to critically reassess their project timelines and funding strategies, potentially favoring shorter-term, higher-cost solutions or necessitating equity raises to de-risk balance sheets.
Neocloud Market Sentiment Tracker
Lender sentiment towards emerging neocloud providers is shifting, becoming increasingly discerning. While the AI boom continues to attract capital, the market for debt financing is segmenting. Mitsubishi HC Capital America’s Riley Thompson noted a reduction in the pool of ‘truly interesting’ neoclouds from 50 to perhaps 20, suggesting a flight to quality and proven business models. This heightened scrutiny indicates a demand for clearer pathways to profitability, stronger revenue visibility, and more robust risk management frameworks. Lenders are not merely seeking higher yields; they are prioritizing credit quality and project viability, even if it means foregoing potentially lucrative but riskier deals. This evolving sentiment impacts liquidity for a crucial segment of AI companies, pushing them towards more stringent covenants and potentially dilutive financing structures. To stay ahead of the curve, investors should closely monitor shifts in private credit terms for insights into broader market health, which you can regularly find in our educational financial insights.
The Shifting Landscape for AI Companies: Capital, Competition, and Control
The current financial environment marks a pivotal moment for AI companies, where unprecedented demand clashes with rising capital costs and increasing regulatory scrutiny, a dynamic regularly covered by Reuters in business and finance news. While the allure of AI’s growth trajectory remains strong, the true test will be the industry’s ability to adapt to a more expensive and selective financing landscape.
- The escalating cost of debt will likely accelerate consolidation within the AI infrastructure sector, favoring financially robust hyperscalers.
- Smaller AI companies reliant on debt may need to pivot towards equity financing or strategic partnerships to secure the necessary capital for expansion.
- The dual pressures of economic shifts and public backlash mandate a more sophisticated approach to risk management and community engagement for data center projects.
How will these rising costs and growing external pressures reshape the competitive dynamics and innovation pace among leading AI innovators?
📊 StockXpo Analyst’s View
Market Impact: The current surge in bond yields significantly tightens market liquidity for high-growth, debt-dependent sectors like AI infrastructure. This environment will likely lead to a re-evaluation of asset valuations, as higher discount rates impact future earnings potential. We anticipate increased volatility, particularly for publicly traded AI pure-plays with substantial debt, as investors price in higher borrowing costs and potential profit erosion. This could create opportunities for long-term investors to pick up undervalued assets from companies with solid fundamentals but temporarily impacted by market sentiment.
Sector To Watch: The cloud computing and data center sectors will be under intense scrutiny. While hyperscalers (e.g., MSFT, AMZN, GOOGL) possess the financial fortitude and investment-grade ratings to weather higher rates, smaller ‘neoclouds’ and AI hardware developers may face significant hurdles in securing expansion capital. Conversely, companies with strong cash flows or those less reliant on debt for growth might emerge stronger, potentially gaining market share from struggling competitors. Watch for strategic partnerships or acquisitions as financially stronger players look to capitalize on distressed assets within the AI ecosystem. For more in-depth market analysis, visit StockXpo.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE FINANCE
Thucydides Trap Volatility: Xi’s New Diplomatic Stance on US-China Relations
Published: Saturday, September 26, 2026 · 2:23 AM
Bitget Hack: Over $350 Million in Crypto Assets Stolen, North Korea Suspected
Published: Friday, September 25, 2026 · 2:44 AM


