Published: Friday, October 9, 2026 · 8:54 AM | Updated: Friday, October 9, 2026 · 8:54 AM
📊 11 views


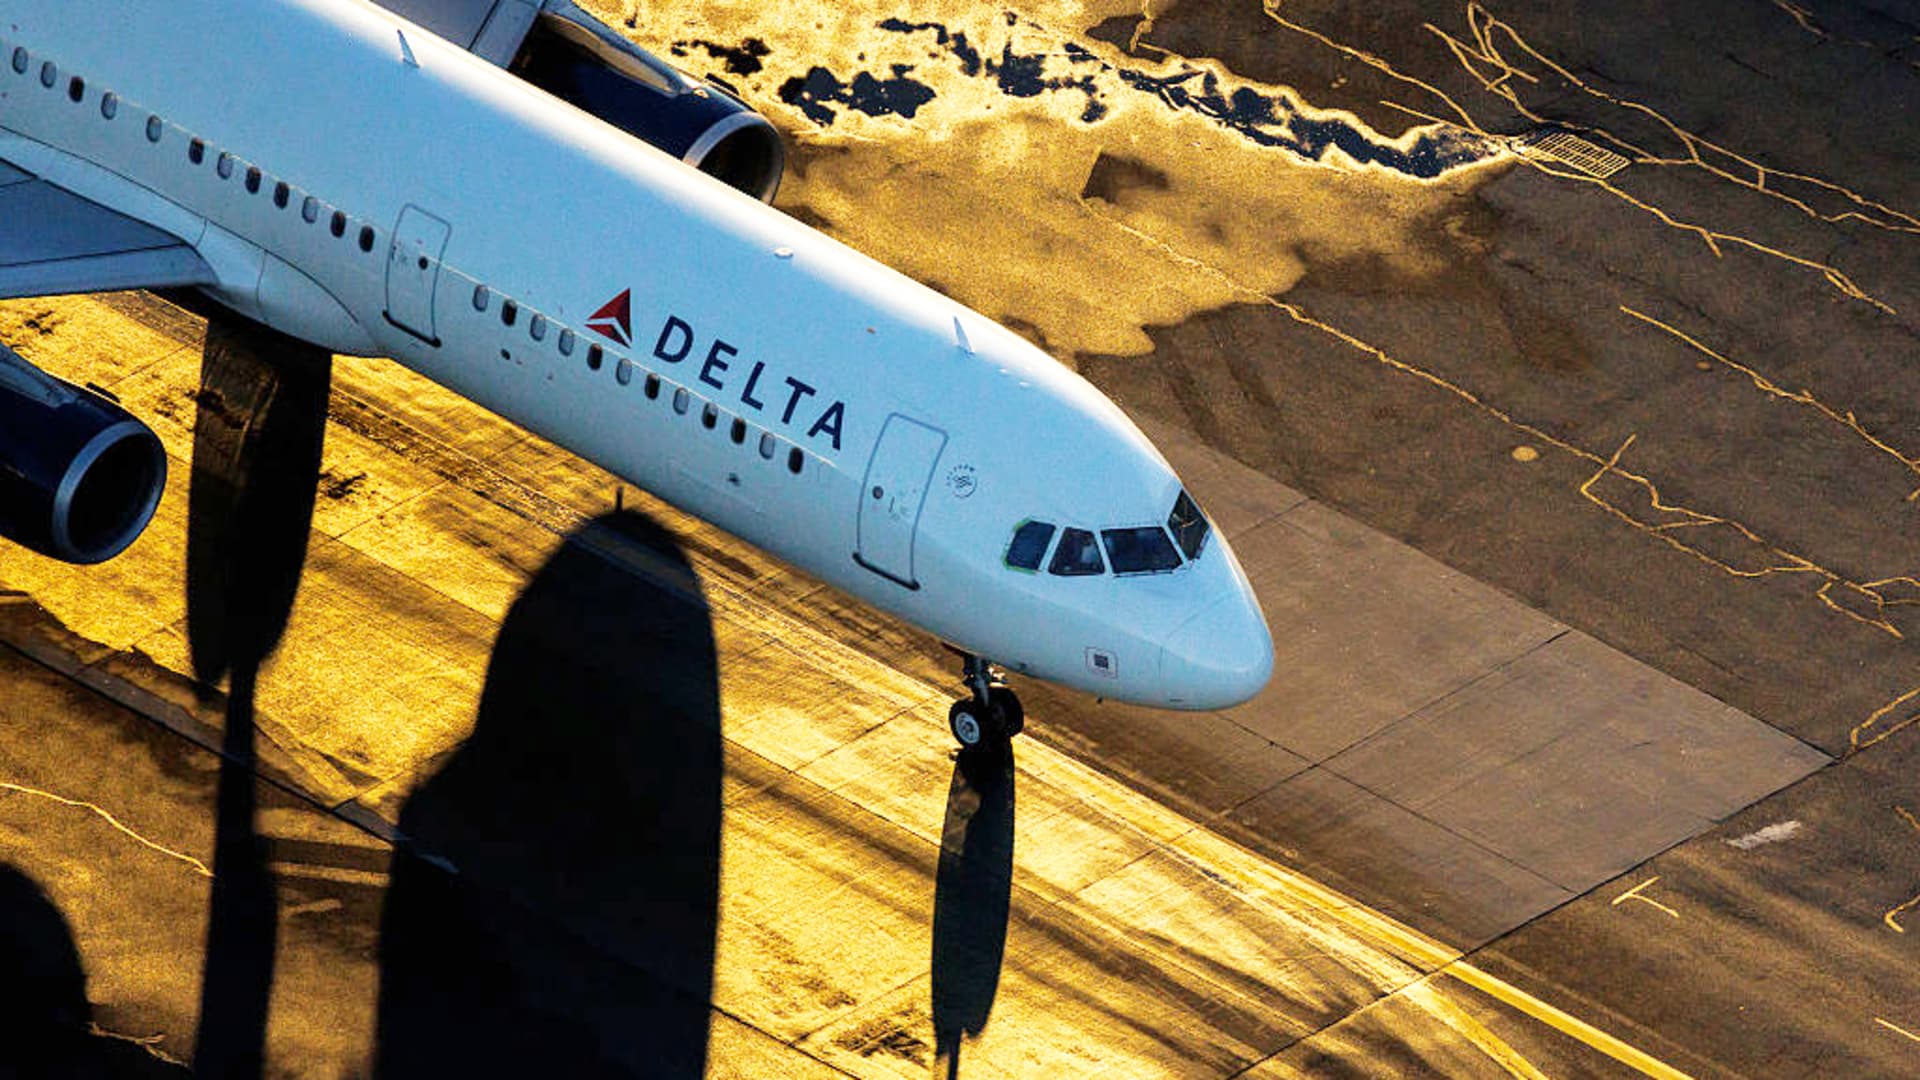
Delta Air Lines (DAL) has adjusted its 2026 profit and free cash flow forecasts downward, citing persistent high fuel costs despite robust consumer demand. This revision signals a tighter margin environment for the airline sector, even as strong travel intent allows carriers to pass on increased expenses through higher fares. Investors are now evaluating how this short-term pressure on profitability balances against Delta’s long-term operational strengths and market positioning.
💎 Strategic Investment & Portfolio Insights
- Fuel Price Impact. Soaring jet fuel costs have forced a significant cut to Delta’s 2026 earnings outlook, highlighting the airline industry’s vulnerability to energy market volatility and geopolitical events.
- Resilient Demand & Pricing Power. Despite higher fares, CEO Ed Bastian confirms strong consumer and business travel demand across all segments, indicating the airline’s ability to maintain revenue growth and premium segment strength.
- Missed Q3 Estimates. Delta missed consensus estimates for Q3 EPS and adjusted revenue, marking its first miss in two years and underscoring the immediate pressure on profitability from rising operational costs.
Delta Air Lines’ recent forecast revision paints a clear picture of the aviation industry’s current landscape: robust passenger demand clashing with inflationary pressures, particularly from jet fuel. The airline now anticipates full-year adjusted earnings per share between $5.10 and $5.60, a notable reduction from its earlier projection of $6.50 to $7.50 issued in July. This aligns with broader trends reported by industry news reports on fuel impact. Similarly, the free cash flow outlook for the year has been trimmed from a potential $4 billion down to $2.5 billion, reflecting the significant capital outflows driven by fuel expenses.
CEO Ed Bastian, speaking to CNBC, emphasized that despite these financial adjustments, the underlying demand for air travel remains exceptionally strong. The airline has largely been successful in passing on much of a projected $6 billion increase in annual fuel costs to consumers through elevated fares. Jet fuel prices in the U.S. Gulf of Mexico region have nearly doubled over the past year, climbing to $4.34 on Thursday from $2.19 a year prior, according to FactSet data. This resilience in demand spans all customer segments—business and leisure—and various cabin classes and geographies.
While Delta holds a unique advantage with its Trainer, Pennsylvania, refinery, which processes crude oil into jet fuel and other products, this benefit hasn’t fully insulated the company from the broader market’s fuel price surge. The airline’s third-quarter performance, encompassing the peak summer travel season, saw adjusted earnings per share of $1.72 against analyst expectations of $1.75, and adjusted revenue of $17.59 billion compared to the $17.67 billion estimated by LSEG. This marked the first time in two years that Delta’s reported figures fell short of Wall Street consensus. However, the company still reported a 20% increase in revenue for the fourth quarter over the same period last year, outpacing the 16% rise in Q3 when adjusting for the refinery’s benefit.
Premium revenue, a crucial segment for Delta’s strategy, continued its upward trajectory, growing 18% in the third quarter to $6.82 billion, slightly outperforming the 12% rise in main cabin sales to $6.8 billion. This strong performance in higher-margin services highlights the success of Delta’s long-term investment strategies focused on customer experience. Separately, the news also touched on Delta’s decision to partner with Amazon Leo for in-flight Wi-Fi, rather than SpaceX Starlink, leading to public remarks from Elon Musk. Bastian downplayed the dispute, stating Delta’s prior engagements with SpaceX didn’t align with scaling needs at the time.
The revised Delta Air Lines forecast creates a direct cause-and-effect chain for portfolio managers: Persistent high fuel costs → Lower profit margins and free cash flow → Potential short-term revaluation of airline stocks. For long-term capital preservation, this necessitates a careful reassessment of sector allocations. While demand signals remain strong, the lack of pricing power to fully offset cost inflation over the next few years could depress earnings multiples. Diversification into sectors less sensitive to energy price volatility becomes more critical, balancing cyclical airline exposure with defensive assets or industries with clearer cost control mechanisms. This development prompts a closer look at a company’s unique competitive advantages, such as Delta’s refinery, which offers a partial hedge against fuel price swings, or its strong brand loyalty that sustains premium segment growth. For a deeper understanding of deeper market trends, explore our research.
“For a diversified portfolio aiming for alpha generation, Delta’s situation underscores the need to differentiate between top-line strength and bottom-line erosion. The ability to pass on costs speaks to market power, but the revised outlook reflects a squeeze on net profitability. Prudent investors should view this as a potential re-entry point for long-term positions if the market overreacts, but only after evaluating the sustainability of demand against future fuel price scenarios and operational efficiencies.”
Delta’s Q3 2026 performance presented a mixed picture, with strong revenue growth in premium segments despite the overall earnings miss:
| Metric | Reported Q3 2026 | Analyst Estimates (LSEG) | Significance |
|---|---|---|---|
| Adjusted Earnings Per Share | $1.72 | $1.75 | Slight miss, first in two years, showing fuel cost pressure. |
| Adjusted Revenue | $17.59 billion | $17.67 billion | Strong growth year-over-year (16%) but fell short of projections. |
| Net Income (GAAP) | $756 million | N/A | Down 47% from prior year, primarily due to higher costs. |
| Premium Revenue Growth | 18% ($6.82 billion) | N/A | Highlights success in targeting higher-value customer segments. |
| Main Cabin Sales Growth | 12% ($6.80 billion) | N/A | Solid growth, but slower than premium, indicating strategy focus. |
Delta Air Lines Competitive Benchmarking: Navigating a Shifting Landscape
When assessing the competitive position of Delta Air Lines, its revised forecast reflects a broader industry challenge. While all major carriers like United, American, and Southwest face similar fuel cost pressures, Delta’s ability to maintain strong demand and higher fares, particularly in its premium segment, positions it favorably. Its direct ownership of a refinery provides a unique, though not complete, hedge against fuel price volatility, distinguishing it from peers. Furthermore, Delta’s consistent focus on customer service and experience, including its early adoption of free Wi-Fi and strategic partnerships like Amazon Leo for internet, aims to build a global market perspectives. This contrasts with competitors who have opted for Starlink, indicating a strategic divergence in passenger experience and technology investments. The premium segment’s outperformance (18% growth) against main cabin (12% growth) is a testament to its successful market differentiation, a critical factor for long-term capital preservation in a cyclical industry.
Delta Air Lines Risk-Reward Matrix: A Balancing Act for Investors
From a risk-reward perspective, Delta Air Lines presents a nuanced picture. The primary risk remains sustained high fuel prices, exacerbated by geopolitical instability, which directly impacts profitability and free cash flow. Execution risk also exists in balancing fare increases with customer demand elasticity, although CEO Bastian’s comments suggest demand remains robust. A broader economic downturn could quickly erode travel demand, reversing the current pricing power. On the reward side, Delta’s strong brand, premium segment growth, and operational efficiencies (including its refinery) offer a competitive edge. If fuel prices stabilize or decline, the airline is poised for significant operating leverage due to maintained high demand and structural cost discipline. The ongoing modernization of its fleet and technological advancements in customer experience could also drive long-term alpha generation by enhancing customer loyalty and operational efficiency. Investors should weigh these factors carefully when considering their latest market insights.
Delta Air Lines’ Outlook: Charting a Course Through Market Headwinds
Delta Air Lines’ updated financial outlook for 2026, while reflecting immediate challenges from fuel costs, highlights its strategic resilience through robust demand and pricing power. The airline continues to demonstrate its capability to navigate volatile market conditions, although investors must temper expectations for near-term earnings growth.
- The airline’s strong demand across all segments underscores the fundamental strength of the travel recovery.
- Premium revenue growth signifies the success of Delta’s strategy to capture higher-value customers.
- Ongoing fuel price volatility remains the most significant external variable influencing future profitability.
How will Delta’s unique operational hedges and brand loyalty position it for sustained profitability if fuel costs remain elevated?
📊 StockXpo Analyst’s View
Market Impact: The revision in Delta’s forecast, even with strong demand, will likely cause a ripple effect across the airline sector, prompting a re-evaluation of valuation multiples as fuel costs squeeze margins. It suggests that while the post-pandemic travel boom is robust, profitability is increasingly sensitive to exogenous factors, potentially leading to increased short-term volatility for airline stocks and a more cautious sentiment for cyclical industries.
Sector To Watch: Investors should keenly watch the broader transportation and logistics sectors. If airlines like Delta continue to pass on increased fuel costs, it indicates strong consumer spending, but also inflationary pressures that could impact cargo and shipping companies. Conversely, energy producers, particularly refining operations, may continue to benefit from these commodity trends, offering a potential hedge for diversified portfolios.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE INVESTMENT NEWS
PepsiCo Earnings Forecast Cut: Alpha Generation Amid North American Lag
Published: Thursday, October 8, 2026 · 6:41 AM
Third-Quarter Earnings Season: Alpha Opportunities Emerge as S&P 500 Profits Boom
Published: Wednesday, October 7, 2026 · 3:18 PM