
Published: Sunday, November 8, 2026 · 9:28 PM | Updated: Sunday, November 8, 2026 · 9:28 PM
📊 10 views



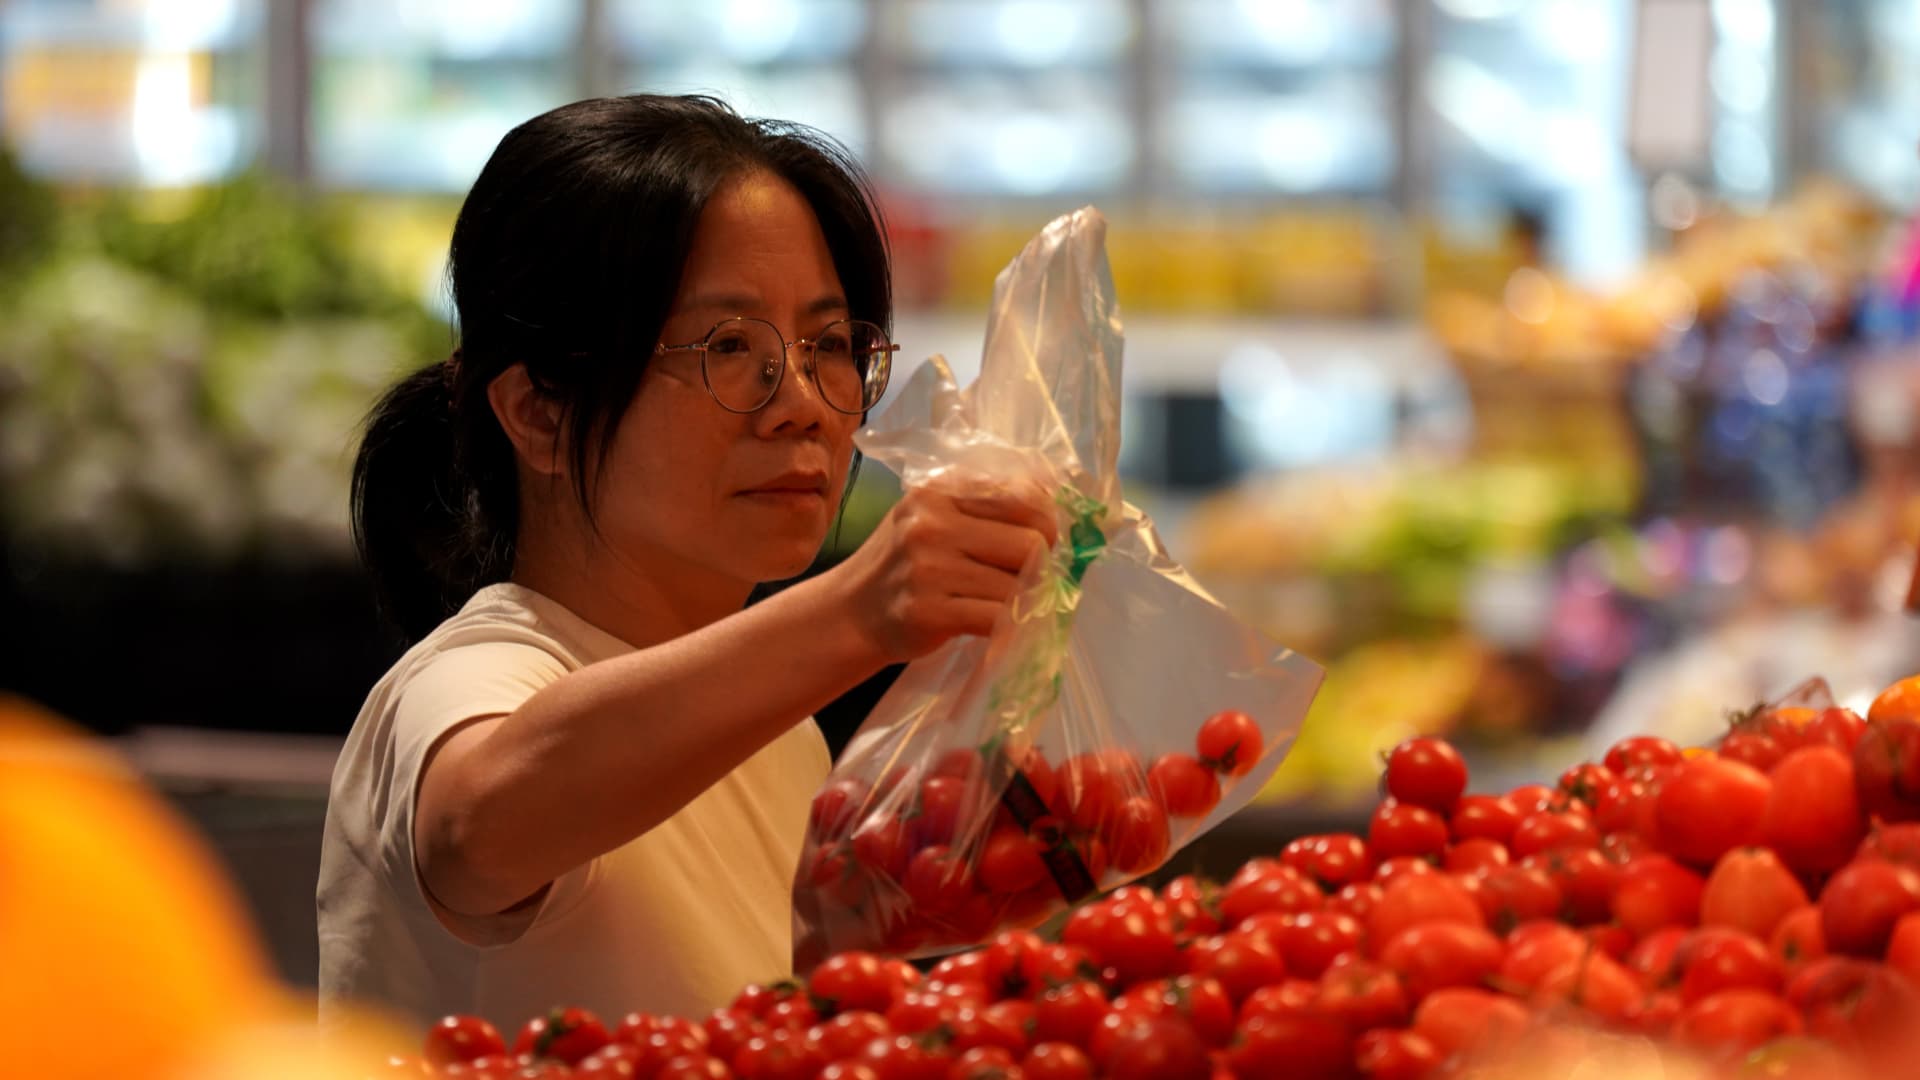
China’s economy is presenting a complex picture, marked by a significant acceleration in producer prices juxtaposed against a surprising deceleration in consumer inflation. This divergence signals a challenging environment for policymakers in Beijing and has notable implications for global trade and market stability, especially given the rising economic policy considerations.
📊 Macro-Economic Strategic Insights
- Producer Price Index (PPI) Hits Four-Year High. China wholesale inflation, measured by the PPI, surged to 5.7% in October, its fastest pace since June 2022 and exceeding economist expectations of 5.3%. This indicates significant cost pressures at the factory gate.
- Consumer Price Index (CPI) Decelerates Unexpectedly. In contrast to rising wholesale costs, consumer inflation slowed to 0.7% in October, missing Reuters’ polled expectations of 0.8% and marking the first deceleration after two months of increases.
- Divergent Inflationary Pressures. This dual-track inflation suggests strong industrial demand and rising input costs are not fully translating into higher consumer prices, pointing to underlying weakness in domestic demand despite recent signs of economic expansion.
October’s data from China’s National Bureau of Statistics paints a nuanced economic landscape. The 5.7% surge in the Producer Price Index (PPI) is a clear indicator that industrial sectors are grappling with escalating input costs, driven by factors such as commodity prices and supply chain dynamics. This sustained acceleration, now for the third consecutive month, could squeeze corporate profit margins, particularly for firms with limited pricing power. This persistent investment analysis suggests a challenging environment for many manufacturers.
Conversely, the cooling of the Consumer Price Index (CPI) to 0.7% signals that these higher producer costs are not being passed on to the end-consumer as readily. This indicates subdued domestic consumption, a persistent challenge for Beijing as it seeks to rebalance its economy towards internal demand. While China’s economy showed stronger-than-expected growth in the third quarter and saw a sharp beat in September’s retail sales, the latest CPI figures underscore that consumer confidence and spending power may still be fragile, potentially influenced by ongoing property market concerns and employment uncertainties.
Understanding the Economic Ripple Effect
The divergence between rising PPI and slowing CPI creates distinct economic consequences:
- Higher Input Costs (PPI) → Lower Corporate Profit Margins → Reduced Investment & Potential Slower Job Growth.
- Weak Consumer Demand (CPI) → Intense Price Competition → Deflationary Pressures on Consumer Goods.
- Government Stimulus (Q3 Growth) → Increased Industrial Activity → Further Upward Pressure on PPI.
Producer Price Index (PPI) vs. Consumer Price Index (CPI): PPI measures the average change over time in the selling prices received by domestic producers for their output. CPI, on the other hand, measures the average change over time in the prices paid by urban consumers for a market basket of consumer goods and services. A widening gap, where PPI rises significantly while CPI stagnates or falls, typically indicates that businesses are absorbing higher costs, which can hurt profitability, or that consumer demand is too weak to support price increases.
This bifurcated inflation trend underscores the complexities facing China’s economic planners. The government’s efforts to stimulate the economy, which contributed to stronger Q3 growth, appear to have primarily boosted industrial activity and demand for raw materials, pushing up factory-gate prices. However, these impulses have yet to fully translate into robust consumer spending, which remains critical for sustainable economic recovery.
Key Economic Metrics
- Producer Price Index (October): 5.7% (vs. 5.3% expected). This metric indicates the strength of upstream cost pressures and industrial demand, signaling inflationary risks for manufacturers.
- Consumer Price Index (October): 0.7% (vs. 0.8% expected). A critical gauge of household spending power and overall demand-side inflation. Its slowdown points to persistent softness in domestic consumption.
China’s Inflationary Risks Under Scrutiny
The rising global economic shifts and commodity prices continue to pose a significant inflationary risk to China’s industrial sector. Higher energy and raw material costs, exacerbated by geopolitical factors and supply chain bottlenecks, directly impact factory-gate prices. While Beijing has tools to manage these pressures, including strategic reserves and price controls, the persistent rise in PPI indicates these measures may not fully insulate producers. Simultaneously, the muted CPI introduces a different risk: demand-side deflation, where a lack of consumer appetite could lead to price wars and further economic stagnation.
China Regional Trends and Economic Disparities
China’s vast geography often means economic trends manifest differently across regions. Coastal, export-oriented industrial hubs, which are heavily reliant on global trade and manufacturing, are more susceptible to the direct impact of rising PPI through higher production costs. Meanwhile, inland provinces, often more dependent on domestic consumption and agricultural output, might feel the effects of a slowing CPI more acutely, struggling with weaker local demand. Understanding these market trends requires a granular view, highlighting the challenge for uniform national policy implementation.
China Wholesale Inflation: Navigating a Complex Economic Outlook
The latest data presents Chinese policymakers with a delicate balancing act. While the broader economy shows resilience, the stark divergence between soaring China wholesale inflation and subdued consumer prices necessitates careful calibration of monetary and fiscal tools. Sustaining growth without triggering broader inflation, while simultaneously stimulating domestic demand, will be the central challenge.
- Beijing’s policy response will likely focus on targeted support for small and medium-sized enterprises struggling with input costs, alongside measures to boost household income and confidence.
- The global implications include potential shifts in export pricing from China, impacting global supply chains and imported inflation for other economies.
- Monitoring the real estate sector and its impact on consumer wealth remains crucial for unlocking stronger domestic consumption.
How will Beijing navigate these dual inflationary pressures to foster sustainable, balanced growth in the coming quarters?
### 📊 StockXpo Analyst’s View
Market Impact: This mixed inflation data signals underlying structural challenges for China, potentially tempering investor enthusiasm for broader market rallies. Equity markets may see volatility, particularly in sectors highly exposed to rising input costs or weak consumer spending. Bond markets could see increased demand as investors seek safety amid economic uncertainty, while the yuan might experience pressure from concerns over deflationary forces in the consumer sector.
Sector To Watch: Industrial commodities and heavy manufacturing sectors could continue to benefit from strong upstream demand, but their profitability will depend on their ability to pass on costs. Conversely, consumer discretionary and retail sectors will remain under pressure until robust domestic demand materializes. Investors should monitor technology firms for innovation that can drive efficiency and reduce cost dependencies.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE ECONOMY
US Economy’s Robust Growth: 165,000 Jobs Added, Unemployment Dips to 4.1%
Published: Friday, November 6, 2026 · 9:11 AM
Bank of England Interest Rate Hike Signals Inflation Warning and Macro Stability
Published: Thursday, November 5, 2026 · 7:19 AM


