
Published: Tuesday, October 13, 2026 · 2:23 AM | Updated: Tuesday, October 13, 2026 · 2:23 AM
📊 15 views


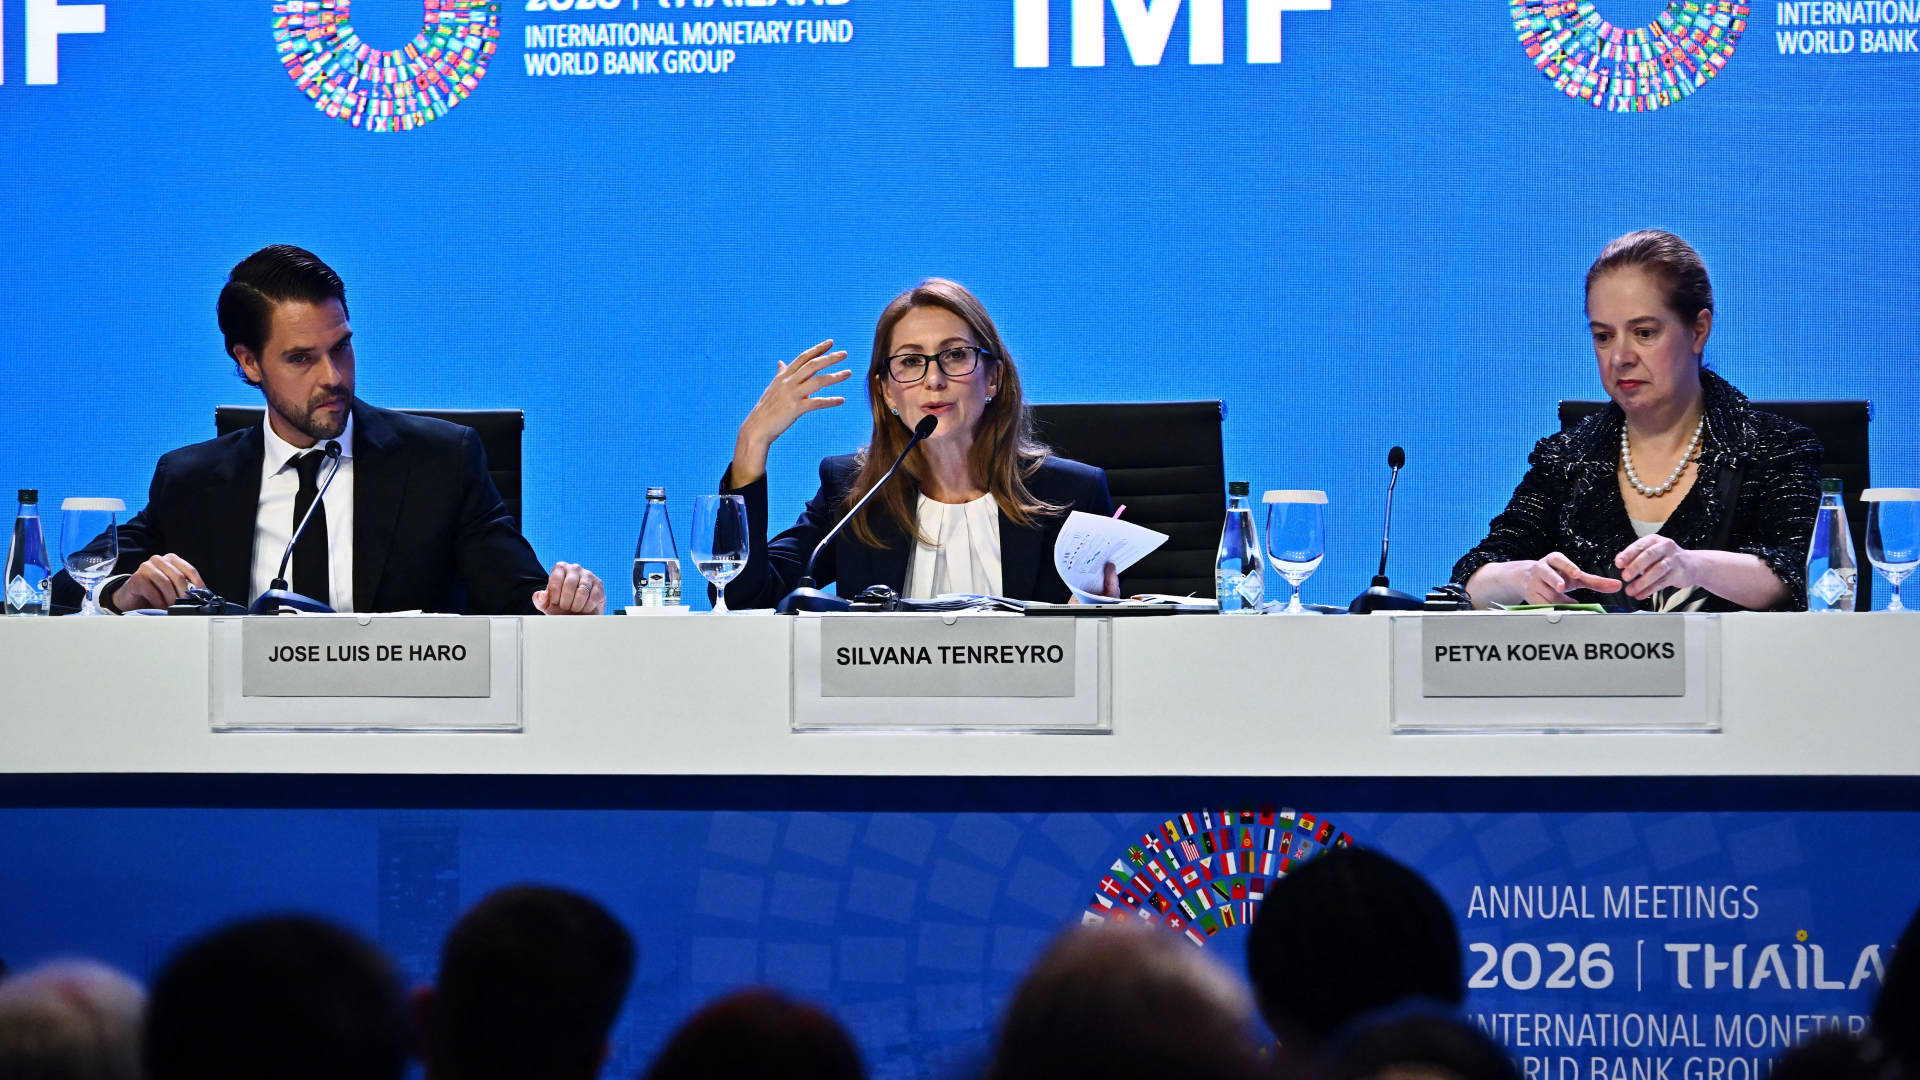
The International Monetary Fund (IMF) has adjusted its global growth forecast upwards for the current year, attributing a milder Global Slowdown to a surge in AI-driven investment. This revised outlook, however, comes with a stern caution: the global economy’s capacity to absorb further shocks is rapidly approaching its breaking point amidst ongoing geopolitical tensions and mounting public debt.
📊 Macro-Economic Strategic Insights
- AI as a Demand Impulse. Significant investment in AI infrastructure is temporarily buoying global economic activity, offsetting impacts from geopolitical conflicts.
- Resilience Nearing Limits. Despite stronger-than-expected growth, the IMF warns that strategic buffers like oil reserves are depleting, raising vulnerabilities to future shocks.
- Persistent Inflationary Pressures. Elevated energy costs and the demand shock from AI investment are expected to keep global inflation above pre-war levels into 2027.
The IMF’s latest World Economic Outlook highlights a nuanced global economic landscape, where an unexpected investment boom in artificial intelligence is providing a critical ‘demand impulse.’ This surge, primarily channeled into sectors like semiconductors and data centers, has enabled the global economy to better withstand the ongoing Middle East conflict and persistent trade tensions than previously anticipated. The Fund now projects a 3.1% global growth rate for 2026, a slight uptick from its July forecast of 3%, though still slower than the 3.5% seen last year. For 2027, the forecast holds steady at 3.4%.
However, this resilience is not without its costs. IMF Economic Counsellor Silvana Tenreyro emphasized that global economic buffers are ‘rapidly narrowing,’ urging policymakers to actively restore fiscal space and reinforce supply-chain security. The reliance on strategic oil reserves, currently being drawn down by 2.7 million barrels per day, underscores a growing vulnerability to sharp price movements, particularly if energy constraints begin to impede the AI-led momentum. Inflation remains a concern, with the IMF forecasting 4.7% for the current year and 4.1% for 2027, an increase from its earlier 3.9% projection for 2027, partly due to revised expectations for the Strait of Hormuz reopening.
Growth is also becoming increasingly concentrated, with just 32 economies now accounting for 95% of global expansion, a stark decline from 54 economies previously. This divergence creates significant winners and losers in the current environment:
- Tech-Centric Economies: Countries with strong exposure to AI-driven demand are thriving. Taiwan is projected to see 10.7% growth this year, and South Korea 3.3%, largely due to semiconductor demand. The U.S. is expected to expand by 2.3% in both 2026 and 2027, bolstered by robust private consumption, fiscal policies, and tech investments.
- Energy Importers and Emerging Markets: These nations face substantial headwinds. The Eurozone is set for a modest 1.1% growth this year amidst higher energy costs and subdued consumer confidence. The Middle East and Central Asia region is forecast to contract by 0.3%, with some Gulf states experiencing double-digit declines before a projected rebound in 2027.
- Asian Giants: India continues its trajectory as the fastest-growing major economy, with upgrades to 7.0% growth for both 2026 and 2027, driven by strong domestic demand and AI investment. China, however, is expected to slow to 4.5% this year and 4.0% in 2027, weighed down by higher oil prices, structural issues in its property sector, and sluggish consumption.
This uneven distribution of growth underscores a critical reallocation of economic activity, favoring nations that can either supply or leverage AI-related advancements while penalizing those dependent on energy imports.
The Ripple Effect: Economic Cause and Consequence
The interplay of global forces creates clear economic consequences:
- AI Investment Surge → Increased Demand for Tech Components → Boosted Manufacturing & Services (e.g., in Taiwan, South Korea, U.S.).
- Middle East War & Energy Disruptions → Elevated Energy Costs → Higher Import Bills for Non-Producers → Weaker Real Incomes in regions like the Eurozone.
- Depletion of Strategic Reserves → Reduced Economic Buffers → Heightened Vulnerability to Supply Shocks → Potential for Sharp Price Volatility.
- Mounting Public Debt → Rising Benchmark Yields & Borrowing Costs → Increased Fiscal Pressure on Governments → Reduced Fiscal Space for Counter-Cyclical Policy.
- Persistent Inflationary Pressures → Central Banks Maintain Restrictive Monetary Policy → Higher Interest Rates → Potential Slowdown in Broader Economic Activity.
Fiscal Space: In economic terms, ‘fiscal space’ refers to a government’s capacity to increase spending or reduce taxes without endangering its financial health or market confidence. It’s built through prudent debt management and robust economic performance, allowing governments flexibility to respond to crises or stimulate growth. The IMF’s warning implies many nations have diminished this vital capacity.
| Metric | 2026 Forecast (Current) | 2026 Forecast (July) | 2027 Forecast (Current) |
|---|---|---|---|
| Global Growth (GDP %) | 3.1% | 3.0% | 3.4% |
| Global Inflation (CPI %) | 4.7% | 4.7% | 4.1% |
| Advanced Economies Public Debt (% GDP) | 108% (2025 proj.) | N/A | 115% (2031 proj.) |
Note: The slightly higher growth forecast for 2026 signals a positive short-term impact from AI investment. However, persistent inflation and rising public debt projections underscore structural challenges that could weigh on long-term macro-stability. The public debt figures highlight a growing concern over sovereign balance sheets, especially for advanced economies, as borrowing costs climb.
Navigating Inflationary Headwinds: A Policy Imperative
Despite the milder global economic slowdown, the IMF’s revised inflation forecasts underscore a persistent challenge for central banks worldwide. The blend of a substantial ‘demand shock’ from AI investment, coupled with elevated energy prices influenced by geopolitical events, is creating an environment where inflation may prove more stubborn than initially hoped. Policymakers face a delicate balancing act: maintaining sufficiently restrictive monetary policy to curb price pressures without stifling the nascent growth spurred by technological advancements. As central banks grapple with this complexity, preserving their independence becomes paramount to avoid politically motivated easing that could entrench inflation. Bloomberg Economics recently highlighted that market expectations for rate cuts might be overly optimistic given these underlying pressures.
Asymmetric Growth Across Global Markets
The latest IMF report vividly illustrates a deepening divergence in economic performance, marking a significant shift from previous periods where growth was more broadly distributed. This asymmetry is not merely cyclical but structural, with nations capable of catering to the burgeoning AI supply chain demonstrating remarkable resilience and growth, while energy-importing economies face intensifying fiscal and real income pressures. This bifurcation suggests that investors and businesses must adopt highly granular strategies, identifying specific national and sectoral exposures to either the AI boom or the persistent commodity price shocks. For a deeper dive into these macro trends, exploring global economic policies is crucial.
Global Slowdown: Balancing AI Exuberance with Fiscal Prudence
While the IMF’s updated outlook offers a glimmer of hope through AI-driven economic activity, the underlying message is one of cautious optimism tempered by stark warnings. The global economy is undeniably benefiting from a tech surge, yet this momentum is precarious, resting on rapidly diminishing buffers and facing significant fiscal and inflationary headwinds.
- Policymakers must prioritize fiscal consolidation and supply-chain diversification to enhance long-term resilience.
- The concentration of global growth in fewer economies signals increased vulnerability and necessitates targeted structural reforms in lagging regions.
- The risk of an AI bubble, where investment outpaces actual productivity gains, poses a tangible threat to financial market stability.
Can the global economy successfully navigate these converging challenges to achieve sustainable, inclusive growth?
### 📊 StockXpo Analyst’s View
Market Impact: The IMF’s assessment suggests a mixed bag for investor sentiment. While the AI narrative provides a strong bullish undertone, driving liquidity into specific tech plays, the overarching warning about limited resilience and rising public debt introduces significant macro-level uncertainty. This could lead to increased volatility, with markets susceptible to sudden corrections if AI productivity gains disappoint or fiscal concerns escalate, making selective stock market investment analysis critical.
Sector To Watch: The semiconductor and data center infrastructure sectors are clear beneficiaries of the AI investment boom, warranting continued attention. However, investors should also closely monitor the energy sector for potential price spikes as global reserves dwindle, and defensive sectors that typically fare better during periods of fiscal tightening and economic uncertainty, as Reuters reports. Further insights on market dynamics can be found on the StockXpo blog.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE ECONOMY
Nobel Prize in Economics: New Foundations for Macro-Stability Growth
Published: Monday, October 12, 2026 · 6:12 AM
Judy Shelton’s Treasury Role: A Controversial Shift in Economic Guidance
Published: Friday, October 9, 2026 · 7:52 AM


