
Published: Wednesday, September 30, 2026 · 9:07 PM | Updated: Wednesday, September 30, 2026 · 9:07 PM
📊 12 views


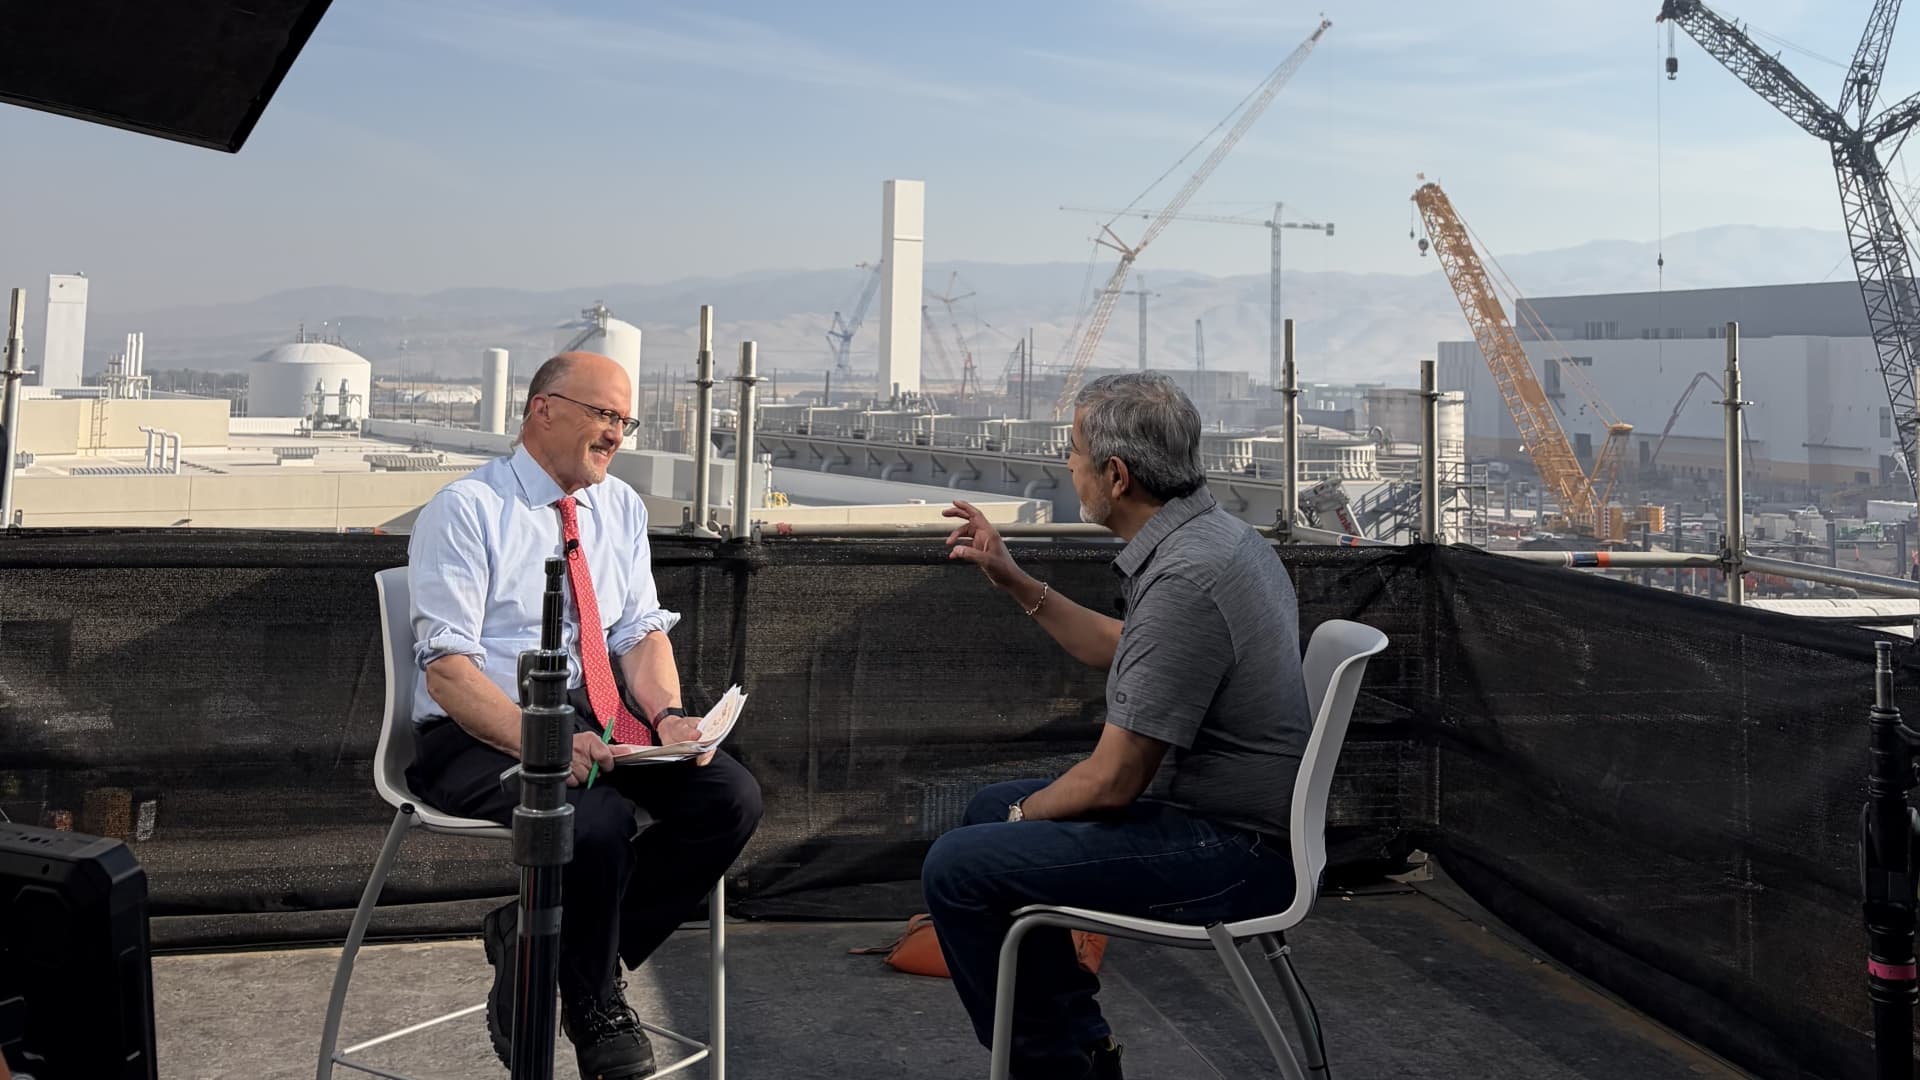
Micron Technology has delivered a stellar performance, exceeding analyst expectations for its fiscal 2026 fourth quarter and projecting continued strength into fiscal year 2027. This surge is largely propelled by unprecedented demand for its memory products, particularly High Bandwidth Memory (HBM), which is crucial for powering modern artificial intelligence workloads. The company’s robust guidance suggests that supply constraints in the memory market will persist, leading to favorable pricing dynamics.
💎 Strategic Investment & Portfolio Insights
- AI-Driven Demand Explosion. Surging demand for AI accelerators is creating a structural imbalance in the DRAM and NAND memory markets, driving up average selling prices.
- Strategic Customer Agreements (SCAs). Micron’s shift towards SCAs offers greater revenue visibility and aims to mitigate the historical boom-bust cycles of the memory industry.
- Capacity Expansion & Future Growth. Significant capital expenditures on new fabrication plants signal confidence in sustained demand and provide a pathway for future revenue growth, supported by customer commitments.
Micron’s Record Quarter Driven by AI Memory Needs
Micron reported a fiscal 2026 fourth quarter revenue of $54.23 billion, a remarkable 379% year-over-year increase, surpassing consensus estimates. Adjusted EPS surged by 1,002% to $33.42. This exceptional performance is a direct result of the tight supply conditions and escalating demand for memory products integral to AI applications. The company highlighted that the structural gap between DRAM supply and demand growth rates is widening, with expectations for calendar 2027 and 2028 to be even tighter than the current year. CEO Sanjay Mehrotra stated that approximately 75% of Micron’s projected output for 2027 is already committed, with customers actively discussing allocations for 2028. This indicates a fundamental shift in demand patterns, moving beyond traditional cyclicality.
The memory market is broadly divided into NAND (storage) and DRAM (working memory). A specialized form of DRAM, High Bandwidth Memory (HBM), is a critical component for AI accelerators, enabling efficient data flow for complex computations. As AI systems become more sophisticated and deployed at scale, the need for higher memory bandwidth and capacity is becoming paramount. This has led to a situation where industry demand consistently outstrips supply, a condition Micron anticipates will continue for the foreseeable future.
- Revenue for fiscal Q4 2026 reached $54.23 billion, a 379% year-over-year increase.
- Adjusted EPS jumped to $33.42, a 1,002% rise from the previous year.
- Management forecasts fiscal year 2027 to experience sequential revenue growth each quarter.
Micron is actively addressing this demand by increasing capital expenditures to expand its manufacturing capacity. While such expansions carry inherent risks of overbuilding in the industry, the company’s confidence is bolstered by the revenue visibility provided by its Strategic Customer Agreements (SCAs). These agreements, which have grown to 26 from 16 in the prior quarter, aim to stabilize pricing and revenue streams, moving away from the historical volatility of the memory market. Many of these SCAs are extending beyond 2030, underscoring long-term customer commitment.
Furthermore, Micron is poised for significant capital returns to shareholders. With free cash flow of $33 billion in the recent quarter and an additional $128 billion projected for the upcoming fiscal year, a substantial share repurchase program is anticipated. Restrictions related to CHIPS Act funding are set to ease in December, potentially unlocking substantial buyback capacity, comparable to industry leaders. This financial flexibility, combined with strong operational performance, positions Micron favorably for sustained investor returns and portfolio growth.
Why This AI Memory Boom Matters
The current dynamics suggest a departure from typical memory market cycles. The foundational changes in demand driven by the AI revolution are creating a ‘higher for longer’ scenario for memory prices and demand. Micron’s proactive strategy with SCAs and capacity expansion aims to capitalize on this structural shift. This development could lead to more predictable earnings and enhanced shareholder value, moving the company beyond its traditional cyclical reputation. Investors should monitor the execution of its expansion plans and the continued signing of SCAs.
For CIOs, the implication is clear: the long-term demand for advanced memory solutions, particularly HBM, is not a temporary surge but a fundamental shift driven by AI’s pervasive integration across industries. Strategic allocation towards companies like Micron, with clear visibility into future demand and supply-side management, becomes paramount for alpha generation and capital preservation.
| Metric | Value | Significance |
|---|---|---|
| FY26 Q4 Revenue | $54.23 Billion (+379% YoY) | Demonstrates exceptional top-line growth driven by market demand. |
| FY26 Q4 Adj. EPS | $33.42 (+1,002% YoY) | Indicates significant profitability expansion due to pricing power and efficiency. |
| FY27 Projected FCF | $128 Billion | Highlights substantial cash generation capacity for shareholder returns and reinvestment. |
Micron’s Expanding Revenue Horizon
Micron’s forward-looking guidance remains exceptionally strong, projecting revenue of $61.5 billion (±$1.5 billion) for the fiscal 2027 first quarter, outperforming consensus estimates. The company anticipates sequential revenue growth in every quarter of fiscal year 2027. While gross margins are expected to see a slight dip to approximately 86.25% in Q1 fiscal 2027 from 87% in Q4 fiscal 2026, this is attributed to increased employee compensation rather than softening average selling prices, which is a crucial distinction. Management indicated that fiscal Q1 will likely represent the floor for gross margins for the year. Adjusted EPS for the current quarter is forecast to be $38.15 (±$1), exceeding consensus expectations.
Micron’s Competitive Edge in AI Memory
In the competitive landscape, Micron faces formidable rivals in Samsung and SK Hynix. However, the current market conditions, particularly the insatiable demand for AI-specific memory like HBM, appear to be creating a supply-demand imbalance that benefits all major players capable of scaling production. Micron’s ability to secure SCAs and commit to significant capacity expansions positions it to capture a substantial share of this growing market, potentially differentiating it through secured customer relationships and advanced manufacturing capabilities. As the broader market analysis suggests, the semiconductor industry, particularly memory, is entering a phase of sustained demand growth fueled by AI advancements.
Micron’s AI Momentum Continues
The sustained demand for AI-driven memory solutions positions Micron for continued financial outperformance. The company’s strategic initiatives, coupled with a fundamentally rebalanced supply-demand dynamic, suggest a new era of growth characterized by higher profitability and reduced cyclicality. The potential for a significant share buyback program further enhances the investment thesis.
- Micron’s stock has surged approximately 275% year-to-date, reflecting strong investor confidence.
- The company is actively expanding its manufacturing capacity to meet future demand.
- Strategic customer agreements are enhancing revenue predictability and pricing power.
Will the current trajectory of HBM demand and Micron’s strategic execution lead to a sustained period of elevated profitability, fundamentally altering the perception of memory stocks?
📊 StockXpo Analyst’s View
Market Impact: The robust performance and optimistic guidance from Micron significantly bolster investor sentiment in the semiconductor sector, particularly for companies involved in AI infrastructure. This could lead to increased liquidity and a rotation of capital into technology-related assets, influencing broader market trends.
Sector To Watch: The memory chip segment, driven by AI accelerators, is the immediate beneficiary. Beyond this, industries reliant on high-performance computing, cloud services, and advanced data analytics will likely see increased investment and innovation, indirectly benefiting from the advancements in memory technology. Companies involved in AI hardware design and AI software development should also be monitored closely.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE INVESTMENT NEWS
Costco’s Membership Momentum: A Bullish Signal for Portfolios
Published: Thursday, September 24, 2026 · 10:26 PM
Cat Owners’ Spending Surge: A Portfolio Bullish Signal
Published: Thursday, September 24, 2026 · 12:19 PM


