
Published: Friday, November 13, 2026 · 9:39 AM | Updated: Friday, November 13, 2026 · 9:39 AM
📊 10 views



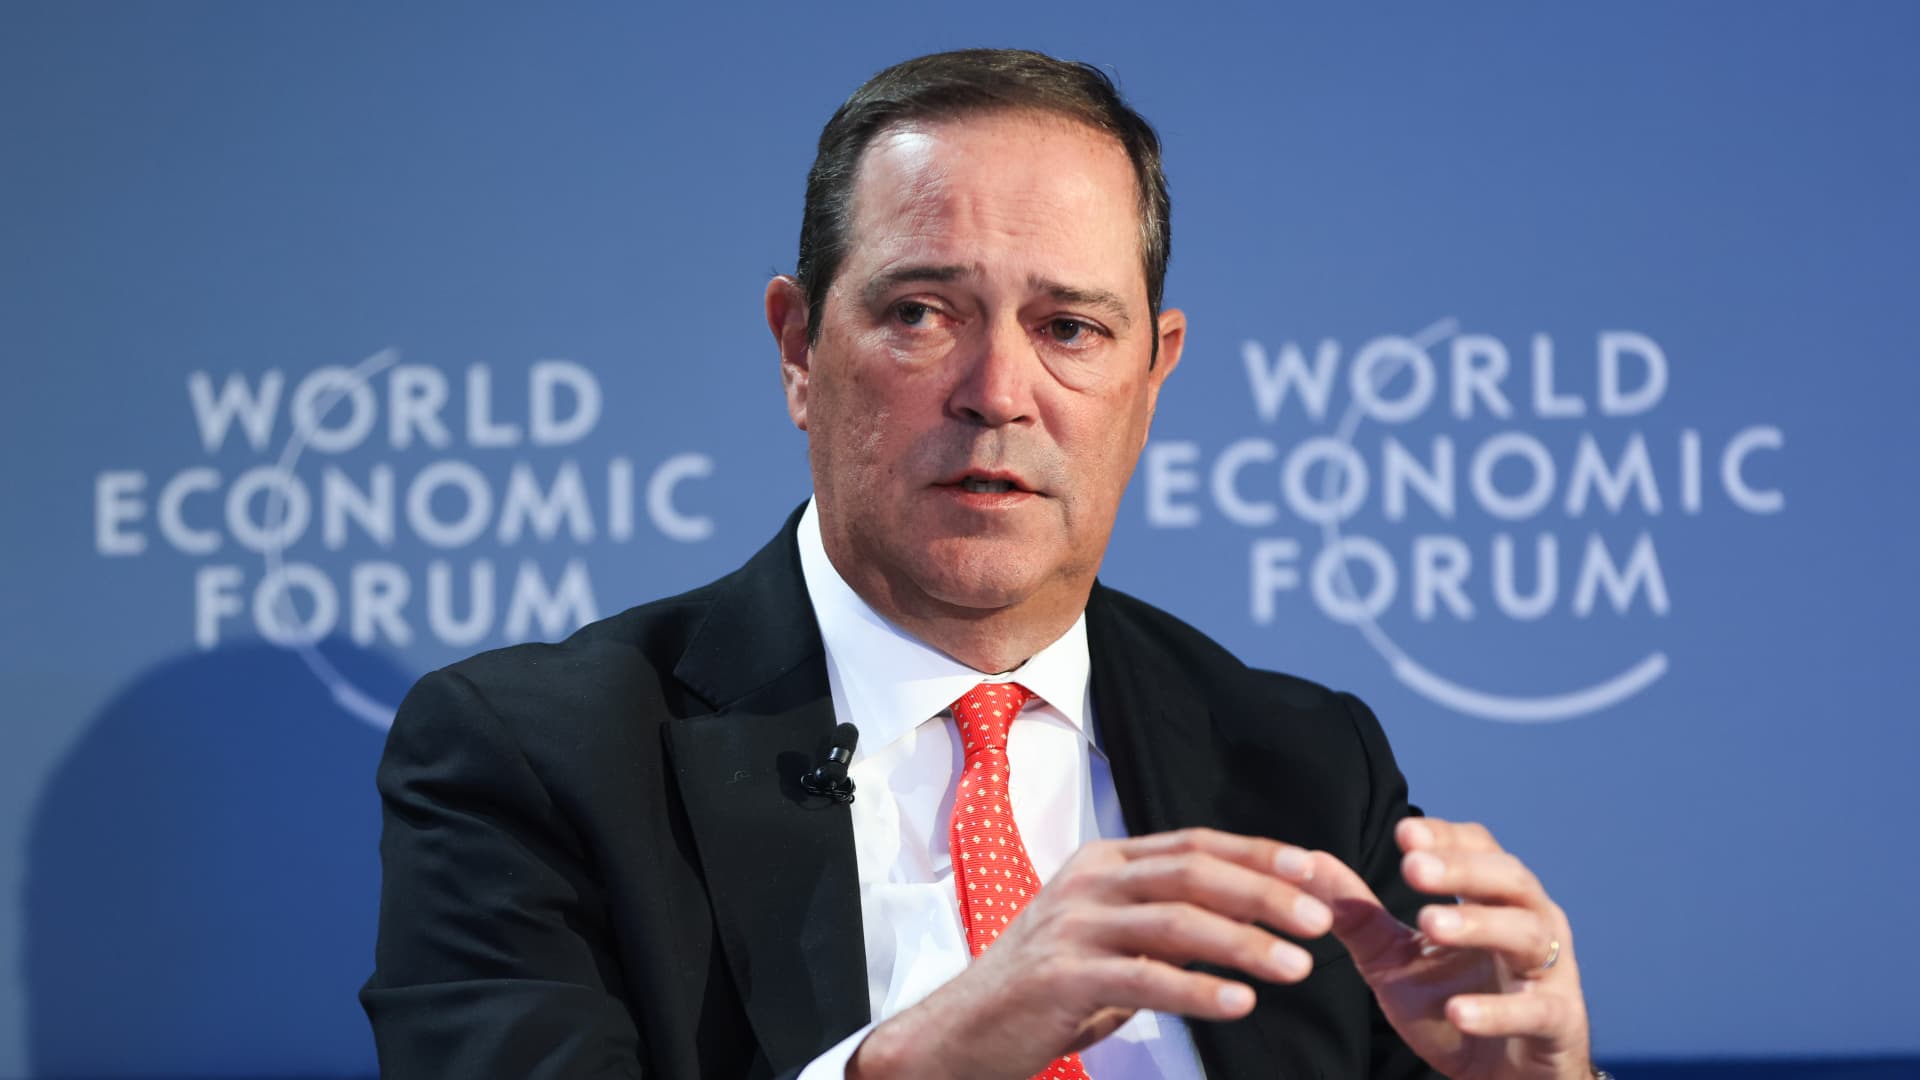
Cisco Systems Inc. (CSCO) reported robust fiscal first-quarter results that surpassed analyst expectations, driven by strong demand for its networking gear. The company significantly elevated its guidance for AI infrastructure revenue, signaling a pivotal shift in its growth trajectory and validating its strategic focus on the burgeoning artificial intelligence sector.
💎 Strategic Investment & Portfolio Insights
- AI Infrastructure Momentum. Cisco’s projected doubling of AI infrastructure revenue to $9 billion underscores its increasing relevance in the generative AI buildout, positioning it as a critical enabler for hyperscalers and enterprises.
- Strong Financial Outperformance. Beating both EPS and revenue estimates by a notable margin, alongside an upward revision of future guidance, suggests operational efficiency and resilient demand for core networking and emerging AI solutions.
- Revaluation Potential. The market’s positive reaction and CSCO’s year-to-date outperformance against the Nasdaq indicate a potential re-rating as investors acknowledge its enhanced role in the AI economy, justifying a closer look at its intrinsic value.
Cisco shares climbed in extended trading following the announcement of its fiscal first-quarter performance, which saw adjusted earnings per share reach $1.40 against an LSEG consensus estimate of $1.33. Revenue also comfortably exceeded projections, hitting $18.5 billion compared to the anticipated $18.1 billion, representing a substantial 24% increase from $14.88 billion in the prior year. This financial strength points to robust execution amidst a complex macroeconomic environment, solidifying Cisco’s position as a foundational technology provider. The company’s net income soared to $4.6 billion, or $1.14 per share, significantly up from $2.9 billion, or 72 cents per share, a year earlier.
A key highlight was Cisco’s revised outlook for its AI infrastructure revenue, now expected to hit $9 billion this fiscal year. This figure more than doubles its fiscal 2026 projection, signaling an aggressive push into a sector it previously lagged. CEO Chuck Robbins emphasized that organizations are increasingly relying on Cisco’s technology and expertise to scale, secure, and optimize their environments for the ‘agentic AI era,’ as reported by the company’s latest business insights. This strategic shift is critical for Cisco, which aims to carve out a significant presence in the artificial intelligence development, having notably missed out on the initial waves of the generative AI boom. The stock’s roughly 35% gain year-to-date, far surpassing the Nasdaq’s 9% rise, reflects growing investor confidence in this pivot. Looking ahead, Cisco’s guidance for the fiscal second quarter anticipates revenue between $18 billion and $18.2 billion, above analyst expectations of $17.88 billion, with adjusted earnings per share projected at $1.34 to $1.36, comfortably beating the $1.23 average estimate.
This strong earnings report and the substantial upgrade in Cisco AI revenue forecasts have immediate implications for portfolio positioning. Enhanced earnings visibility and an accelerated entry into high-growth AI infrastructure markets will likely lead to asset revaluation, pushing CSCO into a more growth-oriented allocation within diversified portfolios. This strategic rebalancing could involve a higher weighting for technology segments demonstrating tangible AI leverage, potentially reducing exposure to more traditional, slower-growth segments. For investors seeking enhanced portfolio growth through strategic capital allocation decisions, Cisco’s performance offers a compelling case for re-evaluation.
“Cisco’s decisive move into AI infrastructure is not merely an incremental adjustment; it’s a re-foundational play. For long-term capital preservation and alpha generation, investors should view this as a potential catalyst, moving CSCO from a stable cash cow to a hybrid growth-and-value proposition, particularly given its crucial role in the underlying digital plumbing of AI.”
Cisco’s recent performance highlights demonstrate its consistent ability to exceed market expectations across key financial metrics:
| Metric | Reported (Q1 FY26) | LSEG Consensus | Significance |
|---|---|---|---|
| Adjusted EPS | $1.40 | $1.33 | Exceeding profit forecasts indicates strong operational efficiency. |
| Revenue | $18.5 Billion | $18.1 Billion | Revenue beat reflects robust demand across Cisco’s product portfolio. |
| Net Income | $4.6 Billion | Not explicitly provided, up from $2.9B YoY | Substantial year-over-year growth signals improving profitability. |
| FY26 AI Revenue Projection | $9 Billion | Double FY25 ($4.5B previously) | Pivotal growth driver, positioning Cisco for the AI economy. |
Cisco Risk-Reward Matrix: Navigating AI’s Promise and Peril
Investing in Cisco now presents a nuanced risk-reward profile, largely driven by its renewed focus on AI. On the reward side, the company’s established market leadership in networking hardware provides a stable foundation, while its aggressive push into AI infrastructure offers significant upside potential. The projected doubling of AI revenue is a strong indicator of future growth, catering to the insatiable demand from hyperscalers. This strategic pivot could unlock a higher valuation multiple, particularly as its AI solutions become more integrated into enterprise and cloud architectures. For a broader perspective on market dynamics, explore recent market analysis and stock trends.
However, risks remain. The AI infrastructure market is highly competitive, with established players and nimble startups vying for market share. Execution risk associated with rapidly scaling AI-specific product development and deployment cannot be overlooked. Furthermore, any slowdown in hyperscaler capital expenditures or a shift in technological standards could impact Cisco’s AI growth trajectory. Geopolitical tensions and supply chain vulnerabilities, while less directly tied to AI, continue to pose broader operational risks for a global hardware provider.
Cisco Competitive Benchmarking: A Fight for AI Dominance
Cisco operates in a highly competitive landscape, particularly as it expands its footprint in AI infrastructure. While it has traditionally dominated enterprise networking, its AI ambitions place it in direct competition with specialized AI hardware providers like Nvidia (for GPUs) and network equipment rivals like Arista Networks, which has a strong presence in high-performance data center networking. Cisco’s advantage lies in its comprehensive portfolio, offering integrated solutions across networking, security, and now AI-optimized infrastructure, a holistic approach many competitors lack. Its extensive installed base and customer relationships provide a robust foundation for cross-selling AI-centric upgrades. However, it must demonstrate superior innovation and agility to fend off competitors who may have a first-mover advantage or more focused R&D in specific AI domains. The company’s ability to secure large contracts with hyperscalers, as indicated by the significant AI revenue forecast, will be a critical benchmark of its success against these formidable rivals.
Cisco’s AI Imperative: Reshaping the Networking Narrative
Cisco’s impressive Q1 performance and the bullish outlook on its artificial intelligence infrastructure revenue marks a critical juncture for the networking giant. The company is actively shedding its image as a legacy hardware provider, aggressively positioning itself at the core of the digital transformation driven by AI. This pivot is already yielding tangible results, reflected in both its financial metrics and market valuation.
- Cisco is successfully re-establishing its relevance in high-growth technology segments.
- The doubling of AI revenue forecasts provides strong validation for its strategic investments and product development.
- Enhanced visibility into future earnings and market positioning supports a more optimistic long-term growth outlook.
Can Cisco maintain this accelerated momentum and solidify its indispensable role in the AI-driven data center?
📊 StockXpo Analyst’s View
Market Impact: Cisco’s strong earnings and AI guidance are likely to bolster confidence in the broader technology sector, particularly for companies enabling AI infrastructure. This signals healthy enterprise spending and a sustained investment cycle in generative AI capabilities. It could drive liquidity towards established tech giants demonstrating clear AI monetization strategies, potentially drawing capital away from more speculative AI ventures.
Sector To Watch: Beyond pure-play AI chipmakers, the networking and data center infrastructure sector stands to benefit significantly. Companies providing high-bandwidth switches, optical components, and integrated security solutions vital for AI workloads will likely see increased investor attention. This includes not just direct competitors but also suppliers within Cisco’s ecosystem who are critical to scaling AI deployments.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE INVESTMENT NEWS
Nebius Shares Plunge 10%: A Warning on Cloud Capex & Outlook
Published: Thursday, November 12, 2026 · 8:27 AM
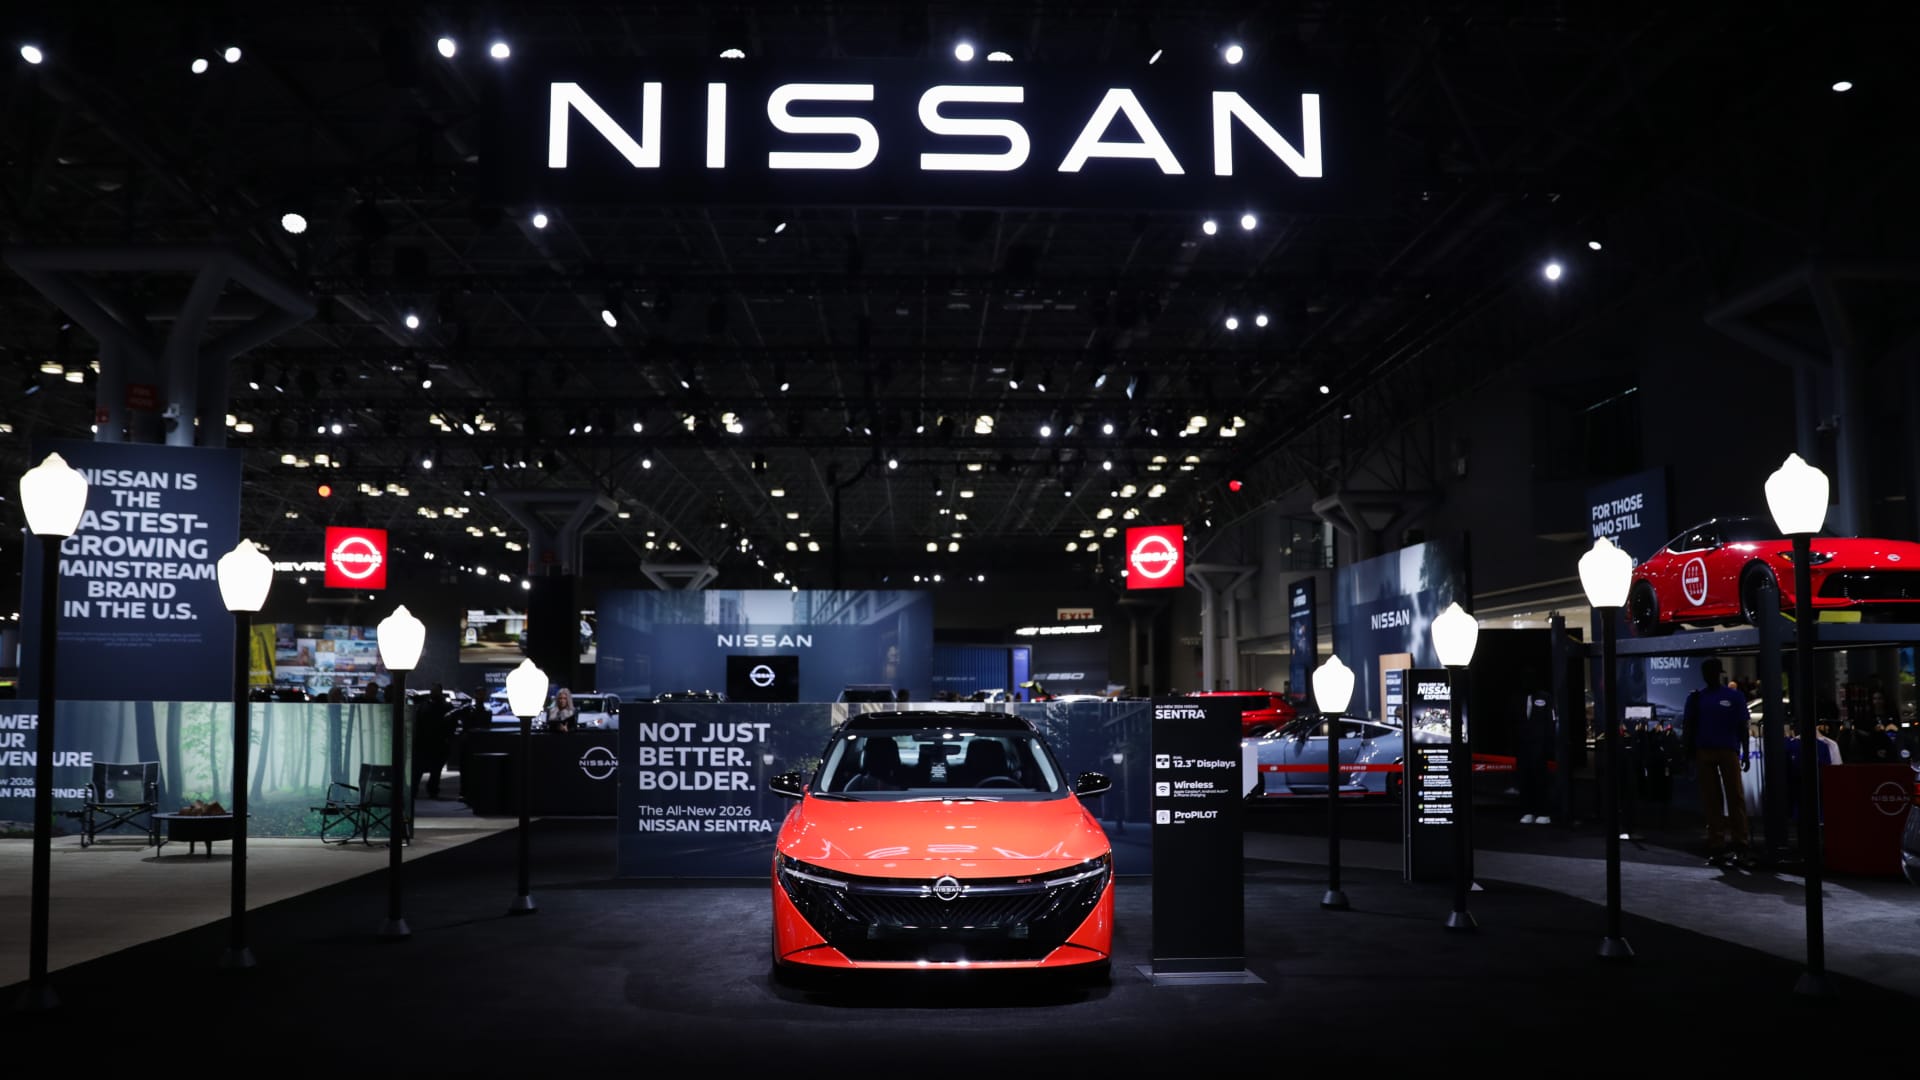
Nissan’s fight: Strategic Counterattack Amidst Chinese EV Alpha Pursuit
Published: Wednesday, November 11, 2026 · 5:56 AM


