
Published: Thursday, November 12, 2026 · 8:27 AM | Updated: Thursday, November 12, 2026 · 8:27 AM
📊 9 views



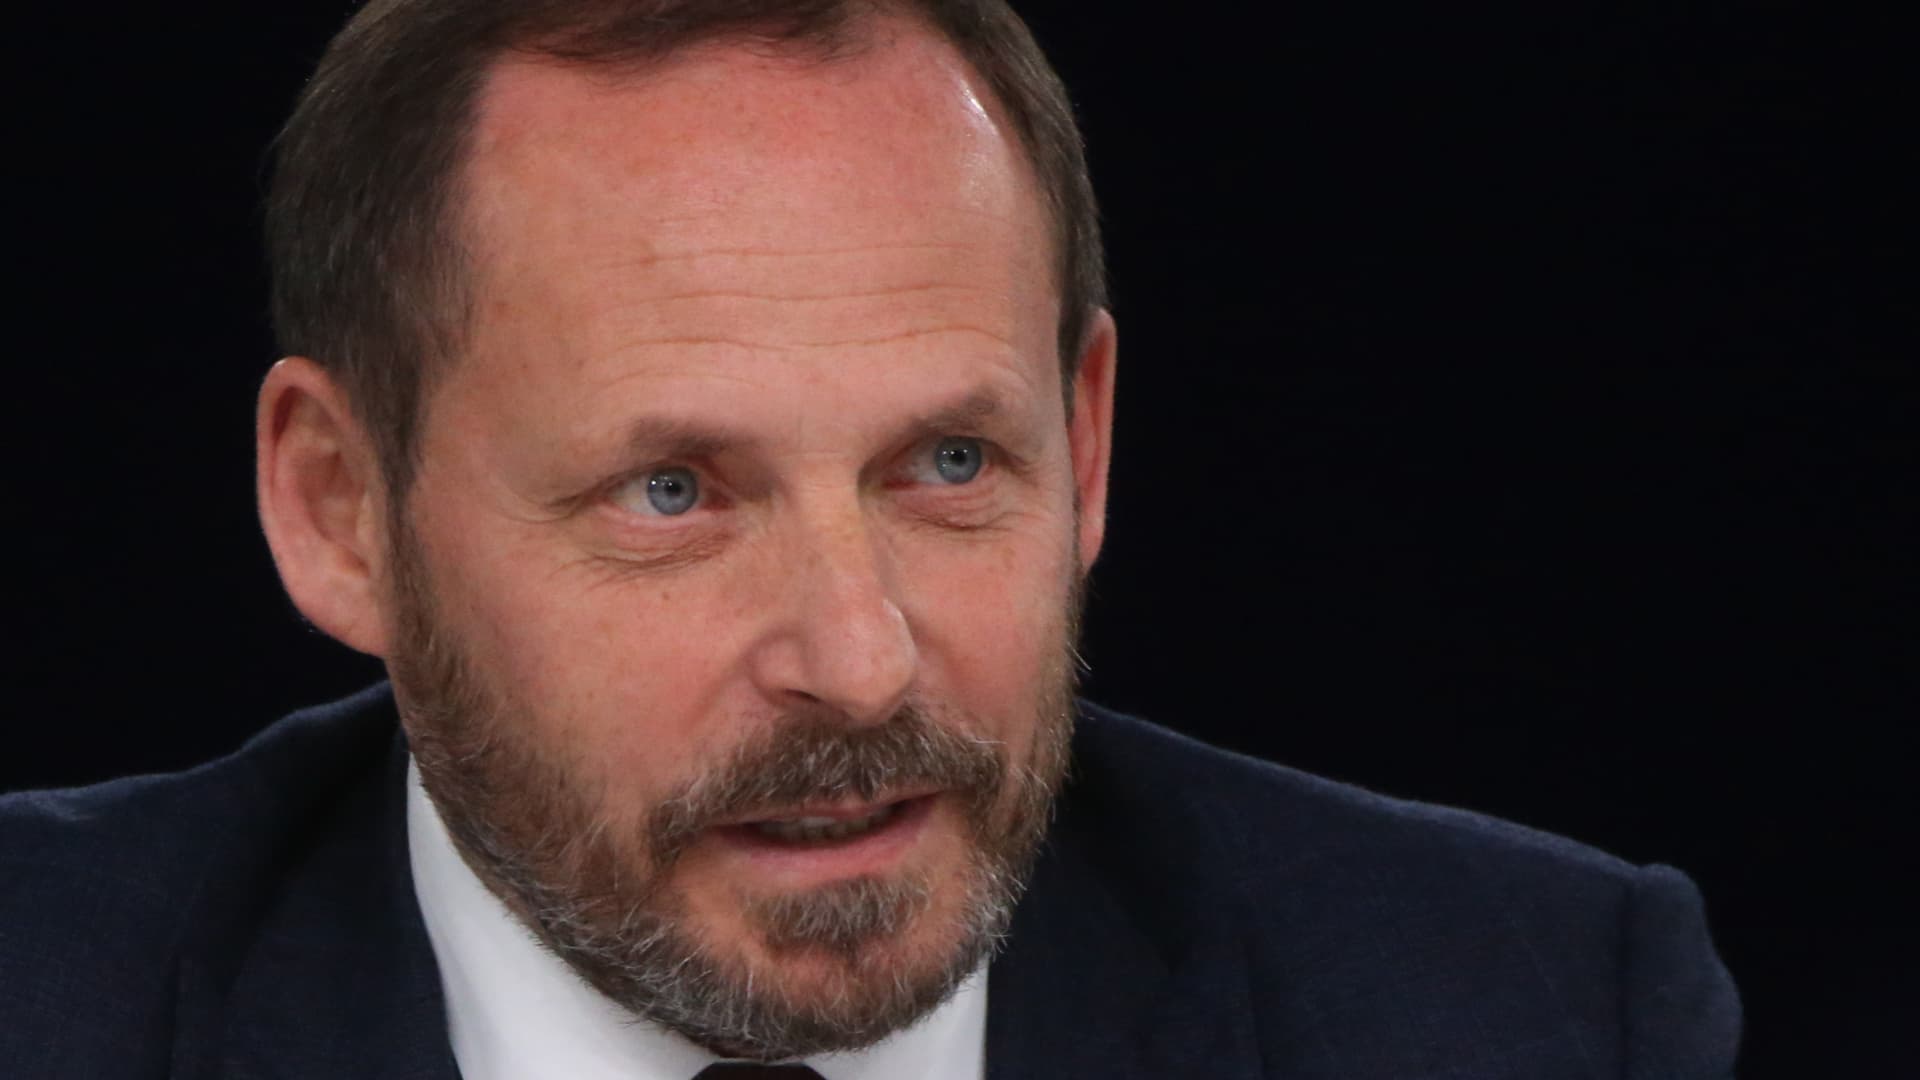
Nebius shares plummeted 10% on Thursday, reacting to significantly elevated capital expenditure forecasts for 2026 and 2027, alongside a cautious future revenue outlook. This sharp decline arrived despite the neocloud company reporting third-quarter revenue that surpassed analyst expectations, highlighting investor sensitivity to future spending commitments in the high-growth AI infrastructure sector.
💎 Strategic Investment & Portfolio Insights
- Rising Capex Risks. Nebius’ substantial increase in capital expenditure guidance for 2026 and 2027 signals aggressive build-out, but raises concerns about future free cash flow and potential investor dilution if growth does not materialize as planned.
- Conservative Outlook Weighs. Despite beating Q3 revenue estimates, the CEO’s tempered fiscal year 2026 revenue guidance and cautious 2027 outlook indicates a possible deceleration in the hyper-growth phase or a more realistic assessment of market saturation.
- Sector-Wide Volatility Alert. The market’s reaction to Nebius underscores the inherent volatility and rapid re-evaluation risks within the broader neocloud and AI infrastructure space, prompting a closer look at valuations and execution capabilities across the sector.
Nebius experienced a significant sell-off after revealing its third-quarter financial results. While the company posted a robust revenue figure of $980.8 million, comfortably beating LSEG consensus estimates of $907.5 million, and improved its net loss to $37.5 million (13 cents per share) from $119.6 million (50 cents per share) a year prior, the market’s focus quickly shifted to future guidance. The implications of such aggressive capital allocation for a company’s financial health and valuation are significant, warranting deeper educational market insights.
The core of the investor concern lies in Nebius’ projected capital expenditures. For fiscal year 2026, the company now expects capex to hit $27 billion, substantially higher than its previous guidance of $20 billion to $25 billion and FactSet’s expectation of $23.85 billion. This trend continues into fiscal year 2027, with anticipated capex ranging from $40 billion to $45 billion, far exceeding FactSet’s $28.77 billion forecast. This ambitious spending plan, aimed at building out its neocloud infrastructure, implies significant upfront investment for potentially delayed returns.
CEO Arkady Volozh conveyed a conservative approach, projecting FY2026 revenue at the lower end of its $3 billion to $3.4 billion range, below FactSet’s $3.35 billion. The initial FY2027 revenue outlook of $12 billion to $13 billion, while substantial, was also framed by management as a ‘conservative approach to the pace of our build-out’. Investors closely watch global market developments, which can impact sentiment for such ambitious forecasts.
The broader neocloud market has seen considerable volatility. Just prior to Nebius’ announcement, competitors like CoreWeave and IREN had reported stronger-than-expected financials, leading to a temporary rally in the sector. However, Nebius’ updated outlook triggered a premarket sell-off across these stocks, indicating a fragile sentiment regarding the sustainability of the AI infrastructure boom. This underscores the need for continuous market trend analysis. CoreWeave, for instance, had recently seen its bond yields spike, emphasizing investor scrutiny over debt levels and financing strategies. Nebius itself secured $5.75 billion in debt financing during the quarter, underscoring the capital-intensive nature of its growth.
Macroeconomic factors and sector-specific challenges further complicate the picture. Recent U.S. ballot initiatives restricting data center development signal potential regulatory headwinds. Moreover, internal issues at Nvidia, a crucial partner and investor in Nebius (holding approximately $329 million in Nebius shares as of June), could introduce an additional layer of uncertainty for the ecosystem that has propelled the neocloud market.
- Q3 Revenue: $980.8 million (beat $907.5 million estimate).
- Net Loss: $37.5 million (13 cents/share), improved from $119.6 million (50 cents/share) a year prior.
Portfolio Positioning Effect: The High-Stakes Gamble on AI Infrastructure
Increased Capital Expenditure Forecasts → Heightened Debt & Execution Risk → Re-evaluation of Growth Premiums for AI Infrastructure Companies → Potential Portfolio De-risking from High-Beta Cloud Stocks.
‘The aggressive capex guidance from Nebius, despite strong Q3 revenue, is a critical signal for the entire AI infrastructure landscape. It suggests that while demand is robust, the cost of scaling to meet that demand is escalating, potentially compressing future margins and extending payback periods for these investments. Long-term investors must scrutinize free cash flow generation and debt burdens far more closely.’ – StockXpo CIO Insights.
Understanding Nebius’ performance requires a close look at its recent financials against consensus and revised outlooks:
| Metric | Q3 Actual (2026) | LSEG/FactSet Consensus | Significance |
|---|---|---|---|
| Revenue | $980.8 million | $907.5 million | Strong beat indicates robust current demand. |
| Loss per share | ($0.13) | ($0.69) | Improved profitability year-over-year. |
| FY2026 Revenue Guidance | $3.0 – $3.4 billion (low end expected) | $3.35 billion | Conservative outlook, slightly below consensus midpoint. |
| FY2026 Capex Guidance | $27 billion | $23.85 billion | Significantly higher, indicating intense investment phase. |
| FY2027 Capex Guidance | $40 – $45 billion | $28.77 billion | Massively increased, a major driver of market concern. |
The discrepancy between Nebius’ ambitious capital expenditure plans and the relatively conservative revenue guidance for the coming years points to a widening investment gap that could pressure margins and valuation multiples.
Nebius Competitive Benchmarking: Navigating the Neocloud Race
The neocloud market, central to the AI buildout, is intensely competitive. Nebius operates alongside key players like CoreWeave and IREN, all racing to deploy substantial GPU-accelerated infrastructure. While CoreWeave recently assured investors about managing its debt, Nebius’ aggressive capex plans stand out. This heavy investment strategy is a double-edged sword: it could secure market leadership and long-term capacity, but also entails significant financial strain and execution risk. The reaction to Nebius’ guidance suggests investors are becoming increasingly discerning, distinguishing between companies based on capital efficiency and realistic growth projections rather than just raw revenue growth. The political landscape, with increasing local opposition to data center development, further complicates the competitive field, adding a layer of regulatory and social acceptance risk to expansion plans.
Nebius Risk-Reward Matrix: High Stakes in AI Infrastructure
For investors, the current situation with Nebius presents a complex risk-reward profile. The reward lies in tapping into the booming demand for AI compute, which Nebius’ massive infrastructure build-out aims to capture. If AI adoption continues its exponential trajectory, these investments could yield substantial long-term returns, justifying the high upfront costs. However, the risks are considerable: the elevated capex could lead to continued operating losses, increased debt servicing costs, and potential shareholder dilution if future capital raises are equity-based. There’s also the risk of overbuilding capacity relative to demand, or competitive pressures eroding pricing power. The reported issues at key partner Nvidia add another layer of uncertainty, given its strategic importance and investment in Nebius. Investors must weigh the potential for alpha generation against these tangible execution and financial risks, particularly when considering the broader portfolio strategy for high-growth tech exposures.
Navigating Nebius’ Future: Growth Ambition vs. Capital Intensity
The market’s sharp reaction to Nebius’ updated guidance underscores a fundamental tension within the rapidly expanding AI infrastructure sector: the immense capital required to fuel future growth. While Nebius demonstrates strong current demand, its ambitious capex program casts a long shadow over near-term profitability and free cash flow generation.
- Capital Intensity: The significantly raised capex targets highlight the company’s aggressive strategy to scale, but signal potential for prolonged cash burn.
- Valuation Reassessment: Investors are repricing Nebius to account for higher future investment and a conservative growth outlook, signaling a shift from pure revenue growth narratives.
- Market Sensitivity: The stock’s fall, despite a revenue beat, shows investor wariness towards execution risk and financial sustainability in a competitive, capital-intensive industry.
Can Nebius’ long-term vision justify its immense capital outlay amidst increasing market scrutiny?
📊 StockXpo Analyst’s View
Market Impact: The Nebius sell-off is likely to reverberate through the entire neocloud sector, prompting a re-evaluation of valuation multiples for companies engaged in capital-intensive AI infrastructure build-outs. Investor sentiment may shift towards a more critical assessment of free cash flow and debt metrics, potentially increasing volatility for growth stocks heavily reliant on future capital.
Sector To Watch: The broader AI infrastructure and data center sector, including GPU manufacturers and specialized cloud providers, will be under intense scrutiny. This event emphasizes the need for companies in this space to articulate clear paths to profitability and capital efficiency, rather than solely focusing on revenue growth. We anticipate a period of greater discernment by investors, possibly leading to a flight to quality among AI-related plays.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE INVESTMENT NEWS
Nissan’s fight: Strategic Counterattack Amidst Chinese EV Alpha Pursuit
Published: Wednesday, November 11, 2026 · 5:56 AM
SoftBank’s $7 Billion Loss: A Portfolio Warning Amidst Tech Selloff
Published: Tuesday, November 10, 2026 · 2:14 AM

