Published: Wednesday, November 11, 2026 · 9:59 AM | Updated: Wednesday, November 11, 2026 · 9:59 AM
📊 12 views



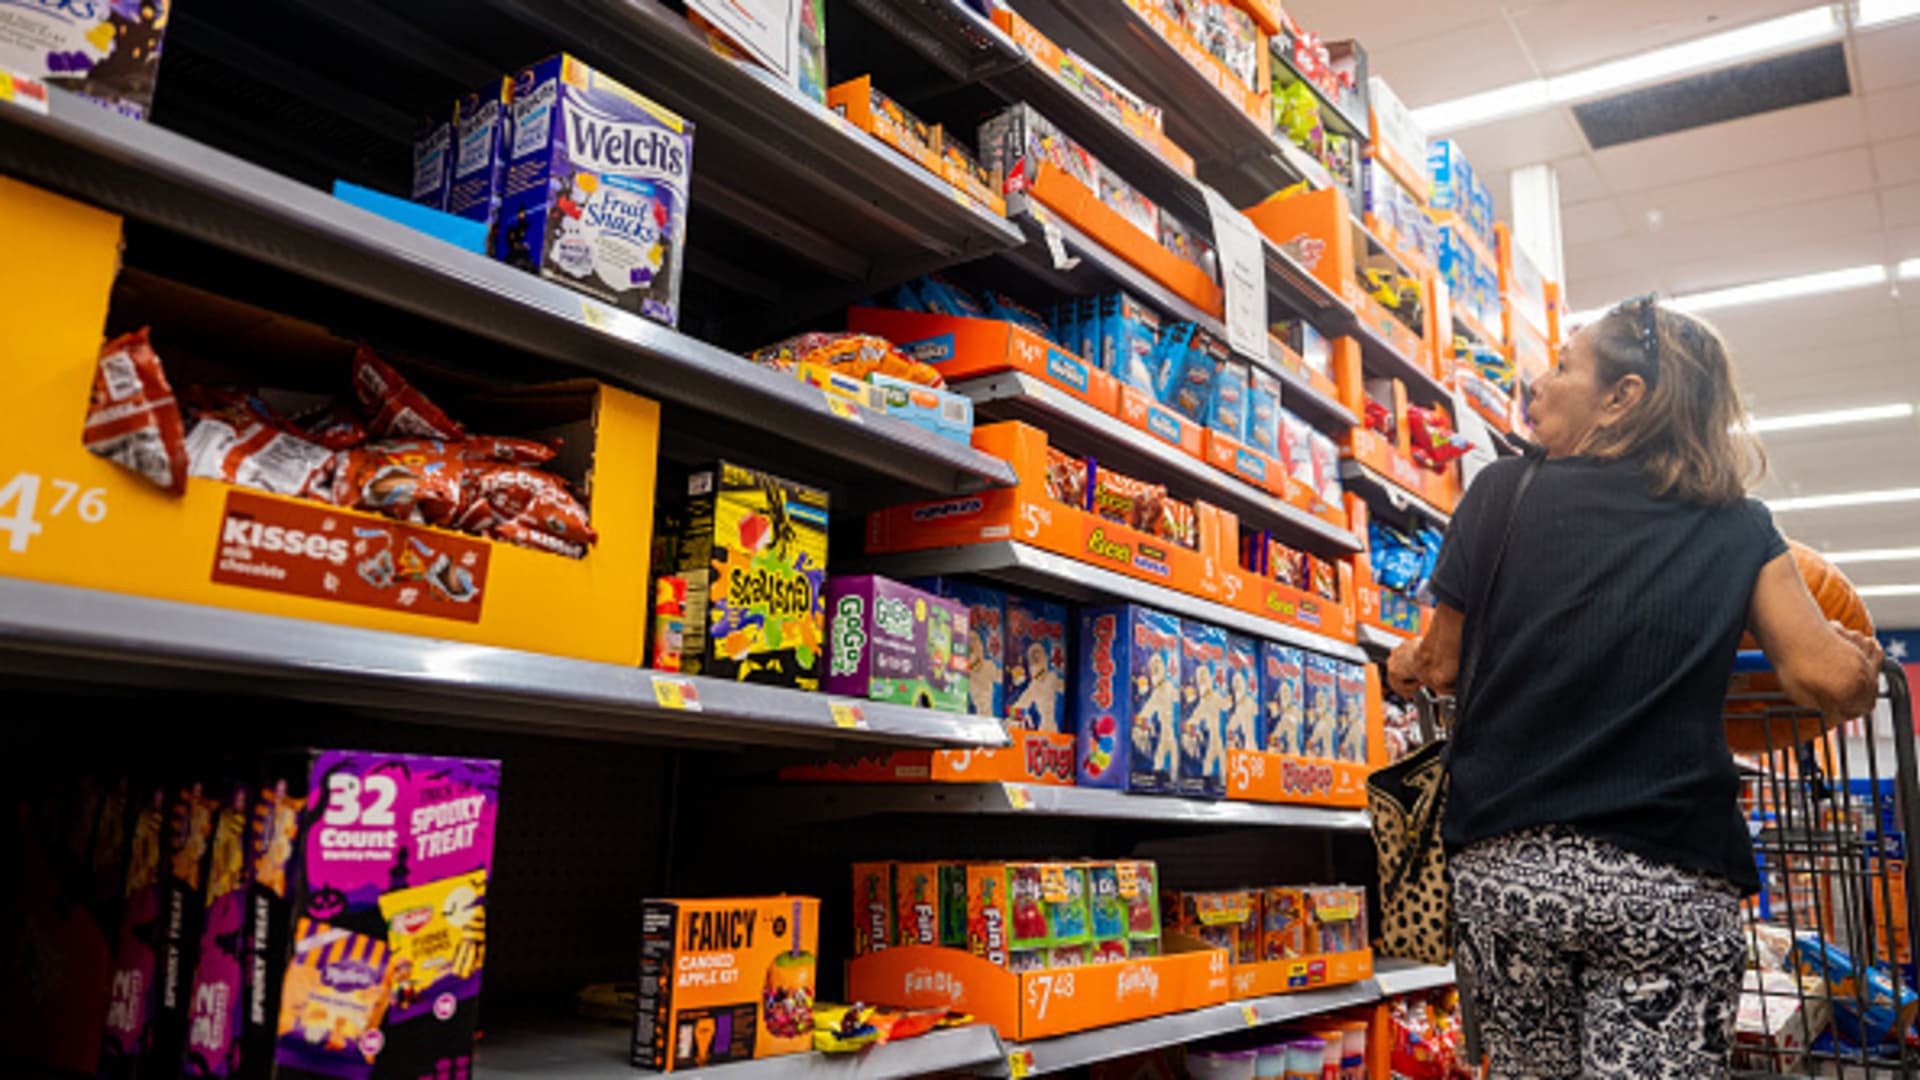
Evidence of mounting consumer strain is increasingly apparent across the U.S. economy as retail sales registered their weakest growth in nearly a year. This deceleration in spending, primarily driven by persistent high prices, signals a critical juncture for macro-stability and could influence global economic outlooks, particularly concerning inflation and central bank policies.
📊 Macro-Economic Strategic Insights
- Retail Slowdown: U.S. retail spending in October increased by a mere 0.2% month-over-month, the slowest pace observed since November 2025.
- Price Sensitivity: Consumers are demonstrating increased selectivity, timing purchases around promotions to manage budgets amidst elevated inflation.
- Sector Divergence: While electronics and appliances saw robust growth (9.3% YoY) due to price hikes, sectors like home furnishings (down 2.6% YoY) and leisure items (down 0.4% YoY) struggled, reflecting impacts from housing market conditions and discretionary spending adjustments.
The latest CNBC/NRF Retail Monitor indicates a significant cooling in consumer spending, with October’s total retail sales rising just 0.2% from the prior month to $561.7 billion. This marks the slowest monthly growth rate in almost a year, signaling that American households are grappling with sustained inflationary pressures. Core retail spending, excluding restaurant expenditures, similarly saw a modest 0.3% increase month-over-month to $454.2 billion, underscoring a broad-based shift in purchasing habits.
The National Retail Federation (NRF) attributes the prevention of an even sharper decline to a strong Halloween season and early holiday promotions, suggesting consumers are actively seeking value rather than engaging in unfettered discretionary spending. Matthew Shay, CEO of the NRF, highlighted that ‘Households are managing budgets carefully, timing purchases around special offers and sales events in order to stretch their dollars.’ This sentiment aligns with broader observations of how inflation affects consumer behavior, pushing demand towards necessity or heavily discounted goods.
The impact of high prices and rising interest rates is not uniform across all sectors. Technology-driven categories like electronics and appliances defied the overall slowdown, recording a robust 9.3% year-over-year increase. This surge is largely attributed to price increases by manufacturers like Apple and Microsoft, driven by soaring memory chip costs fueled by the artificial intelligence boom. Conversely, interest-rate sensitive sectors faced considerable headwinds. Furniture and home furnishings sales dropped 0.2% in October and were down 2.6% over the last 12 months, directly reflecting the ongoing freeze in the housing market as mortgage rates remain elevated. Similarly, spending on leisure items, including sporting goods, music, and bookstores, contracted by 0.4% year-over-year. These divergent trends underscore a bifurcated consumer landscape where essential or technology-driven spending, often influenced by supply-side costs, holds up better than discretionary purchases tied to housing and leisure. For deeper analysis on these evolving dynamics, explore our comprehensive economic policy insights.
- Shrinking Discretionary Spend: Consumers are increasingly prioritizing essential purchases or strategically timing non-essential buys, indicating a retreat from broad discretionary spending.
- Tech Sector Resilience: Price hikes driven by component costs (e.g., AI-related chips) are supporting revenue growth in electronics despite broader consumer caution.
- Housing Market Drag: High mortgage rates continue to suppress demand for housing-related goods, creating significant headwinds for the furniture and home furnishings sector.
The Ripple Effect: Economic Cause and Consequence
Persistent Inflation → Erosion of Purchasing Power → Consumer Strain → Slower Retail Sales Growth → Pressure on Corporate Margins → Potential for Economic Deceleration
Higher Interest Rates → Housing Market Freeze → Reduced Demand for Home-Related Goods → Sector-Specific Contractions → Broader Economic Headwinds
Unpacking Economic Terminology
The term ‘stagflationary pressures’ often arises when an economy faces both high inflation and sluggish growth. While the U.S. isn’t in full stagflation, the current dynamic of consumer strain amidst rising prices and slowing retail activity presents a challenging environment, demanding careful monetary and fiscal policy calibration to avoid a more severe economic downturn.
Key Economic Metrics: What the Numbers Tell Us
- Total Retail Spending (Oct): +0.2% MoM, +3.6% YoY (Source: CNBC/NRF Retail Monitor). This metric is crucial as consumer spending accounts for the majority of U.S. economic output.
- Core Retail Spending (Oct): +0.3% MoM, +3.4% YoY (Source: CNBC/NRF Retail Monitor). This excludes volatile restaurant spending, offering a clearer view of goods consumption.
- Consumer Price Index (Oct): +0.4% MoM (Source: Bureau of Labor Statistics). A key gauge of inflation, indicating continued upward pressure on prices.
U.S. Inflationary Risks Intensify
The Bureau of Labor Statistics recently reported that the Consumer Price Index (CPI) increased by 0.4% in October, exceeding economists’ forecasts. This persistent inflationary trend is a core driver of the observed consumer strain. Further exacerbating these concerns, a survey by the National Federation of Independent Business (NFIB) revealed that a net 37% of businesses plan to raise prices in the next three months. This figure represents the highest intent since July 2022, a period marked by significant energy price shocks following geopolitical events. Such widespread pricing intentions suggest that inflationary pressures are deeply embedded within the supply chain and business operations, rather than being merely transitory. The Federal Reserve faces a delicate balancing act: continue aggressive rate hikes to tame inflation, risking further economic slowdown, or pivot, potentially allowing inflation to become entrenched. The public’s concern is palpable, with inflation and the cost of living being dominant themes in recent midterm elections, influencing significant shifts in political power. For comprehensive market insights, visit StockXpo.
Retail Sector Policy Commentary
The retail sector, a bellwether for consumer health, is currently navigating a complex landscape shaped by both macro-economic forces and evolving consumer behavior. Policymakers are keenly observing trends like the slowdown in retail spending and the divergence between sectors. The resilience of electronics, driven by tech innovation and chip costs, contrasts sharply with the struggles in home furnishings tied to interest-rate sensitive housing. This calls for nuanced policy considerations beyond blunt monetary tools. Support for specific industries facing headwinds, or incentives for innovation, might become more prevalent if consumer demand continues to soften significantly. The NRF’s commentary underscores retailers’ efforts to offer promotions and value pricing, effectively acting as a private sector buffer against inflation’s full impact on consumers. However, this strategy can compress retailer margins, posing challenges to profitability and investment in the long term. A policy environment that fosters supply chain stability and addresses core input costs would ultimately benefit both businesses and the struggling consumer. For further readings on global economic shifts, see analysis from leading publications like Bloomberg Economics.
Navigating Consumer Strain: A Turning Point for Retailers
The current environment of consumer strain is more than a fleeting slowdown; it represents a significant turning point for retailers and the broader economy, forcing strategic adjustments in pricing, inventory, and marketing. As households prioritize value and necessities, businesses must adapt rapidly to evolving purchasing patterns and persistent inflation.
- Businesses will likely intensify promotional activities and value-based offerings to capture hesitant consumer spending.
- Investment in supply chain efficiency and cost management will become paramount for retailers to preserve margins.
- Sector-specific strategies will emerge, with tech continuing to push price increases while home-related goods face prolonged weakness.
How will this sustained consumer re-evaluation shape the holiday shopping season and influence economic projections for the coming year?
📊 StockXpo Analyst’s View
Market Impact: The deceleration in consumer spending, coupled with persistent inflation signals, presents a cautious outlook for equity markets, particularly for non-essential retail and housing-related sectors. Investors should anticipate margin compression for companies heavily reliant on broad discretionary spending, potentially leading to downward earnings revisions. Market liquidity could remain tight as the Federal Reserve continues its fight against inflation.
Sector To Watch: While the broader retail sector faces headwinds, the technology and electronics segments, particularly those tied to the AI boom and critical component costs, may show surprising resilience through strategic price adjustments. Conversely, home improvement, furniture, and luxury goods sectors are likely to continue experiencing significant contraction, making them key areas to monitor for further downside risk. Read more expert investment analysis.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE ECONOMY
China Trade Surplus Hits Record $1 Trillion Again Amid Global Rebalancing Calls
Published: Tuesday, November 10, 2026 · 6:17 AM
October jobs report: Unexpected Strength Signals Macro-Stability
Published: Monday, November 9, 2026 · 5:38 PM