Published: Wednesday, October 21, 2026 · 2:51 AM | Updated: Wednesday, October 21, 2026 · 2:51 AM
📊 10 views


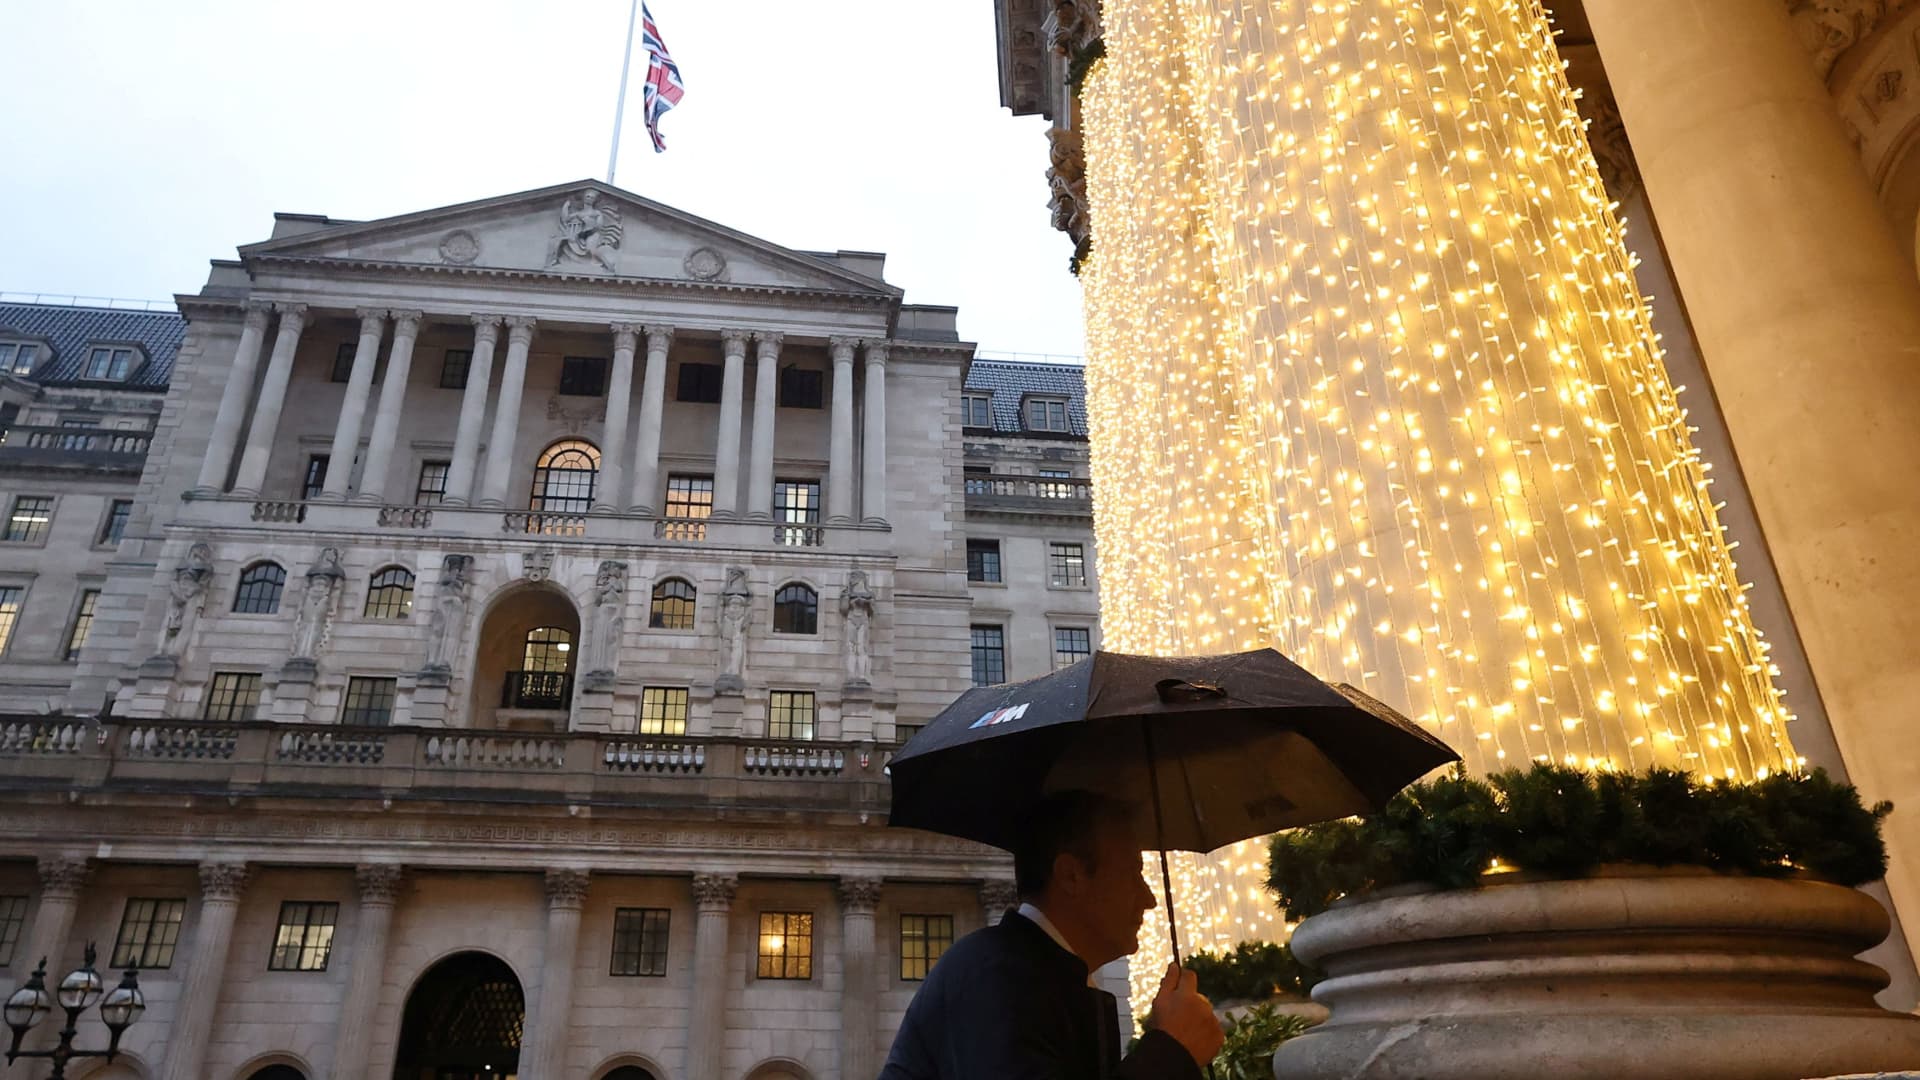
Britain’s economic landscape is bracing for further monetary tightening as UK inflation unexpectedly surged to 3.5% in September, intensifying pressure on the Bank of England. This latest data point, significantly above analyst forecasts, signals a persistent inflationary challenge that could ripple through global markets, particularly for countries sensitive to energy price fluctuations.
📊 Macro-Economic Strategic Insights
- Unexpected Rise. UK inflation hit 3.5% in September, exceeding Reuters’ polled economist forecast of 3.4% and marking the highest annual figure in a year.
- Fueling Factors. The primary driver was a sharp 29.8% surge in motor fuel prices year-on-year, reflecting global energy shocks exacerbated by geopolitical tensions.
- Rate Hike Certainty. Markets now price a 98% chance of a 25 basis point rate hike by the Bank of England next month, with further tightening expected by year-end.
The Office for National Statistics (ONS) confirmed on Wednesday that UK inflation climbed to 3.5% for the 12 months ending September, surpassing economists’ expectations of 3.4%. This figure represents the highest annual inflation rate recorded in a year, following August’s 3.1% and July’s 2.9% prints, demonstrating a consistent upward trajectory. The core of this acceleration can be attributed primarily to the surging cost of motor fuels, which saw a significant 29.8% increase over the same period, reaching levels not seen since August 2022 following Russia’s invasion of Ukraine.
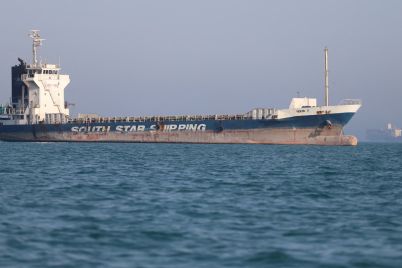
As a net energy importer, Britain remains particularly susceptible to external energy shocks. Current global dynamics, including tensions in critical oil shipping routes like the Strait of Hormuz, continue to exert upward pressure on energy prices, directly translating into higher domestic costs for consumers and businesses. While the British pound remained largely stable against the euro and the U.S. dollar, and U.K. government bond yields saw little immediate change post-data release, the underlying economic pressure is clear.
Scott Gardner, investment strategist at J.P. Morgan Personal Investing, observed that the recent headline inflation growth has ‘undone the progress we saw in the spring.’ He highlighted the accelerating services inflation, suggesting that ‘second-round inflationary effects beyond energy prices’ are beginning to manifest. This indicates a broader embedding of price pressures into the economy, making the Bank of England’s mandate to control inflation more challenging. The continued geopolitical conflicts further weigh on the UK economy, bolstering the argument for more aggressive monetary policy actions to restore price stability for sustained systemic growth, a sentiment echoed in Reuters’ reporting on global economic trends.
- Persistent Price Pressures: Inflation’s upward trend from July to September signals entrenched rather than transient factors at play.
- Energy Vulnerability: The UK’s reliance on energy imports makes its economy highly sensitive to global supply chain disruptions and geopolitical events.
- Monetary Policy Response: The Bank of England is under significant pressure to act, with markets nearly certain of a rate hike in the upcoming Monetary Policy Committee meeting.
The immediate economic consequences of persistently high UK inflation can be understood through a straightforward chain of cause and effect:
High Inflation → Increased Cost of Living for Households → Reduced Consumer Purchasing Power → Slower Economic Growth
Simultaneously, for monetary policy:
High Inflation → Central Bank Rate Hikes → Higher Borrowing Costs for Businesses and Consumers → Potential Dampening of Investment and Spending → Eventual Inflationary Control (but with potential growth trade-offs)
Central banks primarily target core inflation, which excludes volatile items like food and energy, to gauge underlying price pressures. The concern in the UK now extends beyond headline figures, as accelerating services inflation suggests broader second-round effects, complicating the Bank of England’s assessment of macro-stability.
The recent inflation report from the ONS provides critical insights into the UK’s economic trajectory:
| Metric | Value (September) | Significance |
|---|---|---|
| Annual Inflation Rate (CPI) | 3.5% | Exceeded 3.4% forecast, highest in a year, reinforcing rate hike expectations. |
| Motor Fuel Inflation (YoY) | 29.8% | Primary driver of headline inflation, highest since August 2022, highlighting energy import vulnerability. |
| Bank of England Rate Hike Probability | 98% (next meeting) | Market certainty reflects the severity of inflation and the central bank’s likely response. |
These metrics underscore the immediate challenges facing the UK economy and the likely direction of monetary policy.
UK Policy Commentary: Navigating Monetary Tightening
The Bank of England’s Monetary Policy Committee (MPC) faces a delicate balancing act. While the headline UK inflation figure unequivocally points towards the need for tighter monetary policy, the broader economic context includes concerns about potential recessionary pressures. Policymakers must weigh the imperative of price stability against the risk of stifling economic activity. As detailed by financial news sources such as Bloomberg Economics, central banks globally are grappling with similar dilemmas, but the UK’s specific vulnerabilities, particularly its energy dependency and ongoing labor market tightness, amplify the complexity of policy calibration.
Global Benchmarking: UK’s Energy Vulnerability
Compared to its peers, the UK’s position as a net energy importer renders it acutely exposed to international commodity price volatility. This structural vulnerability means global events, such as the U.S.-Iran war mentioned in the source, have a disproportionate impact on domestic price levels, particularly for fuel. While many developed economies experienced a post-pandemic inflationary surge, the UK’s persistent energy-driven inflation differentiates its trajectory somewhat from countries with greater energy independence or diversified supply chains. This makes the path to disinflation potentially longer and more challenging, requiring a multi-faceted approach beyond just interest rate adjustments, as often discussed in economic policy forums on economic policy.
The Persistent Challenge of UK Inflation: What’s Next for Stability?
The latest acceleration in UK inflation underscores the enduring economic headwinds facing the nation. The Bank of England is now under immense pressure to act decisively, with market expectations firmly set on further rate hikes. This situation demands careful navigation to prevent inflation from becoming entrenched while preserving the foundations for future systemic growth.
- The immediate future will likely see the Bank of England prioritizing inflation containment, signaling a period of continued monetary tightening.
- Businesses and consumers should anticipate higher borrowing costs, potentially impacting investment decisions and household spending power.
- The UK’s economic resilience will be tested as it contends with both domestic price pressures and unpredictable global energy markets.
Will the Bank of England’s upcoming policy decisions effectively anchor inflation expectations and steer the economy towards sustainable stability?
📊 StockXpo Analyst’s View
Market Impact: The persistent surge in UK inflation, particularly the embedded services component, reinforces a hawkish stance from the Bank of England. This will likely support the British pound in the short term, but higher interest rates could dampen equity market sentiment, especially for growth-oriented companies. Investors should brace for continued volatility and a potentially tighter liquidity environment as global central banks maintain their fight against inflation.
Sector To Watch: Energy-related sectors and defensive plays will likely perform better in this environment. Conversely, sectors heavily reliant on consumer discretionary spending or high leverage, such as retail and real estate, may face headwinds from reduced purchasing power and increased borrowing costs. The market will be closely scrutinizing future earnings reports for signs of margin pressure and shifts in consumer behavior, as analyzed in deep dives available on stock markets. For broader insights on market dynamics, our educational insights often cover these trends.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE ECONOMY
Housing Market Flashes Warning Signs Amid Fed Rate Hikes
Published: Tuesday, October 20, 2026 · 2:17 PM
AI Job Losses: A Historical Warning for Women in the Workforce
Published: Monday, October 19, 2026 · 8:04 AM