Published: Tuesday, October 20, 2026 · 2:17 PM | Updated: Tuesday, October 20, 2026 · 2:17 PM
📊 10 views


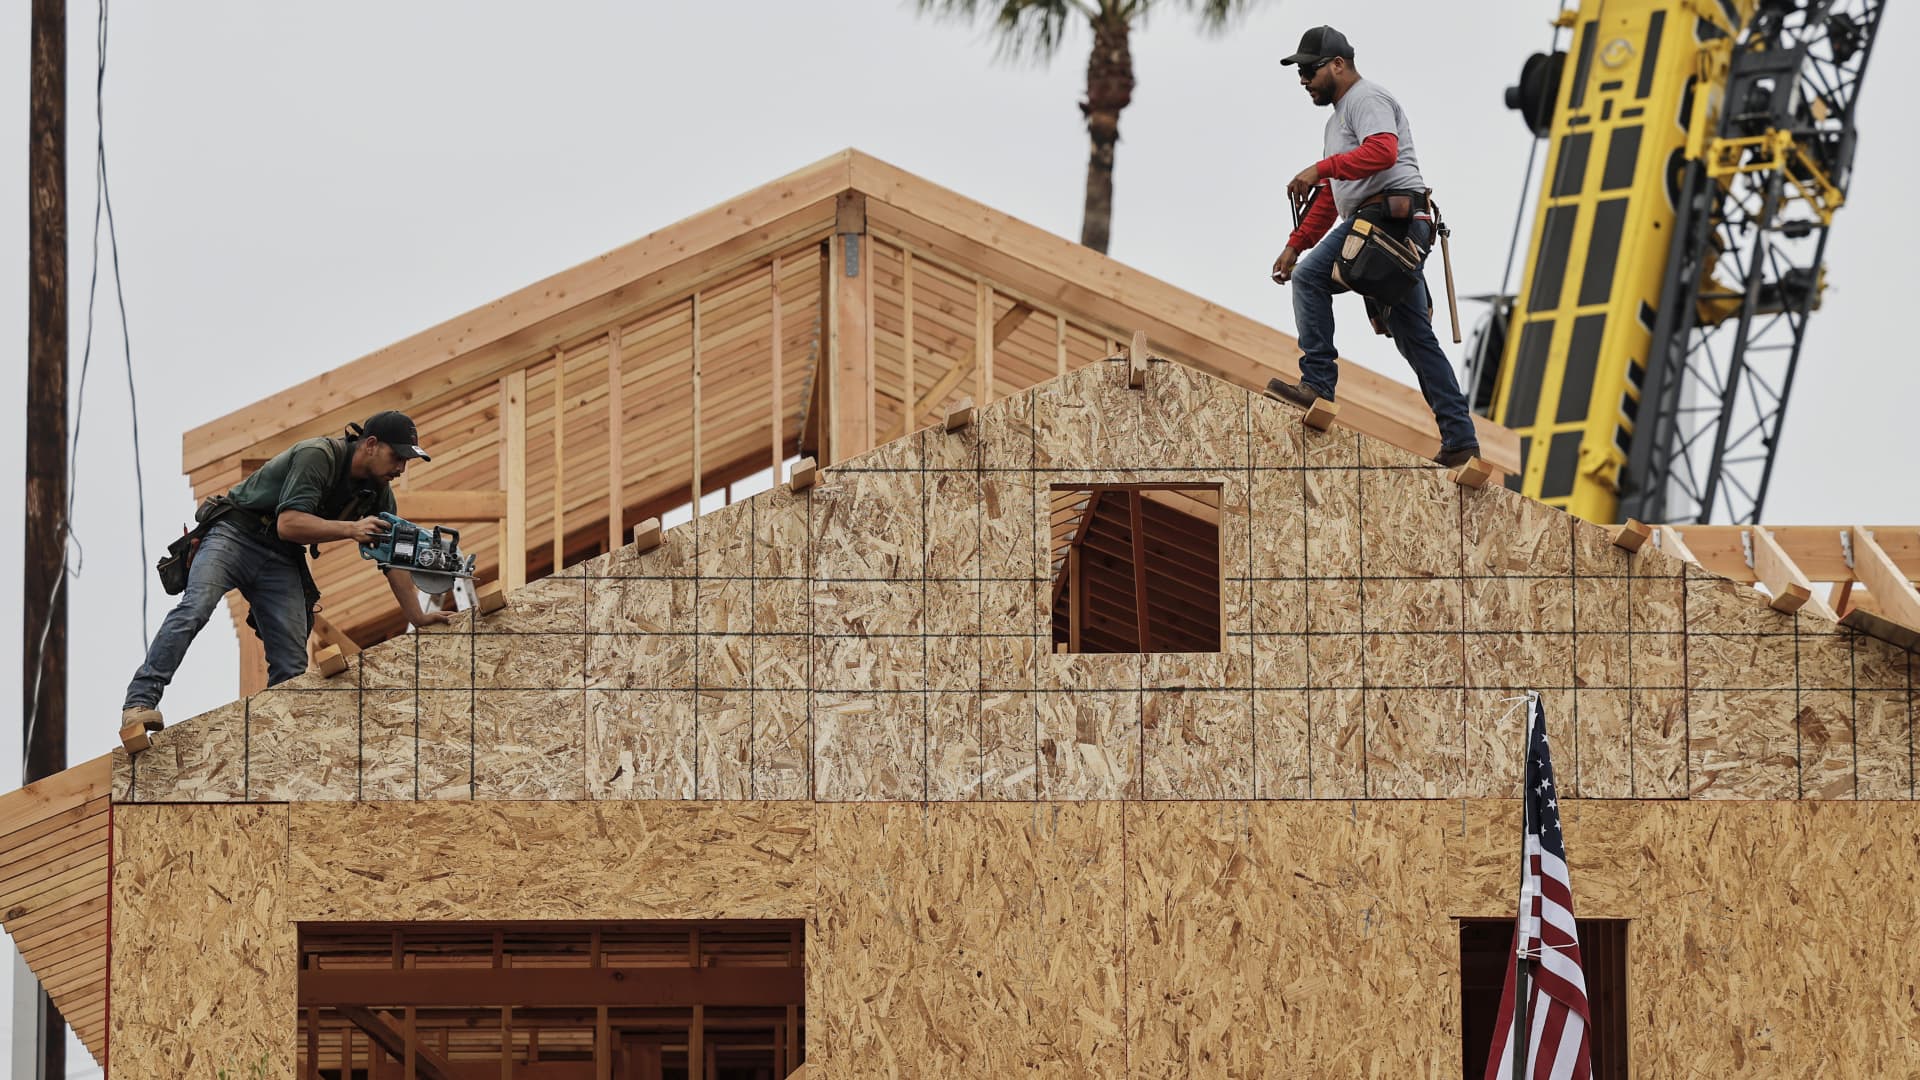
The U.S. housing market is sending clear distress signals, caught between persistent inflation and the Federal Reserve’s aggressive rate hike cycle. This significant downturn in a key economic sector presents a growing complication for policymakers, threatening broader macro-stability as affordability rapidly erodes across global markets.
📊 Macro-Economic Strategic Insights
- Deteriorating Metrics Signal Slump. Key housing indicators, including pending sales and housing starts, have plunged far beyond muted expectations, indicating a deep freeze in the sector.
- Affordability Crisis Deepens. Mortgage rates, now significantly higher than just five years ago, are severely impacting home-buying power and exacerbating an existing housing shortage.
- Policy Dilemma for the Fed. The Federal Reserve faces a challenging balancing act: taming persistent inflation while grappling with a weakening housing market that typically demands easier monetary policy.
Recent data has painted a stark picture for the residential sector, revealing a rapid deterioration in market conditions. In September, the National Association of Realtors (NAR) reported that pending home sales, a crucial forward-looking index, plummeted by 7.3% for the month and 11.3% year-over-year, reaching an all-time low in records stretching back to 2001. This figure significantly missed Wall Street’s expectation of a mere 0.4% decline.
Concurrently, Commerce Department data indicated that privately owned housing starts fell by a seasonally adjusted annualized rate of 5.2% in September, against an anticipated 0.4% decline. Building permits also disappointed, slipping 0.2% when a 2% gain was expected. Single-family permits specifically dropped 4% from August to 845,000, marking the lowest level since 2023. This widespread decline suggests that the aggressive stance of the Federal Reserve on interest rates is severely impacting consumer demand and builder confidence, creating headwinds for overall economic policy and macro trends.
The core of the issue lies with rising borrowing costs. The rate for a 30-year mortgage hovered above 7% for most of September, closing the month around 7.6% according to Mortgage News Daily. This is a dramatic increase from approximately 3% five years prior, which fueled the intense Covid-era housing boom. As Fwdbonds chief economist Chris Rupkey observed, ‘The housing market is about to go into a deep sleep unless Washington can do a 180 on its policies and make the cost of a new home more affordable.’
Lawrence Yun, NAR’s chief economist, emphasized the disproportionate impact of mortgage rates, stating, ‘Although job growth and income gains can support home purchases, housing affordability is more affected by changes in mortgage rates.’ The adverse conditions have also pushed home builder sentiment to 14-year lows, indicating deep pessimism within the industry. While Fed officials acknowledge the weakening housing sector, their primary mandate remains inflation control, with recent consumer and producer price readings showing few signs of easing. Some officials point to robust investment in artificial intelligence as a potential offset to weaker sectors, driving up costs for chips and electronics.
Ronnie Walker, an economist at Goldman Sachs, forecasts that residential investment will decline by 2.5%, 4%, and 1% over the next three quarters, with a possibility of steeper falls if mortgage rates do not ease. Goldman Sachs projects single-family starts to be around 875,000 in 2027, similar to 2026, while existing home sales are expected to hit 3.9 million, remaining 26% below pre-Covid 2019 levels. This stagnation is largely attributed to a ‘lock-in’ effect, where existing homeowners, benefiting from significantly lower mortgage rates (over 95% have rates below prevailing levels), are reluctant to sell and incur higher borrowing costs on a new property.
The Ripple Effect: Macroeconomic Consequences Unpacked
The deepening slump in the residential sector has profound implications for the broader economy, setting off a chain reaction across various segments:
- Higher Interest Rates → Elevated Mortgage Costs → Reduced Housing Affordability → Slump in Home Sales & Construction → Economic Slowdown & Potential Job Losses in Housing Sector.
- Persistent Inflation → Federal Reserve Rate Hikes → Slower Economic Growth → Reduced Consumer Spending → Broader Market Volatility.
- ‘Lock-in’ Effect → Reduced Housing Inventory → Stifled Market Turnover → Price Stickiness & Suppressed Demand → Prolonged Housing Market Stagnation.
The ‘lock-in’ effect, currently observed in the U.S. housing market, refers to the phenomenon where a significant portion of homeowners are disincentivized from selling their current properties due to having secured much lower mortgage rates than currently available. This creates an artificial shortage of inventory, even as demand softens, making the market less fluid and contributing to sustained high prices despite declining affordability for new buyers.
Key Housing Market Indicators and Projections
While the market faces considerable pressure, understanding the specific metrics provides crucial context for investors and policymakers. These figures illustrate the current contraction and future expectations for the residential sector.
| Metric | Latest Data (September) | Significance |
|---|---|---|
| Pending Home Sales Index | -7.3% MoM, -11.3% YoY | Reached an all-time low since 2001, indicating future sales declines. |
| Housing Starts | -5.2% MoM | Significantly missed expectations, reflecting decreased new construction. |
| Building Permits | -0.2% MoM | Reflects builders’ cautious outlook on future construction projects. |
| Single-Family Permits | 845,000 (lowest since 2023) | Indicates a substantial slowdown in new single-family home development. |
| 30-Year Mortgage Rate | ~7.6% (end of September) | Key driver of affordability challenges, significantly higher than recent years. |
U.S. Regional Trends in Housing Downturn
The impact of rising rates and diminished affordability is not uniform across the United States. While the overall national data signals a slowdown, regional markets exhibit varying degrees of resilience or vulnerability. Areas that experienced the most rapid price appreciation during the pandemic boom, particularly in Sun Belt states and popular tech hubs, are now witnessing more significant cooling and price corrections. Conversely, some historically less volatile markets or those with stronger underlying job growth may see a more tempered decline. However, the universal upward pressure on mortgage rates ensures that no region remains entirely insulated from the broader economic developments, leading to a nationwide adjustment in buyer expectations and seller strategies.
Inflationary Risks Beyond Housing
While the housing sector faces immense pressure, the Federal Reserve’s battle against inflation extends to other critical areas of the economy. The latest readings on consumer and producer prices provided little cause for optimism, with wholesale final demand goods prices showing a significant jump. This persistent inflationary pressure, potentially exacerbated by robust investment in artificial intelligence driving up costs for chips and electronics, limits the Fed’s flexibility to ease monetary policy despite the housing downturn. The challenge for the central bank is to navigate these multifaceted inflationary risks without triggering a more severe recessionary impact on the broader economy, a scenario closely watched by those tracking economic perspectives from leading news sources.
The Housing Market’s Pivotal Role in the Economic Outlook
The ongoing slump in the housing market is a critical variable influencing the broader U.S. and potentially global economic landscape. Its health is intertwined with consumer confidence, employment, and investment, making its current trajectory a significant concern for systemic growth.
- The swift deterioration in housing metrics underscores the severe impact of higher interest rates on consumer demand and construction activity.
- The Fed’s challenge to balance inflation control with housing market stability creates uncertainty for future monetary policy decisions.
- Long-term implications include sustained affordability issues and a re-evaluation of residential investment strategies by major players in stock markets.
How will the Federal Reserve navigate this complex landscape, balancing the need to tame inflation against the risk of further destabilizing a crucial economic pillar?
📊 StockXpo Analyst’s View
Market Impact: The persistent weakness in the housing market, coupled with the Fed’s hawkish stance, is likely to dampen overall market sentiment. Investors should anticipate continued volatility, particularly in interest-rate sensitive sectors. The ‘lock-in’ effect could further compress housing inventory, leading to prolonged market stagnation rather than a swift correction, complicating investment analysis.
Sector To Watch: The financial sector, particularly mortgage lenders and regional banks, will face margin pressure from reduced origination volumes and potential credit quality concerns. Conversely, sectors less reliant on consumer discretionary spending or those benefiting from AI investment, such as technology, might demonstrate greater resilience amidst broader economic uncertainty.
Financial Disclaimer:
StockXpo.com is a financial news aggregator and educational portal, not a registered investment advisor or broker-dealer. All information, news, and analysis provided herein are strictly for educational purposes and do not constitute investment, financial, legal, or tax advice. Investing in the stock market involves high risks, and past performance is not indicative of future results. StockXpo will not be liable for any financial losses or investment damages. Always consult a certified financial advisor before making market decisions.
MORE IN INSIDE ECONOMY
AI Job Losses: A Historical Warning for Women in the Workforce
Published: Monday, October 19, 2026 · 8:04 AM
India’s Equity Market Underperformance: A Liquidity Warning from Finance Minister
Published: Sunday, October 18, 2026 · 7:25 PM